IADS Exclusive Articles

IADS Exclusive: Interview with Blocher Partners - the true innovation is to deal with uncertainty
IADS Exclusive: Interview with Blocher Partners - the true innovation is to deal with uncertainty
Click here for a look into Blocher Partners
Blocher Partners (bp) was founded 30 years ago in Germany by Jutta and Dieter Blocher. From the very beginning, their approach was transdisciplinary. Along with their client needs, they added new competencies to their practice: interior design, product design, but also marketing and communication solutions. Thanks to their recognized know-how in the development of retail spaces, they were soon labelled as retail architects. They could offer clients holistic concepts, always putting the customer in the centre of actions and the thinking process. For getting in touch with their clients in an early stage and really understanding their needs, Blocher Partners lately expanded their business by the field design strategy: early in 2022 ‘Blocher Partners sens’ was established. Erik Schimkat who leads the new entity, is an interior designer who has specialized in co-creative design research methods. These are of great importance when it comes to unveiling unseen potential and pushing ideas towards new boundaries. For this interview we had the chance to talk to both Jutta and Erik about innovation and transformation in the retail business.
Innovation and transformation
IADS - What is your understanding of innovation for retail in general? How do you translate that into architecture? Do you sense any kind of acceleration or a sense of emergency, especially with Covid?
bp Jutta - Innovation should be broken down a bit. Working for the retail industry, but also for the hospitality business or even when creating offices, we can see what companies have in common: they have to deal with uncertainty when it comes to bringing a new project to life. Innovation really lies in dealing with this permanent uncertainty, and in the ability to turn it into a suitable experience. Sustainability and digitalization are also big forces being part of the process.When it comes to innovation, we need to be brave enough to try unprecedented things. They might work for one company and not for the other: this is exactly the context in which we can provide efficient methods and offer viable solutions.
bp Erik - Companies often ask us to help them be more relevant. They are aware that it will take bravery and boldness for them to be successful in the future, but the more we move on together, the shyer they become. That's really the biggest challenge for us. Forcing us to take a step back, Covid touched on a raw nerve and critically highlighted what was not working. It allowed us to really think about spaces and usage. But we wouldn't say we felt a sense of emergency as questions were already there, Covid was acting more like a booster even accelerating the process. Finding the right solutions is just becoming increasingly complicated.
IADS - What are the limitations of architectures, if any, for modern retail? What can it do, or can’t do, to fix the issues?
bp Erik - As everything is becoming digital, architecture is not the first step of a project anymore. Since consumers can now shop online wherever, whenever they want, architecture is the possibility for a brand to ultimately be able to convey a strong brand identity. Architecture gives retailers the power to really decide where they want to be visible.
IADS - How did the sustainability concerns change your practice, especially in retail?
bp Jutta - As a company, sustainability is in our minds for many years. For instance, our HQ built 12 years ago received the DGNB certification, which was something pretty unique at that time. Since then, our design approach has always been very sustainable. It’s also been part of our clients’ mindset for many years, and even more with Covid and the overall climate situation worsening.
Does the store of the future exist?
IADS - What is your personal view of the store of the future (if such a ‘concept’ makes sense to you)? Do you want to mention any ongoing project that would relate to that vision?
bp Erik - Actually such a concept doesn't really make sense to us. Although it is especially important for us to develop visions, it would be far too specific to have a single solution for a store of the future. There are certain guidelines and trends that have to be considered when developing a retail project, but in the end, our efforts are put into finding the specific solution for a specific client and its specific target group. As a company, we try not to use the word future as it can put us immediately in the past somehow. That said, we understand why there is this need for such a notion as it would represent an easy and global answer to many questions.
IADS - Architecture and online: how do you articulate both to cope with the customer omnichannel journey?
bp Jutta - We developed a digital unit within the company over the past years, consisting of a network of experts from the digital field. The purpose of such a unit is to both provide a seamless experience to our clients, and of course to help them deliver a seamless experience to their own customer base. Once again, we work on tailored solutions which will be very different from one retailer to another. For instance, Breuninger is very much advanced when it comes to online shopping, and they have a very good digital unit we closely collaborate with. The situation might be very different with another retailer.
IADS - Retail is about people - customers -, but also and equally importantly sales teams. How do you take them into account in your projects? And in the future now that staff retention and quality of work environment are crucial to retaining talents?
bp Erik - Our methods include having all experts and stakeholders at the table when kicking off a new project. The question of the sales teams comes usually late in the process, but we consider it crucial to include them from the early stage of a project, like any other stakeholder. They have a very valuable impact on the design process because of their unique position on the shop floor, providing products and experience to the customers. It might also be counterproductive to impose a new store design they will have to work with for years without involving them. Finally, because they feel seen and listened to, they often become ambassadors for the project
IADS - How do you manage creativity within your organisation? How are ideas generated and with what process?
bp Jutta - Our transdisciplinary approach is of some help in that matter, especially considering we need to make people work from our different locations, in Stuttgart, Mannheim, Berlin and India. We also have specific formats to develop exchange and creativity: we host something called ‘creative exchange’ where we invite external speakers on trends or innovation. We also have in-house talks bringing the whole company together. In addition, we're working on white papers, and we research ideas that we think are worth exploring. In the end, creativity works when we combine all expertise, and not only the design people as all people need to have a full understanding of what's going on.
IADS - Could you please tell us more about ‘Blocher Partners Sens’ new division? How are workshops and methods like LSP (Lego Serious Play) unique to understanding the client’s needs and developing an adequate project?
bp Erik - Blocher Partners Sens comes in at a very early stage of a project to work in a co-creative process with the client. Using different perspectives and methods, we are trying to find the best solution for the client. Everyone involved in the process is on the same page and the overall method ensures that everyone is taken into account. For example, the Lego Serious Play method allows everyone to have a voice, no one is louder or quieter. Everyone can come up with something creative (even when people are not part of the creative field) enabling them to have a valuable impact on the project. It starts with a perfect briefing in the early stage to really know what we have to work on, and the problems to be solved to reach a successful outcome.
We also use more creative methods allowing us to keep an eye on the overall project and make sure we are still on the right track compared to what was decided in the beginning. Blocher Partners Sens is also about communicating with all the project’s stakeholders, and about conveying the message of change. An evaluation is made after the project to assess what was good and what can be improved. It’s increasingly important in retail considering spaces are not set for years anymore.
Department stores and retailers
IADS - What is the role of a department store in 2022? How do you see its articulation with the city? In your view, is the European department store part of the 1% of public buildings (like a church, a city hall, a landmark...) or something else?
bp Jutta - It’s both, and something else! Department stores are city marketplaces where people can go without having a specific goal. Knowing that something is happening there is a good enough reason to go. The new KaDeWe flagship store in Berlin embodies this vision. The idea of public buildings fits with the idea of the department store: like a church or a landmark, it's a place where people find experiences.
In regard to this idea, Breuninger’s champagne bar is a very good example, as people don’t go there having shopping in mind, but for the experience. The EmiLu hotel we worked on in Stuttgart is another great example. The breakfast room, empty hence spooky most of the time, is open for everybody to have brunch until 4 pm. The place has been crowded since then. It shows that with more creativity, the hotel had a bigger chance to be in part of the city and become the “talk of the town”. This initiative also has a strong impact on the appeal of the hotel itself, as a place to stay.
IADS - How do we make sure that department stores will continue to be part of people’s lives? How is an architecture practice of some help?
bp Jutta - Whereas some became only ‘product portfolio’ over the years, department stores should go back to being places for experiences and discovery, their essence from the very beginning. Thanks to their size, locations and product offer, they have a true competitive advantage for experiences and discovery and a bigger chance to succeed when compared to other retailers. The challenge is more to make them understand the potential they have here.
Department stores can benefit from their great architecture (for some of them), from their restaurant offer making them a great place to meet friends. They offer a physical experience, and we are all craving for experiences.
IADS - Looking back: what did Blocher Partners learn with the various projects you ran with department stores? How working with department stores is different from other projects?
bp Erik - Department stores are very different as a lot of stakeholders are involved, adding complexity to uncertainty. On the other hand, they have more expertise, hence much more possibilities when it comes to what can be achieved. In the end, it might be more intense than working with smaller companies, but the results are often much more holistic experiences.
Contact:
Annette Willige
Head of Business Development
Tel: +49 711 224 82-452
Mobile: +49 152 54511169
Annette.Willige@blocherpartners.com
Credits: IADS (Christine Montard)

IADS Exclusive - Dubai Retail Tour: how are the franchised department stores doing?
IADS Exclusive - Dubai Retail Tour: how are the franchised department stores doing?
Check out the retail review in pictures here
*The IADS visited Dubai in early March for a joint meeting with the International University of Monaco and the American University in Dubai, who will be collaborating with the Association on Private Labels-related research topics. The IADS took the occasion to visit the Dubai Mall and the Mall of the Emirates to review the department store scene in Dubai, we have included pictures for your review.
Most of the department stores available in Dubai are operated through franchised agreements. Is there anything new in their approach, has any decoupling taken place, or, on the contrary, did the Covid-19 episode tighten the links with the mother companies? And to what extent does their service offering reflect the evolution of the market? We have tried to draw some conclusions from our visit in addition to the pictures that are available separately.*
Introduction: overview of the visited malls
The Dubai Mall, which opened in 2008, is the second-largest mall in the world, with half a million square meters surface spread over 4 floors and 1,200+ stores. Its many attractions (an aquarium and underwater zoo, a VR Park, cinemas and children’s activities, Bloomingdale’s, Debenhams and Galeries Lafayette department stores) made the mall a Dubai touristic attraction. It is operated by Emaar Properties, a public joint-stock company whose logo is ubiquitous on Dubai towers. Emaar Properties is primarily a real estate building company, involved in the building of the Burj Khalifa and the Dubai Fountain in Dubai, but also in other projects in Egypt, India, KSA, Syria, Turkey and Pakistan. It initiated mall management operations after completing the Dubai Mall.
The Mall of the Emirates, opened in 2005, is smaller, with 223.000 commercial square meters dedicated to 630+ boutiques, including Harvey Nichols, Debenhams and Level Shoes department stores or equivalents. It made the headlines upon completion with the opening of the world’s largest indoor ski slope and is owned by the Majid Al Futtaim Group, which specialises in mall management, retail, leisure, entertainment and hospitality.
When asked about the two malls, it is common to hear long-term Dubai residents mentioning that the Dubai Mall is great for a weekend excursion, but they usually do not see it as a staple destination for everyday purchases (due to the traffic and dimensions of the space). As a consequence, the Mall of the Emirates stands more as an option for a human-sized everyday shopping destination, even though it is probably suffering more than the Dubai Mall of the competition created by the new malls opened in other parts of the city since then. The Mall of the Emirates, which can not compete with Dubai Mall in terms of the number of attractions, also tries to provide a sense of luxury to local customers in terms of communication, overall feeling and atmosphere.
However, at the time of visit, the sentiment was that the Mall of the Emirates was feeling worn out when compared to the Dubai Mall, where everything, public premises, service spaces, and even mall attendants’ level of knowledge, felt in better shape and more looked after. This was exactly the contrary when entering stores, as levels of attention provided by retail staff in the Mall of Emirates was incomparable with the ones in Dubai Mall where no attention was given to visitors, reinforcing local customers’ opinion.
Debenhams (franchise operated by Alshaya Group) – Dubai Mall and Mall of the Emirates
Debenhams, the British department store chain founded in 1778, went into liquidation in December 2020 and closed down all 101 stores in the United Kingdom within June 2021. The brand was acquired by Boohoo in January 2021.
However, this did not impact Debenhams’ partner in the Middle East, Kuwaiti group Alshaya, which started the partnership as early as 1997. Alshaya has since the bankruptcy announcement made a deal to retain the franchise rights with Boohoo, and operates a total of 23 in-mall stores in Kuwait, KSA, UAE, Bahrain, Egypt, Oman and Qatar, in various formats. In Dubai, there are 6 locations: 3 department stores (Mall of the Emirates, Dubai Mall, City Centre) and 3 Debenhams cosmetics stores.
IADS visited the two Dubai Mall and Mall of the Emirates locations. The feeling was rather different from one location to another, and paradoxically, the Dubai Mall location felt more worn than the Mall of the Emirates One, probably because of its smaller dimensions.
Debenhams Dubai Mall
The store extends on one floor with very few windows and a rather classical store planning: cosmetic space at the entrance (a black generic concept with logos), then RTW (M, W, kids) and other categories.
In-store fixtures include brands-separating walls in the central section of the RTW area, giving a somehow suffocating feeling, reinforced by the very dense visual merchandising, with overcrowded racks. As a consequence, it gave a ‘bazaar’ feeling, reinforced by ubiquitous price reduction signs. At the time of visit, the location was empty with staff busy unboxing products and not paying attention to visitors.
Debenhams Mall of the Emirates
The store spans over 3 floors and gives a much more positive feeling than the Dubai Mall location, at least on the ground floor (cosmetics with brand concept corners, lingerie and accessories). Staff is omnipresent, welcoming and eager to help visitors. Lighting and the feeling of space are refreshing and give a very positive impression.
The 2 other floors are dedicated to fashion: Women’s on the 1F and Mens, Kids and Home on the 2F. Women’s fashion was overloaded with products and dense VM, however, this did not seem to deter customers from buying (Debenhams is popular in Dubai for middle-income families looking for bargains and low prices). On the upper floor, the feeling, especially in the home section, was clear and nice. In both 1F and 2F, staff was non-existent or not interested in helping or even saluting customers.
No specific services were mentioned or advertised at cash desks in both locations. The Debenhams website for the Middle East, announced by Alshaya for early 2022, is still not active at the time of writing.
Galeries Lafayette (franchise operated by Admic) – Dubai Mall
Galeries Lafayette and BHV department stores in the Middle East are managed by Admic, a Lebanese company founded in 1996. Galeries Lafayette in Dubai Mall, spanning over 21,500 square metres and 3 floors, opened in 2009 and is easy to find thanks to the mall’s public signs as a significant anchor.
The store is also extremely visible from afar, especially because of the ubiquitous branding visible from the atrium. It also emphasizes that the store’s main logos are not updated, clashing with the current “Time the time to smile” campaign on the windows with the new Galeries Lafayette logo introduced in 2017. This can be confusing for customers, especially the ones already familiar with the French locations or website, and who might be surprised to see an old-school logo on the building (shopping bags display the new logo).
The ground floor is dedicated to luxury accessories and international brands (LV, Gucci, Dior, Marc Jacobs, Valentino…) in peripheral sections, and low-rise corners with brands’ concepts dedicated to cosmetics in the centre, giving overall visibility, and a feeling of luxury and space.
On the first floor, dedicated to fashion (M, W) with flexible walls which can be moved to change brands or sections, there is a mix of local and international brands’ shop in shops fitted with their own concepts (Missoni, Ba&h…). It is therefore really possible to have 2 different feelings, one being that local brands are overrepresented, and the other one being that GL displays its savoir-faire in terms of fashion merchandising. The dressy space (an important market in the Middle East) is represented by Etoile La Boutique, a retailer specialized in evening gowns, and an extremely good-looking and inviting wedding dresses space at the entrance. The shoe space on the same floor is somehow less efficient as it is difficult to see the products. The Men’s section is also equipped in a flexible generic concept, with the exception of a few brands (Pal Zileri, Hugo Boss, Hackett, Polo Ralph Lauren).
The second floor is dedicated to kids, home and gourmet. The whole floor is in low rise concept, independently of the category, to make the gourmet space visible and accessible, which further emphasizes the logo mix-up (pre-2017, post-2017) in the Gourmet section.
Cash desks are all located in peripheral locations, forcing sales associates to ask customers to follow them to finalize sales, which seems surprising to ask of demanding Middle Eastern customers. At cash desks, no specific services are mentioned or advertised.
Bloomingdale’s (Dubai Mall) and Harvey Nichols (Mall of Emirates) (franchises operated by Al Tayer)
Al Tayer is a UAE-based conglomerate founded in 1979, operating in automotive, retail, hospitality, services and entertainment in the Middle East. It opened the largest Harvey Nichols store outside of the UK in 2006 in Mall of the Emirates, and the first Bloomingdale’s store outside of the US in 2010 in Dubai Mall.
Bloomingdale’s in Dubai Mall
Bloomingdale’s Dubai extends into 2 sections: a 3 floor department store dedicated to fashion, over 14,600 square metres, and a home store on the lower ground over 5,400 square metres (not visited). Like Galeries Lafayette, located in the opposite side of the Dubai Mall, it is extremely visible and accessible through an appropriate signage.
The ground floor is dedicated to cosmetics in the central section, and luxury accessories and shoes (but also a Gucci store with all categories) in a “drum”, with direct access to the valet parking. The size, level of attention and energy in the Cosmetics section suggests that this is where the turnover is made. Sunglasses and custom jewellery are also presented in this section but are hardly visible and not really appealing. In the “drum”, all brands are displayed in their own concept, with the exception of a generic space in the central Accessories and Shoes section where some brands are repeated (Saint Laurent, Valentino, Balenciaga).
On the first floor dedicated to Women’s fashion, only Gucci, Moncler and Keepsake have their own concepts, the rest of the brands are presented in generic sections on specific racks (which are different from the Men’s section ones). The dressy and luxury section is not specifically outstanding in terms of visual differentiation when compared to the rest of the floor, and the personal shopper’s entrance is not appealing. What is striking is a combination of smart initiatives (the Chanel fragrance chariot in a strategic location near the escalators) and the lack of services, including seating areas.
The second floor dedicated to Men’s and Kid’s is visually different, and most brands have their own concept. The personal section is appealing, with a barber, a fragrance section, and many seating spaces where to spend time. Men’s shoes are presented in a generic section and there is also a contemporary space, poorly accessible and not engaging due to the way the space is structured. The Kids section is experiential and festive, with a specific ambience and non-brand-dedicated staff.
At no point during the visit were services or Covid-related instructions mentioned. Also, the Visual Merchandising was somehow confusing and did not help to make products visible. This is all the more curious that the VM at Harvey Nichols is extremely efficient, and an executive at Al Tayer explained to us that both stores were managed by separate teams.
Harvey Nichols Mall of the Emirates
Harvey Nichols extends on 3 levels at a corner of the Luxury avenue. Signage in the mall and overall visibility is probably less efficient than for Bloomingdale’s in Dubai Mall.
The ground floor is dedicated to Accessories, Shoes and Beauty and all brands are displayed in their own concept. Visual Merchandising is extremely efficient and the space is one of the best seen during the visit.
The first floor, dedicated to Women’s fashion, is clear, welcoming and spacious. The play on colour in the atrium is similar to what Saks Fifth Avenue has done in New York, and the multi-brand space is commercially efficient. Visual Merchandising is exemplary.
The second floor, dedicated to Men’s and Kids, displays shop in shops in peripheral and central sections, with a very good display of shoes. Some questions are raised by the brand zoning (e.g. Gucci kids near Kenzo adults).
Harvey Nichols was one of the most appealing locations visited during this trip. It is (justifiably) seen as a reference by brands when trying to enter the Dubai market.
Level Shoes (original concept from Chalhoub Group) – Dubai Mall
Chalhoub Group, founded in 1955 and specialized in fashion and luxury retail operations in the Middle East, has launched Level Shoes in 2012 in the Dubai Mall over 9,600 square metres. It is not really a department store nor a shoe shop, but a “shoes & accessories district” and Chalhoub Group refurbished it in early 2020 in a spectacular fashion.
All international brands are presented either in their own-concept shop in shops in peripheral sections or in luxurious generic areas in the centre. The overall feeling is not far from a large and luxurious department store, with many welcoming seating areas, popup zones, and dedicated salespersons (attached to each brand).
Level Shoes is the only space visited where Click & Collect is advertised and proposed with appropriate signage. When IADS discussed this Click & Collect topic (or its lack of in most of the visited locations) with the Dubai Mall General Manager, he mentioned that this was the kind of service that the Dubai Mall was willing to develop at its own level, and a new section is currently being developed to welcome and accommodate customers coming to retrieve their click & collect purchases in a Dubai Mall premise, and not in each shop.
*Is Dubai still worth a retail trip? Yes, to see to what extent the need for services and retailer brand differentiation is not the same from one region to another. The most striking point during the visit was the fact that many brands were over-represented due to the multiplication of points of sales: in Dubai Mall only, Saint Laurent is represented in the Bloomingdales Accessories section (shop in shop + generic), in the Bloomingdales WRTW section (racks + double shoes/accessories exposure), in the Bloomingdales MRTW section (racks + additional shoe section), in the Level Shoes area (shop in shop) in addition to the brand’s own retail store, leading to a total of 7 locations for this mall only. Is it enough for local retailers to stand out with an international offer that can be available somewhere else?
Our conversation with the Dubai Mall General Manager suggests that they anticipate that the need for services and additional care, that is spreading in the rest of the world, is growing and that they might be looking to be part of the solution. Department Stores might want to follow what they do when it comes to Click & Collect and, above all, how they articulate it in terms of business model with brands, as this might come as an inspiration.*
Credits: IADS (Selvane Mohandas du Ménil)
IADS Exclusive - Le Printemps revamp in Paris: what is new?
IADS Exclusive - Le Printemps revamp in Paris: what is new?
To view our photos of the Printemps revamp click here
Introduction
*Paris has gone through significant retail upgrades in the past 2 years, with the opening of La Samaritaine in June 2021 and the general stores and branding overhaul at Galeries Lafayette in September 2021.
In the meantime, the global events that have been unfolding one after another are blurring the visibility when it comes to getting back to normal touristic flows, a situation that has forced all major players in Paris to rethink their approach almost in real-time.
Apart from launching “7ème Ciel”, which is a second-hand and circular fashion initiative (quite different both in terms of spirit and business model when compared to Re-Store from Galeries Lafayette), Printemps has remained silent since the arrival of Jean-Marc Bellaïche, the new CEO, in March 2021 and the subsequent store closure plan in French regions that was announced.
This is the reason why the relaunch of Printemps is significant, both in terms of brand identity, customer approach and new services offered. We have visited the new Haussmann stores and reviewed the novelties for you, drawing some comments from our visit in addition to the pictures that are available separately.*
The Printemps situation in a nutshell
Printemps, founded in 1865, currently operates 29 stores, 20 with the Printemps brand (16 in direct and 4 in Franchise) and 9 with the Citadium brand, after having closed respectively 4 Printemps stores and 3 Citadium stores in 2020-2021. The group achieved a turnover of €1.5 bn in 2021, a far cry from the estimated €1.7 bn turnover from 2019 but increasing +38% compared to 2020. The CEO mentions that the 2021 turnover is -12% on comparable days (i.e. on the days when Printemps was opened in 2021) compared with 2019, which gives an idea of the tourists’ absence impact. In 2019 70m customers visited the Printemps stores, 20m of them in Haussmann only.
The goal of the Printemps brand, offer and services revamp is to regain local customers (2/3 of the customer base, with locals already growing in 2021 +10% vs. 2019 overall and +15% in Haussmann) and attract US, Middle East and European customers, through new customer journeys, starting with “less retail, more F&B and entertainment”.
The revamp took place on the 19th of March, the Spring day, with a “Tout commence au Printemps” catchphrase, playing on the meaning of Printemps (Spring in French, which means that the slogan is akin to “Everything starts at Printemps”). This allows the company to play on the concept of renewal, which is quite catchy these days when customers are tired of the Covid-19 related restrictions and are also looking to escape the gloomy news of the war in Ukraine. It is also an efficient way to emphasize all the “first times”, both in terms of advertising messages (my first emotion, my first shopping spree…) but also present Printemps as an innovative company which led the way in many aspects of modern retail (for memory, Printemps was a founding member of the IADS in 1928). In a nutshell, Printemps presented their new initiative as a moult, to complete the springy message.
A new in-store experience
The company has decided to review its logo (a stylized P which also evokes a heart), colour code (green, white and gold) as well as its tagline (everything starts at Printemps). The new advertising campaign is quite dynamic and transmits a lot of positive energy.
The in-store execution is quite effective, both in terms of signage and the use of the green colour, vivid and visible from afar, which is dotted across the floors, be it via the in-store displays, elements of décor, but also the products developed in collaboration with brands. At the entrance of the store, the information desk has been decluttered and is quite welcoming. The staff has been well briefed, 100% of them saying hello to all customers and showing enthusiasm even 1 week after the re-opening, which suggests that sales and traffic were extremely sluggish prior to this welcome rebranding and upgrade.
10 new permanent concepts have been introduced across the 3 buildings (Women’s, Men’s, Kids and Home) mixing retail, experience, leisure and F&B, also making the most of the building specificities:
- In the Women’s store: La Coupole (6F), a spectacular animation area mixing a 6-months long pop-up zone with a restaurant, Ready Up (4F), an area dedicated to promising students in fashion and design, Hors Saison (3F), a space where clothing from former seasons are sold at a discounted price, and L’Endroit (2F), a comfy designers’ multi-brand space replacing the former Maria Luisa concept store,
- In the Men’s store: a new “Café vert” area (GF), mixing coffee and plants, and an experiential shop-in-shop operated by Au Vieux Campeur (-1F), an iconic Parisian outdoor retailer,
- In the Kids and Home store, L’Appartement de Made in Design (2F), a co-op space selling design items in a home-like environment, and a new retail concept on the Beauty lower floor.
What’s new in the Women’s Store
La Coupole Plage on the 6th floor: this place makes the most of the Art Deco cupola, which housed a brasserie in the past and its name makes a reference to “Paris Plage”, the townhall yearly initiative which transforms the Seine riverbank into beaches.
The F&B area has been quite reduced and pushed on the edges, which also allows emphasis on the presence of terraces (4 terraces which can each accommodate 6 customers) while providing a sense of exclusivity and luxury. The restaurant is managed by a Chef, who co-develops with a food personality a new menu every 6 months. For the first iteration, a food critic who recently published a recipe book has been invited.
The freed space has been dedicated to an experiential retail zone, which is supposed to change every 6 months. For now, the whole area is dedicated to swimwear in a very immersive environment which is quite well executed.
Also, the whole area easily communicates with “7ème Ciel” on the 7th floor, the second-hand space that was opened in September 2021. This zone also opens on the rooftop of the store, with a food truck-like F&B offer, giving a feeling of lightness and joy that was catalysed by the sunny weather. Even though La Coupole takes time to be reached, either via escalators or lifts, it is well indicated across the store, and impossible to miss. It might be more effective in terms of traffic generation than the brasserie, at least in terms of traffic spreading across the day.
Ready-up! On the 4th floor and directly in front of an escalator, this space is the result of a partnership with Campus Mode (a structure federating fashion schools in Paris) and is dedicated to fashion students. There, they have the possibility to take part in conferences, explain their work, expose their pieces and sell them with 3-months long popups. 19 talents will be promoted for a period of 3 months, with 3 to 4 participants per session lasting 15 days.
During the visit on a Sunday, the space was not especially welcoming to customers, as students gathered to congratulate themselves, creating de facto a world where it was difficult to enter if not invited. Also, the very interest of the products can be questioned, as well as the business efficiency of such an initiative.
Hors Saison: this clever initiative on the 3rd floor aims at selling former seasons stocks on 200 sqm in a beautiful space, and singing the tune of social responsibility and care for the environment, instead of appealing to customers with low prices. Brands represented there range from APC to Victoria Beckham, and prices can go as low as -60%.
The space is beautiful and appealing, however, its location and structure make it less inviting than other initiatives. During the visit, there were no customers and sales staff were clearly desperate to have anyone coming in.
L’Endroit on the 2nd floor: replacing the former fashion multi-brand store Maria Luisa, this space emphasizes a selection of edgy designers in an apartment-like setup, where photographers are invited to display their works.
Salespersons are extremely well trained and efficient, as several sales were concluded during the visit. They know the products and brands (which is not the case in other parts of the store) and also mentioned that they were extremely happy since the rebranding of the store, as this immediately translated into an increase in terms of customer flow and purchases. Printemps CEO mentioned that traffic jumped +20% during the week of the reopening.
In the women’s building, the ground floor also displays a new selection of gifts and “easy” products, called Le Joli Cadeau, but which is not referenced as a new concept per se. This space was formerly dedicated to a multi-brand premium leather goods area.
What’s new in the Men’s Store
Le Café Vert on the ground floor, open as early as 8 am (before the store opens), aims to become a rendezvous point with a healthy and qualitative offer, enhanced by plants dotted all across the space, appealing to the need for nature that everyone experienced during the various lockdowns.
The café is operated by Brûlerie Belleville, a local Parisian coffee roaster, but the space will be also offering an aperitivo time at the end of the day, and the décor is set up with Kaki (a hydroculture plant specialist), knowing that all plants on display can be purchased by customers.
Au Vieux Campeur on the lower floor is truly a premiere, as this is the first time that this iconic Rive Gauche retailer makes a partnership and expands outside of its own stores. Au Vieux Campeur has been founded in 1941 and is known by every Parisian who had to purchase anything related to outdoor activities in the past (think a high-end Decathlon staffed by proud specialists). The store is 400 sqm wide, highly immersive and is organised by the universe: climbing (with a 6 meters high climbing wall, very visible from the ground floor, that can be used by customers), trekking, sailing and a library. Testing surfaces for shoes are also available. Dedicated Au Vieux Campeur salespersons also allow customers who might not find what they are looking for in the store, to the entire Au Vieux Campeur catalogue via a marketplace system.
What’s new in the Kids and Home Store
Many new beauty initiatives are available on the lower ground floor:
- Beauty food: a holistic cosmetics zone part of L’Officine (a space dedicated to dermo-cosmetics) where food complements are sold in addition to cosmetic routines by specialized (and exclusive) brands such as Agapem (period alleviating treatment), Apnee (collagen in powder), So Much (emotions regulating coffee) or Dijo (infusions with intestinal ingredients).
- Partnership with Kisskissbankbank (a crowdfunding initiative), which enables Printemps to contribute to the development of new brands, through a contest with an independent jury selecting 3 new brands which will be promoted by being introduced to the “Green market” area in Le Printemps.
- Large areas dedicated to manicure, pedicure, brows, as well as a large space gathering hair products and salon: such services were already available before the revamp but were not gathered in a single place. This organisation makes the offer powerful and efficient.
- Face 2 Une: a spa developed with the Face 2 Une beauty tech brand, proposing no gender services through manual massages and machines.
L’appartement with Made in Design on the second floor: Made in Design (owned by Printemps) is an online design retailer, often curating a selection of brands but also developing its own products. L’Appartement is an initiative where selected designers are invited to make a selection in the Made in Design catalogue and create a physical and immersive point of sales for Made in Design, while also bringing a new experience to Printemps.
And the Metaverse?
Printemps has also developed a phygital initiative, with an immersive virtual store accessible from their website showing a selection of products as well as exclusive collaborations (overall, the e-commerce store has increased its offer by +31% vs. 2019). In the event of the purchase of an exclusive product, customers will enter a contest to earn an NFT, which will, in turn, give access to another contest where the winner (1 out of 30 NFT winners) will receive the original piece of art from the artist who has designed the atrium and the 7ème Ciel art tunnel in the Haussmann store.
Interestingly, there is also an initiative with DressX in the form of a pop-up on the ground floor, which allows customers to buy virtual dresses for their Instagram or other social media pictures. However, after checking in person the offer, the pop-up does not offer anything more than what can be purchased online directly.
For customers who are not into such subtleties, 500 exclusive pieces have been developed with brands ranging from Loewe and Sandro to Logan and Lacoste, displayed in a spectacularly redesigned Atrium at the centre of the Women’s floor. However, during the visit, sales staff were not really inviting and busier making comments about customers who had left the space than taking care of those present.
What to think about this revamp? Execution is excellent and the feeling of renewal across the 3 stores is clearly there. Printemps is upping its game and getting back into the Parisian fight for local customers, after a period when it was lagging behind. They have based their whole campaign on the promise of permanent non-retail animations (conferences, workshops, DJ sets, etc…) which could translate into an effective traffic-driving strategy if properly conducted. The main question is therefore to know if Printemps will be able to maintain the momentum on the long-range and keep teams mobilized?
Credits: IADS (Selvane Mohandas du Ménil)
IADS Exclusive - Innovative Thinking Series: IADS interview with Scot Case (NRF) on Sustainability
IADS Exclusive - Innovative Thinking Series: IADS interview with Scot Case (NRF) on Sustainability
Introduction
The IADS interviewed Scot Case, the Vice President of Corporate Social Responsibility and Sustainability at the National Retail Federation (NRF), who has been in the sustainability space since the mid-1990s. From his experience, sustainability is the intersection of three key aspects: business, environmental, and social issues.
Early on in our conversation, Scot shared that the sustainability space is constantly evolving. While in the 90s, the main focus regarding sustainability topics was around recycling, today the focus has shifted towards human rights and climate change issues. Nevertheless, it is worth noting that all of these topics are related in some way, it just depends on what is seen as important and to which player. It is much like an iceberg, only a piece of the issue is unveiled, the part that is being centred on by businesses or consumers, but not the much larger contributing factors that remain unseen or below the surface. A retailer, an individual, or a consumer will focus on one aspect of sustainability and not realise that all issues are intertwined and connected to a challenge that is much bigger than meets the eye.
Retail at the centre of sustainability
IADS - You made it clear at the 2022 Retail’s Big Show in New York that the word ‘sustainability’ is diluted. How do you personally define sustainability when applied to a retail business?
Scot Case - When we started this initiative at the National Retail Federation, the first key issue was to decide what an industry-wide definition looks like. After lots of conversations with retailers, we boiled it down to a simplified definition. Sustainability is creating net positive environmental, social, and community benefits. This net positive concept is similar to how one measures whether a business is profitable or not. At the end of the year, some parts of your business are making money, some parts are kind of breaking even, and some parts are losing a little bit of money. That's what sustainability looks like as well. Some aspects of the business are clearly generating all sorts of benefits and profitability. Other times there will be some costs from an environmental or social impact. But overall profitability is necessary to be able to fund the sustainability projects and initiatives that contribute to making the world a better place.
When companies start to consider sustainability as part of their business, they might only see it as a cost, but rather they should consider it as an investment. At one time retailers probably saw cash registers as a cost, but in the end, such initiatives are contributing to the longevity of the business and sustainability should be seen as the same. Retailers that consider sustainability as an investment are the ones that are prospering. The challenge is that this is a long-term investment, but some of the most significant players in the sustainability space started their journey 15 to 20 years ago, and now the rest of the industry is struggling to catch up.
IADS - You once said that “retail is at the centre of sustainability”. Can you elaborate on this opportunity and influence that retailers have in this space?
SC - Retail is not just the centre of sustainability, retail is the centre of the universe. Sustainability is just embedded in the space. A retailer's ultimate job is to find the best products to meet the needs of the consumer. Consumers want more sustainable products now that they understand that every single purchase has hidden human health, environmental and social impacts. Retailers are best positioned to understand where the best products are, what the hidden human health, environmental, and social impacts are, and then share that information with the consumer. Retailers have access to all the information and ultimately that's what retail is all about. Sustainability is just an additional layer of the story and an additional layer of information.
Advice to retailers: beginners to advanced
IADS - For retailers that have just started investing in sustainability initiatives, what do you believe is the most important area for them to focus on first?
SC- Albert Einstein suggested that you spend 90% of your time defining the challenge. You can achieve this by asking the right questions to figure out what information your consumers are seeking so that you as the retailer are asking the right questions of your suppliers. The reality is that not everyone has the answers yet, and that's okay! The main thing is to be honest and transparent. It is okay to include consumers in the sustainability journey by sharing that the business is attempting to trace the entire carbon footprint of everything sold or trying to trace the origins of all the cotton used, and the challenges that the company is facing to reveal such information. It is important to show that you are committed to making this kind of information available so consumers can make better and more informed decisions. That is an honest story that consumers tend to respond to. Don’t let perfection get in the way of getting started, no retailer started perfectly out of the gate. The history of retail is a history of failing, learning, and doing it again.
IADS - For retailers that have been working hard on their sustainability journey for years and feel like they are no longer playing defence when it comes to CSR topics, where can they go next to be leaders in the space?
SC - I think that even the largest players have realised there are limits to what they can accomplish on their own and that's why, at the National Retail Federation and at IADS, retailers are learning that maybe they should be collaborating on some of these things. Some of these issues pop up in pre-competitive spaces, so there are opportunities for the industry to be sending clear signals deep into supply chains, to consumers, and to regulators to understand what can be accomplished currently, what areas need attention, and where working together is necessary. I think the largest players have learned to collaborate to make sure we have the best sustainability metrics and standards for sustainable fashion, sustainable electronics, or sustainable luxury products. Collaboration is the fastest way to solve problems in the space.
Sustainable department stores
IADS - In your opinion, what does the sustainable department store of the future look like to you? How does it operate? Will it sell ‘new’ products or only offer circularly produced products? How will it achieve profitability?
SC - I think when you design sustainable retail and the department store of the future, you start immediately with your own operations. The focus is on creating a maximum benefit meaning reducing your energy use, going to a hundred percent carbon-free energy and carbon-free logistics. It is important to make sure it's embedded at the core of the business and what you directly control. The next phase is having very effective programs to work with suppliers so that suppliers clearly understand your definitions of sustainability, the metrics that you're using, how you're evaluating their products and their sustainability performance, not just how they're making those products.
Another piece is communicating really effectively with the consumer. Consumers have multiple definitions of sustainability. So it is the retailer's job to understand that and to be able to match what they have available for sale to influence consumer decisions towards sustainability. Retailers are exploring business models, such as rental, that reduce all of the environmental and social impacts of making a garment, while allowing the retailer to sell the same product multiple times.
The future of sustainability in retail
IADS - What are some trends or technologies that could empower sustainable retailers? What companies or solutions should retailers be looking to invest in? (RFID, connected garments, product passports, resale marketplaces, …)
SC - I think you've just named a couple of them. So a lot of these are blockchain-based. The ability to track with blockchain where the cotton from a shirt came from, where the factory was, what kind of dyes were used, who sold it, or when the item was returned or recycled is the key to success in sustainability. Any of these technologies that are collecting, validating, verifying, aggregating sustainability data are going to be really important for moving into the future.
We are also looking at the redesign of supply chains to meet the needs of those consumers, fascinated with the circular economy. Therefore reverse logistics gets very fascinating because it is no longer only about how to make sure these products that the consumer bought and no longer wants and needs doesn't end up in a landfill or in some foreign country being burned. It is about the ability to track, measure, quantify, aggregate and then make good use of that information.
Is there anything else that you would like to share with our members about projects that you are working on, advice you can offer, or opportunities in the space that we have not covered yet?
SC - I actually have a request for retailers all around the world to be sharing their sustainability stories with the rest of the industry. These really are, in many ways, pre-competitive concepts. So I encourage IADS members to share their sustainability opportunities, challenges, risks, headaches, and solutions. We're asking the same of our members so that we can build a global solution for the retail sector. As retail is the centre of commerce, I think there's a real opportunity for retailers to redefine what a sustainable future looks like.
Credits: IADS (Mary Jane Shea)
IADS Exclusive - Retail Review: Beauty Concepts
IADS Exclusive - Retail Review: Beauty Concepts
Keeping markets under close watch, IADS collected noteworthy beauty concepts from retailers around the world.
Check out how retailers are drawing customers into physical stores through new enticing design concepts, innovative experiences, expanded product offer, technology and fun.
Clinique Laboratories, China
The new retail concept from the skincare brand aims to personalize each customer visit. Customers have their skin analyzed before they enter the store thanks to a diagnosis made through a facial scanning system. The rest of the store experience is then determined by the result of the diagnosis: presentation of specific products and services, close to consulting, that will be unique for each customer.
MORE ON Clinique Laboratories, China
B+ Tube, Changsha
The shopping experience, organized throughout the 218 sqm store, allows teens to create social media as they shop, something which helps facilitate online to offline consumption. Sections are organized around the three basics of cosmetics: cleansing, foundation, and make-up. Each area hosts an education centre for customers to learn and experiment with the products through tutorials and videos.
Glossier, UK
Glossier, a ‘community-driven beauty discovery hub’, opened its first permanent location outside of the US. The design is playfully balanced between old and other modern materials and finishes, like perforated paneling and sculptural marble in Glossier’s identifiable millennial-pink hue. The heart of the store is the product testing area. Mirrors are inscribed with ‘You Look Good’ – Glossier’s confidence-boosting catchphrase. Meanwhile, a ‘Wet Bar’ encourages sampling of skincare and makeup.
H Beauty, UK
H Beauty stores by Harrods has price points suiting a vast array of consumers. “Magic Mirrors” leveraging augmented reality technology permit customers to virtually try on products and have images of their experimentation sent directly to their phones. Dedicated spaces labelled “Play” allow customers to have fun with hairstyling, product demos and makeup consultations.
Harmay, China
Once an online retailer, Harmay stores shake up the high-end cosmetics segment. Targeting savvy young consumers and fast developing in Chinese first-tier cities, Harmay has a solid reputation as an influential incubator of consumer trends. Harmay gained a reputation for creating design-led retail spaces, aiming to boost the shopping experience. The displays encourage self-serving shopping which captures the mindset of shoppers.
Joyce Beauty, Shanghai
Joyce Beauty at Lane Crawford, offering a serene refuge from the department store hustle and bustle, is dedicated exclusively to niche high-end cosmetics and fragrances. These brands (Dr. Barbara Sturm, Perricone MD, Augustinus Bader, RéVive, Floraïku and 111SKIN among others) show the growing appeal for prestige beauty.
more on JOYCE BEAUTY, Shanghai
MDC Next Door, Berlin
MDC cosmetics is pushing the beauty limits by offering luxury cosmetics, fine objects, small furnishings, ceramics, and jewelry. MDC cosmetic is a curated specialist shop for cosmetics and cosmetic treatments. You can find brands including Aesop, Image skincare, Susanne Kaufmann, malin+goetz, Santa Maria Novella, Frederic Malle, Escentric molecules, Emma S and many more.
Retterspitz, Nuremberg
One of Germany’s oldest pharmacy brands, offering a wide range of cosmetics and medical cosmetics that combine traditional healing expertise with modern standards and the latest scientific research. Retterspitz offers an immersive brand experience and personal customer service, while serving as a marketing tool to discover clientele’s preferences and shopping patterns.
MORE ON RETTERSPITZ , Nuremberg
The New Sanctuaries, Mexico City
Founded by Mexican designer, pharmacist and alchemist Tatiana Torrealba, The New Sanctuaries provides clean cosmetics for skin care, products that have a high energy frequency and coexist in harmony with nature. The brand is taking information from ancestral knowledge, clean beauty principles, transparency, nature and technology.
MORE ON THE NEW SANCTUARIES, MEXICO CITY
IADS Exclusive - Product passports: bringing transparency to retail
IADS Exclusive - Product passports: bringing transparency to retail
Introduction
In December 2021, the European Union announced plans to use digital product passports to boost the circular economy and to gain a better view on the full lifecycle of various products, including textiles. The overall goal would be to prevent these items from ending up in landfills and to keep them in circulation, either as broken down raw materials to be reused or to be repurposed. Nowadays, it is expected that products should last longer, be repairable, and be recyclable. The major problem is that the information revolving around product components and recyclability is easily lost, but the EU believes that these digital product IDs can be the change that industries need to better promote circularity.
Digital product passports: what is it and what for?
Digital product passports (DPPs) provide a way to digitally capture key information about an item and create a centralised bank where this information can be stored. Basically, it is a virtual tag that captures all information surrounding the product to bring transparency about materials used and overall impact to customers and manufacturers. According to Business of Fashion’s The State of Fashion 2022 report, product passports can be used to boost authentication, transparency, and sustainability by acting as a method to store and share information easily so that either customers or businesses interacting with the product can understand how it was made and what it is made of. According to the report, this technology should not be overlooked because approximately 2 out of 5 fashion executives plan to adopt product passports in 2022 or have already done so.
Communication stemming from these product passports will need to be two fold: addressing customer-facing needs and informing recycling or repair entities with technical information about the item's components or how to extend its life. Digital product passports tackle a few key issues around product information:
- Increased transparency: easily accessible product material information will facilitate the proper recycling and reparation of items.
- Improved life cycle sustainability: availability of detailed supply chain information from material grade, carbon footprint, repair instructions and components.
- Centralised bank of information: provides all necessary information needed by stakeholders such as governments, manufacturers, customers, and for those involved with the second-life of the product.
How can product passports be helpful to retailers?
As seen with NFTs and RFID, technology that enables brands to add a unique identity to each product is increasing in value and importance. These identification technologies are unlocking a lot of potential business cases that retail players find worth investing in. Interestingly, retailers that have already invested in RFID (radio-frequency identification), blockchain technology like NFTs (Non-fungible tokens), QR codes, and NFC (near-field communication can extend their use with product passports. Already this technology has allowed businesses to get a handle on counterfeiting as well as create better transparency across the supply chain, which addressed two major pain points for retailers.
Product passports can also extend the relationship between retailers and their products. Retailers are at a time where they are saying goodbye to the short-lived relationship between brands and products where brands and customers part ways completely following a sale. Customer-brand relationships have advanced, and harnessing the power of product passports gives brands the ability to continuously identify and monetize apparel products through circular business models such as rental, repair, resale, and recycle. This extension of their product’s life not only increases their potential for margins, but also unlocks access to new types of customers, such as Gen Z, who value affordable and sustainable products.
Examples of notable players powering product passports
A major player that is helping power connected products across fashion, apparel, and retail is Eon Group with their Internet of Things (IoT) platform which brings together partners to gather and share data. CircularIDs allow brands to have instant access to connected product data that is crucial for recycling and re-commerce. A mobile app allows users to scan products using RFID, NFC, or QR codes to access details ranging from the original sales price to the material content, with the ability to capture the resale channel as well. This database of information opens garments up to become more circular overall.
Eon Group’s service also increases the amount of communication surrounding garments between brands and consumers. Once a connected product is scanned, customers can access styling tips, instructions for resale, sustainability credentials, services for rental, among other things. The group has basically created a common language and formats for brands to communicate across the lifecycle of fashion products. Eon has already partnered with retail players such as the Yoox Net-A-Porter Group, H&M, and Pangaia
There have been additional efforts in connectivity for the retail industry. In 2020, Avery Dennison partnered with Certilogo, a digital authentication platform, to integrate the solution with Avery Dennison’s apparel labelling products so customers can verify product authenticity via their smartphones through a series of questions. Also, start-up Wiliot offers bluetooth-enabled microchips the size of a stamp that have the ability to sense, compute and communicate. These chips have the ability to report every condition and interaction they face to the cloud in real-time, and are even self-powered using radio frequency!
The limits: standardisation needs to be achieved, one way or another
Although technology is catching up, creating product passports for every item will not be an easy task, especially as supply chains are already an area needing great improvement. Even though information will be easier to capture at each stage of the process, there still seems to be some questions around the overall accuracy of this data. But as product passports can be connected through blockchain technology, there is an additional layer of trust and security that can be achieved. Unfortunately, even blockchain technologies are still in the process of defining governance and standardisation, putting this kind of technology at the cusp of its potential.
But, in order to have a standardised system, businesses and governments will need to come together to agree upon common standards to be able to scale such a project. New data standards, technological innovations, and supportive policies may be able to bring definition to the global waste crisis, putting fashion players under the microscope. With the continued progress and adoption of solutions such as what Eon Group is offering, the future of fully connected products is not so far out of sight.
What’s in it: circularity!
In the past decade, items that are being sold have not been created with the intent of being durable, repaired, or recycled. This is a major problem as consumers become more conscious about their buying habits, but unfortunately, circular products are not always easy to find. There have even been some activists that want to push the European Union to impose a mandatory European standard for durability and repairability among sold items to ensure that sustainable products are the norm. Although such strict regulation has not proven to be easily enforced, such implications could seriously impact the fashion industry if imposed. Therefore, eco-conscious retailers that want to be ahead of the game should understand how digitalising information through product passports could be a tool for implementing and scaling the circular economy.
The fashion industry is a key piece in the achievement of the circular economy, but without transparency, standardisation, and data sharing, overall progress will be stalled. Digital product passports that can be the holder of all information pertaining to the creation and vitality of goods could unlock a more sustainable economy for all.
Credits: IADS (Mary Jane Shea)
IADS Exclusive - Brand Roundup: Home and Decor
IADS Exclusive - Brand Roundup: Home and Decor
IADS recently held a meeting about on the home and decor sector. Based on market research, the IADS team and NellyRodi presented the most innovative brands from different segments of home and decor: furniture, home appliances, home accessories and electronics. Check out a selection of these brands!
Furniture

Vetsak
Produced locally and sustainably with an innovative design from South Africa. One-of-a-kind, modular, quality, practical furniture, that brings life a little extra comfort.
Check out the Vetsak website here

Lapalma
Balancing craftsmanship, industrial techniques, efficient production, and a focus on details, Lapalma produces and sells its quality design aimed at creating innovative solutions that interact with each other. Lounge, Light Office, Outdoor, Cafè and Home, all customised environments, by extending the range of finishes.
Check out the Lapalma website here
Home Accessories

Ago
Korean design studio specialized in lighting, that searches for a balance between beauty & function with light. With the line between residential and commercial space becoming increasingly blurred, Ago values simple, honest and refined aesthetics.
Check out the AGO website here

Helle Mardahl
Helle Mardahl is an artist and designer with an eccentric and contemporary aesthetic. Playing with forms and materials, she playfully combines strength and fragility, crafting pieces that bring life to spaces. Creating a dreamy universe of richly coloured quirky glass designs.
Check out the Helle mardahl website here

Cookut
Cookut is a brand of kitchen utensils, which also offers accessories for storing and transporting food, as well as hygiene and care products. Their goal is to reduce plastic and daily waste, reduce CO2 emissions while using natural raw materials, promote eco-design and produce responsibly and transparently.
Check out the Cookut website here

The Citizenry
Citizenry believes homes deserve designs with a soul, a story, and a purpose. Country by country, they partner with master artisans, blending modern style with different cultural time-tested techniques. The products reflect a collective of individuals from different cultures and backgrounds who rally together to create something beautiful.
Check out the Citizenry website here

Boy Smells
Highly spirited scented candles, fine fragrance, and intimate wear for all or neither gender. Boy Smells wrap traditionally masculine scents in a prettier bouquet, made with natural oils, all-natural coconut wax, and beeswax blend and are hand-poured in a reusable glass vessel and hand-labeled.
Check out the Boy Smells website here

KJP
Colourful homewares, cheerful print & pattern-focused textiles and lifestyle goods that spark joy.
Check out the KJP website here

Lucas du Tertre
Creating a bridge between India and France and between tradition and modernity. Colourful and printed collections created in the Parisian workshops and printed or woven in India according to ancestral know-how.
Check out the Lucas du Tertre website here

Dusen Dusen
Bold, original prints on versatile, textile and home goods products that includes bedding, throws, pillows, and towels.
Check out the Dusen Dusen website here
Electronics

Mirror
A mirror that is also the ultimate home gym with the most workout variety that actually looks good in your home. 10,000+ classes on demand, 50+ genres, and new live classes daily.
Check out the Mirror website here

Yoto
Carefully connected speakers that puts kids in control of their listening, learning and play. Packed with features for day and night and without any cameras, microphones, or ads.
Check out the Yoto website here

Gomi
Wireless mag chargers, portable chargers and speakers, made out of non-recyclable plastic bags, and powered by 100% repurposed e-bike batteries.
Check out the Gomi Website here
Home Appliances

Netatmo
Aesthetic smart home devices with a variety of products including various security cameras, personal weather sensors, and an internet-connected smoke detector.
Check out the Netatmo website here

Daan Tech
Customisable dish washer with 24 colors to choose from that washes daily dishes for one or two people in just 20 minutes. Bob the dishwasher is the world’s most advanced autonomous and eco-friendly dishwasher thanks to its integrated water tank.
Check out the Daan tech website here

Lema
Lema Air Cleaning System uses nanotechnology and a special UV lamp to generate a photochemical reaction within the wardrobe that naturally destroys viruses, bacteria, odours and mould, improving the customers’ well-being, reducing allergies and respiratory problems. The wardrobe is entirely sanitised, including internally and at the back, without air resistance.
Check out the Lema website here

Somnox
Somnox Sleep Robot is a soft-robotic that enhances the quality of sleep and uses breathing regulation and audio to help fall asleep faster, get deeper sleep, and wake up at the optimal time through a smart alarm.
Check out the Somnox website here
IADS Exclusive: 2021 IADS Academy - Omni-cluster for omnichannel
IADS Exclusive: 2021 IADS Academy - Omni-cluster for omnichannel
In early 2021, the IADS Academy participants were set the task by their CEOs of suggesting ways to develop a truly omnichannel P&L and related KPIs relevant to department stores. Their proposals covered several areas including KPIs and data sharing (see Presentation to CEOs at IADS General Assembly, 28 October 2021; and IADS Academy 2021 report). One of the proposals called for the development of “omni-clusters” of customers. The IADS has attempted to develop this idea.
Imitate or innovate?
In the early days, many omnichannel department stores in effect created a separate and competing business within their companies: e-commerce, which started as an “add-on”, often an experiment, was operated on the same principles as the traditional stores, with the differences that selling took place on a website rather than in physical stores, and that customers were delivered at home instead of carrying their purchases away with them.
As e-commerce began to include more merchandise categories, department stores saw the format as competition, just as they had seen big-box and discount retailers, then fast-fashion companies enter their market and address their customers. It was supposed that by getting involved in e-commerce, the danger could be fended off and those customers tempted by pure online retailers could be brought back to the fold. However, online retail proved to be bigger than expected, customers integrated it quickly into their retail habits and department stores found themselves running to keep up with the trend. Today, it is more of a scramble to adapt to the pandemic new normal. The puzzle of profitability of e-commerce was not solved, even by the pure players.
Integration into the traditional business has been unfortunately very expensive. The original business was not adapted and e-commerce was generally loss-making. Department store companies have had to operate simultaneously two business models: one in which the main cost centres have been real estate and people, as well as the new one requiring significant investment in systems, fulfilment and marketing. In spite of efforts to the contrary, the traditional department stores found themselves competing not only against new online companies but also being cannibalised by their own creation, at first a modest separate pilot but which soon grew into a Frankenstein monster. The admittedly complex model of the traditional department store was clearly inadequate for the job of operating online, and a fortiori inappropriate for an omnichannel retail operation. One consequence is that, under pressure from activist shareholder groups, some US companies have already or are considering spinning off the high growth dot.com part of the business to increase market valuation such as Saks Fifth Avenue and Hudson’s Bay, and also illustrated by the speculations on Macy’s, even if this approach sparks controversies. This suggests that they believe there is no answer to the omnichannel conundrum.
Struggling with channel conflict
Part of the problem has been, of course a shift in customer behaviour and expectations. It is clear that any business model which does not start from the customer is doomed to failure in what has been called “the age of the customer” (from say 2010). Starting from the belief that online customers were different from store customers, department stores operated two separate channels and only slowly came to the realisation that there was such a thing as an “omnichannel customer” (with higher spending than the single channel customer they had been dealing with).
But then the challenge of merging two business models with very different cost structures became apparent. Against the traditional conversion ratios of 40% plus, the online part of the business was confronted with rates as low as 1%-2%; against sales per square metre, online invoked profit per transaction; against shareholder expectations of bottom-line profit, online was operating as a start-up expecting no profit for at least 5 years but demanding rapid growth during that time; against B2B logistics based on store deliveries, online required quick and efficient B2C fulfilment.
As long as the online part of the business represented 5% or less of the total, then it was monitored separately in order to determine its profitability, return on investment and its longer-term future. As time passed, it became clear not only that online was here to stay, but also that it was contributing to store-based business (and vice versa) in a complex and organic way making it almost impossible to isolate online P&L from store-based P&L. (See for example how Macy’s is claiming to “scale omnichannel thinking across the entire customer journey”.)
The question then becomes how to determine the profitability of various parts of the business, how to attribute costs and sales. Furthermore, it has become clear also that the “best” customers are “omnichannel” customers, making full use of all the opportunities available to them across channels to search, gather information, purchase, pay, get delivered and return merchandise. However, it remains unclear to what extent they are the most profitable, as they “consume” expensive services which are implemented through expensive platforms.
Omnichannel means integration
And yet… many department stores are locked into the double P&L model and struggling to determine how to attribute sales and costs. Partly because so many employees are assessed on a series of inappropriate KPIs which actually discourage an omnichannel approach. And partly because data is unavailable to track customers, inventory, fulfilment, returns etc. in sufficiently granular form to allow appropriate attributions.
Integration of channels means first and foremost the integration of data allowing all channels to be under the same control and distribution system. For example, all data on any particular customer must be available in one accessible place whether it concerns purchases or returns in all channels, preferences, hard data as well as unstructured data.
Similarly, inventory data should be updated in real time, any priorities for particular channels need to be clearly set out in order that channel conflict does not develop from limited inventory.
At the same time, traditional KPIs which have been focussed on transactional records are no longer able to evaluate the sometimes complex drivers of customer decisions. It has been suggested that omnichannel KPIs should fall into four main categories: awareness, engagement, conversion, and loyalty. Thus, such KPIs might cover traffic and visits, recommendations and conversion rates, cross-channel conversion and baskets, and advocacy, lifetime customer value, revisit rate and frequency, for example. (See KPI suggestions.)
A new idea: “omni-cluster”

Since the customer journey has become omnichannel, it has arguably become necessary to use management tools and financial statements which reflect this development rather than struggling to attribute revenues and costs to different channels. The notion of “omnicluster” is a proposal in this direction.
Clustering in itself is not a new idea for department stores. Different clusters as applied to department stores include clustering by store capacity (space for example); by attribute (traffic, location, income profiles…); by sales (revenue, inventory turn…); productivity (revenue or gross margin per square metre); price (price profile, elasticity); multi-dimensional clustering; and more.
In the same way, customer clustering is also common. Using algorithms and AI it is generally defined as an improvement on rule-based segmentation since it allows clustering over many more dimensions; allows only small variance within each group; and can be made dynamic and reflecting the current state of data.
The proposal made by the IADS Academy was to bring the two ideas together to create customer clusters who shopped at stores, online, or both. This would potentially avoid the difficulty of separate or overlapping P&Ls for stores and online. The only rule is that any customer can belong to only one omni-cluster even if they occasionally shop, return, or collect in several physical stores. All revenues, returns and costs associated with a customer would belong to that omni-cluster.
It has been often remarked that not only does online bring customers to stores (and vice versa), but most online customers are more dense around an existing store (while this was a surprising discovery in the early days of omnichannel, it is now fairly obvious since most customers now shop online and stores are situated in the most important markets). In this case, it is clear that an omni-cluster may consist of one or more stores and the online customers residing around that store. This is the simple omni-cluster model as favoured by Magasin du Nord for example.
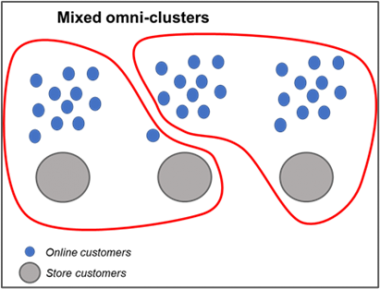
If, however, a number of online or omni customers have a preference for direct contact with a distant store (say a flagship store, or a store closer to their office rather than their residence), then one mixed omni-cluster might include a store, its geographically close online customers as well as online customers geographically closer to a different store. This may happen also if the stores are clustered by size as they are at Manor, for example.
If store customers are very mixed (tourists and locals, for example), then one can imagine an omni-cluster made up of local store customers plus online, and another partial omni-cluster made up of tourists and the much smaller online tourist customers. A business which involves franchised stores might include its own stores and all online customers in its omni-clusters but not include the franchised stores. These cases may be more appropriate at, say, Galeries Lafayette.

A series of ecosystems
As these examples show, the criteria for omni-cluster membership may obviously vary from one company to another according to its history, its organisation, its market etc. It is a flexible model. The definition criteria of omni-cluster will be a function of the particular circumstances of each company and its history as well as of the omnichannel strategy pursued by a company (aggressive online growth, new store openings or potential store closures etc.).
The aim is primarily to group revenues and costs into a number of omnichannel P&Ls which cover total operations of a cluster which can serve to manage operations (through the related KPIs), and which can be consolidated into a total business P&L. While the different omni-clusters can be compared, it is clear that none will be exactly comparable to any other. For example, geographical location or the number of stores in a cluster may have an impact on fulfilment costs.
However, the advantage of this model is that it highlights the profitability of the customers in any one cluster (for example how much they spend in all channels, frequency, rates of return, margin per customer etc.). Clearly the costs of store personnel also do not relate only to store customers, which distorts store-only P&Ls. Potentially it also allows the evaluation of the true loss of revenue through a store closure.
The kind of integration referred to above moves closer to an “ecosystem” perspective of the retail business. Indeed, a degree of “unbundling” will be necessary to evaluate the costs attributable to an omni-cluster. When that exercise is pursued, then it becomes possible to find potentially more appropriate, more efficient or more effective solutions before rebundling these into an omni-cluster ecosystem.
Warnings, dangers and the way forward
However, such a move would make it quasi-impossible to spin off the dot.com part of the business as has been done recently by HBC with Saks Fifth Avenue and Saks.com. There are currently some reports of Macy’s considering a similar move. It is clear, however, that these examples are financially motivated and a result of pressure from activist shareholders. They are also more appropriate to larger companies. A smaller omnichannel department store following the integrated omnichannel route will be capitalising on its unique status as what Bain has called a “regional gem”. Once established, an ecosystem can no longer be dismantled and split up into its original component parts. It competes as a whole, not as a multi-channel entity. However, this commitment is no more risky than the spin-off of the dot.com part of the business may turn out to be for larger companies which choose this way.
The omnichannel route might also imply considerable reorganisation of the traditional bricks and mortar assets as illustrated by the John Lewis case which is closing and shrinking so many of the stores it (perhaps unwisely) opened while it was expanding its online business (now around 60% of total revenue). It also sold its Ocado stake in 2010 for £250m which would be worth nearly £2bn today. Rather than spin off the online business, it is reshaping the total business under a new team, focusing on own brands, convenience, high productivity, sustainability, and the integration of formats.
John Lewis raises the question of how to implement the shift towards real omnichannel in today’s retail landscape. Clustering, new KPIs and rejigged P&Ls cannot be put in place in a day. The question therefore is: What would a transition phase towards omni-cluster P&L look like? Who should guide the transition, and how can investors be won over to support this longer-term shift?
Credits: IADS (Dr. Christopher Knee)
IADS Exclusive - Transformation in retail: Innovative Thinking Interview with Chafik Gasmi , Chafik Studio
IADS Exclusive - Transformation in retail: Innovative Thinking Interview with Chafik Gasmi , Chafik Studio
*2020-2021 has been more than a period of pandemic and crisis: by its magnitude and lack of precedence, it has literally changed the world, especially the retail world, by changing habits: digitalisation and new purchasing habits, work from home and the question of commuting, notion of essential vs. non-essential goods.
The IADS launched a series of interviews with innovative thinkers to understand their views on how to deal with such changes. All organisations have proved their resilience and ability to cope with the emergency of the situation, however, it is a very human thing to tend to come back to habits whenever possible. What happened? How can we make the most of what we learnt and how can we make sure our organisations and thinking processes are durably impacted?*
Introduction: Chafik Gasmi, founder of Chafik Studio
For this session, we welcomed Chafik Gasmi, based in Paris and founder of architectural company Chafik Studio.
Chafik Gasmi, 59, launched his first designer’s furniture line in 1990, just after graduating from the Ecole d’Achitecture de Paris. This line was awarded the Grand Prix at the Paris Salon du Meuble in 1992. Following this initial success, his projects were selected by the French State to furnish the Prime Minister offices.
In 1996, the founder of Sephora, Dominique Mandonnaud, asked Chafik Gasmi to design the Sephora flagship boutique in Champs Elysées, to help him bring his vision alive. This was Chafik Gasmi’s first venture in cosmetics, and ended up in a mix of architecture, design, cosmetics, with a true customer-oriented vision. Then, after LVMH acquired Sephora in 1997, Gasmi was appointed as the artistic director for Sephora and personal advisor of Mr Arnault for several brands on branding and retail experience, including Kenzo, Guerlain or Dior. After a stint as Artistic Director at Baccarat, he created Chafik Studio in 2004. In 2010, he initiated a long-term relationship with Lancôme as well as with Fendi Casa.
Nowadays, Chafik Studio is a multidisciplinary structure, with competencies ranging from architecture, interior design, product design, retail design and artistic direction. The company is involved in hotels, department stores, retail spaces, furniture and objects, and is able to work with both corporate companies and family businesses.
Part 1 – Dealing with innovation
*IADS - Chafik, your studio is renowned for its groundbreaking approach, yet always keeping in mind the needs of customers, which explains why you have developed so many retail concepts with the biggest brands. How do you foster this creativity on a daily basis?*
Chafik Gasmi - First of all, the most important, and this is common to both family businesses and corporate companies, I always deal with the person who ultimately pays for the project, not intermediaries, even if they hold top positions. Innovation is always very difficult and can generate anxiety. For me, it is easier to talk about changing rules with the guy who pays, rather than how to deal with the rules with the guy who executes.
When it comes to my method, I always look at things in a very fresh, almost childlike way. In other words, we force ourselves to be naïve, curious, and ask questions, to make sure we see things differently, challenge the status quo, and get excited in the way. The idea is not to be different for the sake of it, but to generate a tension based on trust, within a reassuring framework.
Innovation can generate anxiety and trust is key to taming the feeling of danger.
*IADS - How do you manage creativity within your organisation? How are ideas generated and with what process? Also, how do you onboard newcomers in your organisation and make sure they fit with your mindset?*
CG - First of all, I avoid creating a silo between my team and my customers. We design the brief together, because the answer is often in the question. If you do not take part in the question elaboration, you will miss something in the answer.
Then, once the brief is done, we do the first meeting with our clients in our studio. During this “project session”, we work together on rewording the brief and gathering the ideas. Everyone sketches their ideas, which at the end I personally synthesise. The goal is to reach a very strong, clear and simple idea, coming from a series of interactions between everyone, including words, sketches, feelings.
Once the idea is here and we are ready to launch the project, we gather all the people who will be involved at one stage or another (contractors, third parties, middle management…) in a room to explain the project. During that moment, we identify in advance all the blocking elements and kill negative thinking. It is all about resolving all opposition at the launch instead of fine-tuning along the development phase, to keep the project strong and fresh. Any other approach invariably ends in concessions and compromises, which always dilutes ideas.
Given the level of interaction with which we work, I must say that Covid-19 has been a difficult period as we lost a lot of the intuitions we usually get from interactions. Video conferencing helps in the thinking process, but not on the perception of feelings. This is why we took a step aside and seized the opportunity to think about our own processes, organisation… to be ready for better days in terms of operations. Covid-19 has been quite difficult for creativity itself I must admit.
Part 2– Retail
*IADS – Coming back on your statement that “answers are usually in the question”, what was the answer in the 1996 Sephora store question, and are these answers still valid for 2022? What would you change if you had to do this project again?*
CG- The challenge at the time was to create a brand, Sephora, where “everything about beauty could be found”. The founder wanted to mix the ease of use from supermarkets, and the feeling of luxury, without being gimmicky. The question was therefore to combine the best of both worlds. In addition, he wanted to create a fascinating and impactful space, like a Versailles-meets-Disneyland idea.
This combination of ideas was a fantastic vision! I related this project to the idea of a religious place, like a “temple of beauty”. I wanted to come back to fundamental symbols that are universally understood. In the end we came up with a black and white store, where you do not see furniture, only products and brands. The original building had some columns for structural reasons, and we created new fake ones to create a rhythm and give the feeling of a temple.
From the merchandising point of view, we created gondolas which allowed us to give visibility and perspective. There was no signage, the zoning was defined by colours and lighting, in a very organic manner.
Today, Sephora is a fantastic selling machine but the point of sales itself may have lost some of its soul. I feel that a part of the magic has been lost, even though the store is extremely efficient from a business perspective. Efficiency is needed but should be completed by an unexpected details, an intention, to really touch the customer. For instance, in the store, in 1996, we wrote poems on the columns that could be visible only if you were extremely close to them.
*IADS- You have collaborated with Lancôme for almost a decade now and accompanied them in the evolution of their retail concept. It is the same thing with Kenzo showroom. What where the key learnings for you when it comes to organising retail (or wholesale)?*
CG – I left Sephora and LVMH because I really wanted to do my job and be an architect. I designed hotels, museums… but I then realized how much I had learnt from retail. Nothing is more sophisticated than retail when it comes to building a space. When I built the Modern Art Museum in Algiers, I recalled my learnings from Sephora when considering the traffic flow within the building. It had truly been a virtuous circle.
When Lancôme reached out in 2012, I wanted to challenge them, and go beyond the architecture of their stores, to work on the architecture of the brand itself. Why? The store is the place where all aspects of the brand are conveyed, but in the case of Lancôme, the brand itself was fragmented and not fully coherent.
At the time, the brand was led by Sue Nabi and she was ready and able to change the rules, which is why she took the chance. Then the adventure continued with her successor Françoise Lehmann. For more than 10 years we were able to bring together the brand to another level. It was all about generating change by asking the right questions, pointing out the incoherences. It is not about doing the work of people, but helping them to grow.
Interestingly, what I realized is that when you are successful, you not only attract the attention of your clients, prospective ones, competitors, but also talents. These 10 years at Lancôme helped my agency to attract great individuals and allow us to grow, expand and look at new projects.
Part 3 - Department Stores
*IADS – You once mentioned that, for you, Department Stores are “decathletes”, do you want to explain your vision behind this phrase? What does a department store stand for you and to what extent do you consider it special (or not)?*
CG – Department stores were challenged twenty years ago by specialty chains such as Sephora, especially from the point of view of their location.
While specialty stores (and later, brands) have the possibility to choose their location, often going for the top ones, department stores have, by essence, to make arbitration and choices about the location they give to brands within their own spaces. Multiply this by the number of locations, possibilities and floors, and you have a handicap for department stores when it comes to the attractivity of their offer seen as a whole, compared to the easiness of access and appeal of specialty stores (not even talking about logistics, service or product range depth).
However, today, after the pandemic, now that digital is part of our lives, size matters. Convenience stores are being swamped by e-commerce. The only way to create a difference is to be big and to have many things, create excitement, events, make people feel they are part of a bigger community. The best in that race are obviously department stores!
However, they still have difficulties to behave as a unified place, rather than an addition of floors or a “vertical street”. The issue is not how to give the same feeling on each floor, but how to make sure that the idea behind the very concept of the department store is felt and palpable as one experience, at the entire building level. For instance, the concept of Galeries Lafayette at the beginning was to be an architectural destination, as the most beautiful place in the city, a monument. You started to shop after having seen the cupola at the Haussmann store. Because the department store was a monument, it became inevitable.
A department store is not a juxtaposition of clearly separated activities which is currently the case at La Samaritaine with a hotel clearly cut from the store itself. It should be a fusion, a mingling of activities under one name, one destination, one experience. For me, the future of department stores is the hotel activity. A hotel where you can shop whatever you want, whenever you want and however you want, is way more exciting than a store where you can stay.
*IADS – Who or what would you consider as exciting when it comes to retail?*
CG – In terms of brands, probably Apple, thanks to the level of service. But you do not sleep in an Apple store. I dream of a store that is accessible 24/7, where you can live. In other words, a hotel turned into a department store. It is all about living an experience, or renting a usage, rather than simply buying something. Alternatively, the metaverse opens unlimited possibilities in terms of architecture, usage, consumption, business…
*IADS – What is the future of retail?*
CG – Hotels!
Credits: IADS (Selvane Mohandas)
IADS Exclusive - Gen Z brands are putting department store models under pressure
IADS Exclusive - Gen Z brands are putting department store models under pressure
Gen Z customers, the new Holy Grail
Today, Gen Z favoured brands are highly addictive and successful due to their interesting offer, convenience, affordability, and seamlessness. But as these players focus in on finding a service that sets them apart, it makes it difficult for more traditional retail formats, like department stores, to stay relevant in the eyes of young shoppers. In fact, retailers can no longer only focus on an interesting offer, they must now offer perfect logistics, seem sustainable, and provide a unique experience. How should retailers respond to these incumbent brands as they change the DNA of the retail business? What exactly does it take to generate an interesting offer and experience for this next generation of shoppers?
A look into hot Gen Z brands: not everything is perfect, despite generational claims
It is important to have a look at three popular Gen Z brands and how they are appealing and winning over young shoppers. As sustainability has been noted as an important factor that impacts Gen Z’s decision making, it is worth noting that some brands are successful despite their level of sustainability. Taking into account how sustainable they are, we can label these brands as the good (Deciem), the bad (H&M), and the ugly (Shein).
The good: Deciem
First, it is worth looking at a popular retailer among Gen Z shoppers, the Canadian beauty brand, Deciem, which has gained a cult following on TikTok for their skincare line, The Ordinary. The reason that it has become such a hit is because it is affordable and offers tried and true ingredients. Deciem has taken the approach of taking basic ingredients and offering them at a fair price, in a space that is typically overpriced with mark-ups.
On top of their successful products, the skincare retailer has also challenged shopping trends that promote overconsumption, such as Black Friday. In 2020 they shut down their stores and websites during the entire Black Friday weekend. And in 2021 they allowed stores to remain open, but did not offer any products to be available to encourage connections over transactions. This year, they even offered a sales event online called “SLOWvember” for the entire month of November, rather than a flash sale, to allow customers the necessary time to think before they buy. This is exactly the rebel stance that Gen Z shoppers are looking for in a company.
The bad: H&M
Then we have H&M, a prime example of a fast-fashion player that is seriously playing to Gen Z’s accelerated sustainability awareness. Shockingly, H&M was named the most transparent brand in the 2020 Fashion Transparency Index, but how can this be? H&M’s business model is known to be the epitome of fast fashion, using materials that don’t last and that are not recyclable, thus contributing loads of textile waste to landfills each day. In this context, transparency simply means that H&M has disclosed credible and comparable data about their supply chains, business practices, and the impacts these practices have on their workers, communities, and the environment. However, being transparent does not make H&M sustainable in the least bit. They are still a fast fashion brand that is exploiting cheap labour leading to the fast turnover of merchandise with large profit margins.
Nevertheless, H&M has been making efforts to be more sustainable, or so it seems. As sustainability is trending among younger shoppers, H&M has made ‘circularity’ the centre of their recent ad campaign, introducing their new collection that is made with ‘cutting-edge recycled and recyclable materials.’ The retailer also set up a recycling program within its stores and launched a resale site. H&M claims that they hope to use only recycled and sustainably sourced materials by 2030, but they have a long road ahead. H&M’s production rate is only second to Zara’s, selling roughly three billion garments a year! H&M is a major GenZ retailer because they can check off the “sustainable” box while at the same time delivering affordable fashion trends to help young shoppers achieve their unique “look.”
The ugly: Shein
The global pandemic led to the emergence and acceleration of purely digital players such as the Chinese fast-fashion retailer, Shein. Shein has revolutionised the fast-fashion world. In fact, we are no longer speaking of fast fashion, but of ultra-fast fashion. It has changed the retail landscape by offering Gen-Z shoppers infinite amounts of items that are all exceedingly cheap and can be delivered within 6-8 working days. In order to satisfy young shoppers' desires to have a wide range of choices and to stay trendy, Shein launches 30,000 new products per week and knows how to identify market trends faster than any of its competitors. Shein has grown in success through social media accounts such as TikTok which encourages a constant stream of marketing efforts to be able to influence shoppers. In fact, Shein offers major discounts on the most sought-after pieces discovered through influencers. The Shein obsession is causing issues for other retailers, almost as Amazon has done, by offering a fully digital service, and providing very cheap fashion articles with super rapid fulfilment.
According to Benedict Evan’s end of year presentation, Shein is now the largest US fast-fashion retailer. Other retailers, not only fast-fashion brands, are unable to compete with such services while being able to conduct a profitable business. Shein is taking over Gen Z shoppers as they offer affordable trendy styles, advertise to them through everyday social apps, while offering speedy delivery. But with Shein, the sustainability piece is definitely missing.
What are the “dinosaurs” (department stores) doing on their side to attract Gen Z?
Department stores are not staying idle in front of this new competition. They are working on offering Gen Z a wider range of sustainable fashion brands that are affordable at the same time. Galeries Lafayette and Printemps have both taken a firm step forward in the sustainability space. Printemps has showcased a circular fashion floor, including a vintage department where customers can sell secondhand items in exchange for store credit. Galeries Lafayette unveiled an entire (RE)STORE floor with both responsible and affordable brands, exploring recycling and upcycling offers, mainly intended to appeal to all of Gen Z’s desires. The space also features a second-hand corner, as well as a vintage department where customers can resell items, showcasing the different facets of implementing sustainability.
Organising such floors and services brings in these young shoppers to explore an area that feels more familiar to them, versus the overwhelmingly pricey offerings on other floors. Gen Z is no stranger to thrifting their clothes and taking the time to dig out a treasure. As much as they like instant gratification, they are also willing to take the time to search for something unique. Thrifting is in fact an affordable and sustainable alternative to fast-fashion and fits the expectations of Gen Z’s price point very well. As trends have a tendency to go full circle, thrifting is an interesting way for Gen Z to obtain a new look, checking both boxes of affordable and sustainable. Creating dedicated spaces for young shoppers with curated products and services is the perfect way to appeal to the experiences that Gen Z shoppers value when visiting a store.
As Gen Z shoppers are interested in achieving certain luxury looks for a lower cost, another innovative concept is the upcoming launch of Nordstrom’s “See You Tomorrow” shop, a luxury brand resale service. Nordstrom’s approach will be novel in the fact that they will be using lightly used and returned inventory that can’t be sold as new any longer. The items will be cleaned and repaired if needed before being added to the new shop. This service is a natural fit for Nordstrom as they have a very relaxed return policy, therefore this new offer will allow the retailer to reduce their overstock as well as achieve better margins on unsold or returned items. It will also allow Nordstrom to attract a new type of customer, probably younger, as the price points will be more affordable for luxury goods. Similarly, we noticed the same trend at Tech for Retail with re-commerce solutions that can help retailers set up plug-and-play resale shops that will attract new shoppers while giving the retailer a piece of the second-hand margin and maintaining control of branding in the resale market.
An upgraded offer is not enough: to be competitive, department stores must re-engineer several fields of operations
For a more behind the scenes example that is virtuous, yet could entice Gen Z’s luxury appeal at the same time, Farfetch recently launched a pre-order service that partners with brands to allow customers to order looks four weeks in advance which will then be produced based on the number of orders. This initiative will reduce the amount of inventory and waste created by the industry by cutting out any excess products, which is appealing to retailers as the management of inventory is streamlined and brands can get insights on which products might be the best sellers to prepare for re-orders sooner than usual.
Let’s not forget that all these examples are only possible if you have a great supply chain. If retailers want to compete with ‘the ugly’ players such as Shein or Amazon, they will need to be able to have complete control of their logistics arm. El Corte Inglés understood this threat and has already diversified their business through the creation of a logistics subsidiary that will compete against DHL and FedEx and allows them complete autonomy in this area and will be one of the major axes of growth for the retailer in the coming years. Young shoppers want to be served quickly with free delivery and returns as a prerequisite. In order to compete nowadays, the logistics side of the business needs to be efficient.
In order to stay relevant with Gen Z shoppers, department stores need to learn from Gen Z favoured brands such as Deciem, H&M, and Shein as they each give something more than just an interesting offer. Essentially, department stores will need to rethink their working model with add ons such as seamless logistics, a focus on incorporating sustainability at the core of the business through offers such as resale, and creating a space for young shoppers to feel ‘at home’, curated specifically to their wants and needs.
These operational add ons that work behind the scenes will create the environment and experience that Gen Z shoppers demand. Without such changes, department stores will be easily left in the dust by young consumers, especially as new and trending brands start to offer and specialise these kinds of services and experiences. It is important for retailers to understand that there will be a necessary evolution to the basics of the business if there will be any hope of keeping fickle Gen Z shoppers interested in their brand and products.
It is clear that department stores are having to tackle trends that Gen Z players have imposed. Gen Z themselves are having to find a balance between affordability and sustainability while trying to obtain luxury items to achieve a certain look. In order to offer such a balance, retailers will need to think outside the box for new initiatives that could potentially lead to new margin opportunities, attracting different and new types of customers, while fighting against industry issues such as overconsumption at the same time.
Credits: IADS (Mary Jane Shea)
IADS Exclusive - New York retail scene: it’s all about experience
IADS Exclusive - New York retail scene: it’s all about experience
At a time when travel is continuously restricted for many of our members, the reopening of the US borders before Christmas, as well as the NRF event in January, to which the IADS attended, felt like the perfect occasion to prepare a special retail review to give you a glimpse of what’s happening in New York retail, including comments and pictures for your review.
Are brands still innovating in New York, the city once seen as the retail mecca? What are the most interesting stores to visit? While Covid has had a major effect on retail everywhere, what are the impacts of the pandemic in New York?
Great and immersive experiences
Fashion and beauty
Gucci in Soho, is an immersive and impressive store that comes off as ultra-luxe and ultra-cool at the same time. On the second-hand side of luxury, TheRealReal Soho store is also impressive, thanks to staff competence, product curation, and a feeling of being in a “real” luxury multi-brand store with perfect presentation. It seems the concept is a success as it was one of the most crowded locations, with people buying and not just browsing. Interestingly, the store staff focuses on inviting customers to sell their belongings more so than to return for another purchase. LVMH recently invested in Aimé Leon Dore, the new cool kids brand. The store, perfectly located in Nolita, includes a café and a terrace outside. The store is usually crowded, giving off a great impression, and looks like a mix between Ralph Lauren and rap lifestyle. On the beauty side, Ulta in the Upper East Side feels very bright compared to Sephora thanks to the all-white atmosphere. More importantly, the perception is more immersive than Sephora, as Ulta provides a full beauty appliances section and a beauty salon.
Sports goods
Nike stores are all about experience. Nike studio was closed however, both Nike midtown House of Innovation and Flatiron locations were extremely crowded with waiting lines filled with local shoppers willing to buy full price goods. Overall, the staff was welcoming, polite and competent. At the REI store in Soho, although the impression is quite messy due to click & collect, the immersion feeling is very strong.
Tech and home goods
The Google store in Chelsea is also immersive and almost better than Apple in terms of experience and comfort. The organisation of their cabins to experience products is effective. Bed Bath & Beyond offers another kind of immersion, with a great revamping in the home goods area, including large and clear sections and alleys, easy circulation, a huge space allocated to cash registers and click & collect areas. It is great but one can wonder if the trimming process was a bit too radical as it seems there was less inventory and choice than before.
Kids
Camp store near Union Square is impressive with a playground located in a hidden location behind the counter. This store is also an inspiration in terms of VM in the kids’ sections. The “kid’s shopping” initiative where kids are given fictitious money to make purchases (with a set limit by parents, charged at the end) is very intelligent.
Other concepts
Because of its size, Neighborhood Goods in Chelsea is more of a concept store than a “department store”. The curation of local brands and price point is very effective, attracting the right customers and a nice coffee shop completes the offer. Shopify store in Soho is an interesting marketing space for the brand. The welcome and service are great however, retail is a real job: which includes maintaining stores in perfect condition, and this is not Shopify’s top competence.
Retail disappointments
Fashion
Kith store in Nolita is well merchandised and even though visitors were buying high price tags, the women’s selection is quite disappointing and overall the store is not impressive. In Soho, Galeria Melissa‘s immersive environment and window set up are impressive but the store was either closed or empty, with sales associates looking at her phones and standing in the middle of the entrance… The Webster was impossible to visit as it was partially closed most of the time. The surroundings look terrible and the building itself is under renovation.
Sports goods
On Running store in Nolita is attempting artificial “coolness” by asking customers to line up and wait for the next available sales associate… who are just chatting together in the back of the store. Once in the store, there are good display ideas (shoe storage drawers) and the number of people on the street wearing On Running shoes was quite impressive. Although greeted with a warm good welcome at the Allbirds store in Nolita, there was no real follow up once inside. Customer education on sustainability was visible, although nothing compared to what Green Pea in Torino does for instance.
Tech
B8ta “Retail as a service” store in Hudson Yards is a showroom demonstrating and selling tech and lifestyle brands. It may have an interesting business model and help people find novel items however, people in the store are more looking than buying, which questions the efficiency of such a concept./nbsp]
Another concept
Even with an interesting brand curation, Showfields was an odd experience. The store does not really reflect the missions the concept intends to represent (vegan, sustainable, women-led…), the sales associates were too pushy, the store was empty, the Magic Wand feature did not work and overall, the store lacks cleanliness.
What about department stores?
New Nordstrom Men’s and Women’s stores near Columbus Circle were by far the most impressive out of all of the visits. Their flexible format and fixtures allow them to change layouts throughout floors without taking a toll on brands’ presentation and desirability (though, sometimes a bit odd with luxury brands). During Christmas, there was a great gifting assortment and wrapping services. Overall, the product presentation was good during sales. In the Men’s store, the “floating” cash registers (right in the middle and designed more as stations, not booths) are interesting, as well as the way click /amp] collect is nicely displayed and even used as a feature visible from the outside. In the Women’s store, the ground floor is energetic, airy, and combines a great cosmetic section with the feeling of a concept store. The ground floor area dedicated to home products offers great product curation, which contributes to the concept store impression.
Nordstrom Local is conveniently located, well attended and had many customers at the time of the visit. The way the services are displayed and visible (as proof of competence) is interesting. The store also sells a very limited number of items (snacks, small items & accessories) though not enough to sustain the store itself. The staff was great and competent.
Saks Fifth Avenue’s ground floor is great and impressive, with the escalators going down to the fine jewellery section and overall, spacious, modern and bright. The rather simple idea of colourful escalator “wrapping” really inspires customers to visit the upper floors. Traffic was slow and SaksWorks on the last floor was closed. The Barney’s floor is a gimmick with no added value.
As usual, Bergdorf Goodman had great Christmas windows and displays, but the impression was not so positive. During Christmas they offered “presales”: customers were charged at the time and were to receive the product at a discounted price later. The 7th floor which used to feature stationery is now dedicated to BG merchandised products. The traffic is low, apart from the shoe floor.
Bloomingdales in the Upper East Side feels a bit old. Still, the store offered a gift-wrapping service with customised-printed gifting paper in partnership with Klarna. The new Men’s shoe floor is not revolutionary but nice, with brand corners and multi-brand areas organised by style/functions (sport and sneakers, casual and weekend, classic and work shoes). Service counters are emphasized.
Macy’s in Herald Square feels old and not well maintained (floor maps are not all correct), however it was overall busy. The home floor has been redesigned with a lifestyle approach. On the ground floor, there is an interesting mix of cosmetics, tech (including Apple) and light travel goods.
Is New York still worth a retail trip? While there are always interesting stores to visit, the city didn’t feel the same as before due to the lack of traffic and energy, even if it was a bit busier during the holidays. The impact of Covid on retail was felt in all areas. It was particularly visible on Broadway around Macy’s, with closed flagships (Victoria’s Secret and empty >500 sqm locations) and even more so in Soho, in the Mercer St. / Greene St. area where there are many “available” retail locations advertised. The slow traffic is both due to the heavy travel restrictions and to the local affluent consumers relocating in their secondary residences. For instance, it led Bergdorf Goodman to achieve a fair share of business by sending trucks every day with goods to the Hamptons and other locations in 2021.
Another common feeling from two separate visits was the impact of staff shortage (Macy’s advertises for recruitment on zones and screens normally dedicated to products) leading to a feeling of poor maintenance (Visual Merchandising, product visibility, overall maintenance and attention to details, even cleanliness) and poor customer service (among department stores only Nordstrom sales staff gave a sense of welcome and product-related competence). During Christmas week, there was a striking contrast between stores that were either fully closed (Mejuri in Nolita, Melissa Galeria in Soho), partially closed (The Webster, On Running) and the ones that were inaccessible due to long queues at the entrance (Louis Vuitton, Prada, Chanel, Nike…).
Credits: IADS (Christine Montard)
IADS Exclusive - Business case #9: Cidade Matarazzo, an example for the retail of the future?
IADS Exclusive - Business case #9: Cidade Matarazzo, an example for the retail of the future?
Retailers always try to keep customers captivated in their stores as the more often they come, the more they spend. A few years ago, carrying a relevant product offer displayed in a nice environment and sold by sales associates was enough to guaranty a healthy business. But through the years, consumers have begun to expect more from retailers than just shopping, including what has been on every retailer’s lips for a while: experience, entertainment and a sense of community.
At the same time, consumers have been travelling more and more and retailers have started to eye the tourism industry. To enjoy their slice of the cake, they started to open hotels, restaurants and all kinds of entertaining features such as a ski slope in the Mall of the Emirates, or closer to the IADS members, a cinema in Selfridges or an ice-skating rink on the Galeries Lafayette flagship’s rooftop: all initiatives designed to increase the number of touchpoints with customers, expand retailer’s influence, and ultimately “sell memories before products”.
The Cidade Matarazzo project in Sao Paulo is a great example of ‘expanded’ retail, illustrating a possible vision of the retail of the future. Scaling at a never-seen-before level in Brazil, it can be considered as the ultimate mixed-use retail project mixing hospitality, culture and entertainment with retail. But how does it compare to other retail experiments? What is interesting considering the future of retail, and what can we expect and learn from the project?
What is Cidade Matarazzo?
Initiated in 2009 and led by French businessman Alexandre Allard, Cidade Matarazzo will be completed in 2023. Versatile and entrepreneur, Allard successively founded several companies in marketing such as Diacom, which developed infomercials in France for the first time in the nineties. From 1994, he also ventured into the tech business with Consodata, once a leader in the consumer data business. Then he entered the real-estate business with successful and failed attempts in historic building refurbishments such as the Qianmen area in Beijing or the Royal Monceau hotel in Paris.
Cidade Matarazzo, located on the famous Paulista Avenue, is a mixed-use project, a city-within-the-city, both in size (the estate initially accounts for 50,000 sq. m/540,000 sq. ft), a EUR 500 million investment from Allard himself, with 27,000 people involved) and in its ambitious programme willing to herald what a ‘smart city’ should be in the future. The project will include:
- Retail: a 28,0000 sq. m/300,000 sq. ft retail village representing more than a half of the project and coming with 1,500 parking lots, gathering 300 brands, 30 restaurants and 60 small shops highlighting local craftsmen. The brand portfolio is unknown yet and, so far, there are no department stores involved in the project.
- Hospitality: a 25-storey tower by French architect Jean Nouvel and designer Philippe Starck will host the first 6-star palace hotel in Brazil which will be run by Rosewood Hotels & Resorts (which operates Crillon hotel in Paris, Carlyle in NYC to name a few). The 150-room hotel, opening late December 2021, offers the usual luxury options with 6 bars and restaurants, a wellness centre, a swimming pool and various event centres. Hong Kongese company Chow Tai Fook, both global biggest jeweller and owner of Rosewood group, owns 49% of Cidade Matarazzo.
- Art: with galleries and an exhibition centre whose inaugural show will be from British-Indian artist Anish Kapoor. There will also be a piece of art by Belgian artist Arne Quinze, “Tupi”, which is advertised as the biggest piece of art in the world. A permanent collection of art with over 450 works by 57 contemporary Brazilian artists will be displayed throughout the hotel property.
- Culture: a cultural centre imagined by French architect Rudy Ricciotti will offer a theatre, a music studio and a cinema.
- Nature: 10,000 trees will be planted in the 45,000 sq.m/48,000 sq. ft park surrounding the project.
- Sustainability: several urban farms are set to become the first national organic market. Also, the project relies on the extensive use of local raw materials.
- Social responsibility: the farms will be run by 4,000 homeless people trained to deal with planting, harvesting and logistics. The project features will also enhance and rely on local craftsmanship and will highlight the work of craftsmen thanks to the 60 small stores from the retail village (see above).
- Local heritage: both part of the estate, an old maternity hospital and an old chapel will be restored to host hotel suites.
- Logistics: an automated platform will guaranty ultra-fast deliveries across the city (although the delivery lead time is not known yet).
- Housing: 122 apartments ranging from 100 to 600 sqm.
- 4,000 sq. m/43,000 sq. ft of office spaces.
In terms of retail, the renderings look luxurious and attractive for sure. And needless to say, customer experience is supposed to be at its peak and will be enhanced by a massive digitalization through artificial intelligence: in order to tailor their journey, an app following customer’s steps will guide them according to their personality, interests, particular taste… and will collect data (as we know Allard is no stranger to data, see above). Also, Farfetch has been appointed by Cidade Matarazzo to implement its Connected Retail solution “to create a technologically advanced luxury experience across the retail village”. Digitalisation seems obvious as “the country has the highest percentage of Facebook and Instagram users in the world. Yet Brazil is only the 35th e-commerce economy in the world.”
The project seems to be able to cater both to locals (to wealthy customers but also to the emerging Brazilian middle-class) and tourists as it is offering all features one can expect from a ‘smart city’. Cidade Matarazzo could also serve the local communities by creating countless jobs. But, even though the digital aspect is quite developed here, this is not the first time such a project is launched. How does it compare with other ‘expanded’ mixed-use retail initiatives?
Hudson Yards: beyond the wow factor
Some have tried ‘expanded retail’ projects before, with questionable success. In NYC, Hudson Yards was also aiming to create a city-within-the-city, only bigger and appealing to the 0.1% richer people thanks to its luxury apartments offer. Accounting for a total of 1.7 million sq. m/18 million sq. ft of urban land, commercial, office and residential space, the project was supposed to be able to change (or at least heavily impact) the retail, entertainment, working and housing NYC landscape.
Representing more than half of the commercial surface, the so-called ‘mall-as-public space’ is gathering 100 stores and 25 food offerings on its 67,000 sq. m/720,000 sq. ft surface, and was originally meant to attract both locals and tourists with a dozen public art installations, a performance space and concert venue ‘The Shed’, the beehive-shaped ‘Vessel’, ‘The Edge’ observation deck, a luxury hotel, 4,000 rental units (including 10% of social housing) and offices to host nearly 56,000 workers. The property management was expecting that 40% of the traffic would come from tourists, 30% from office workers and the rest from city dwellers and the 10,000 people expected to live there.
Almost 3 years after its opening, Hudson Yards tremendously suffered from Covid with almost 2 years without tourists and the closure of its crown jewel, the Neiman Marcus department store. But even before Covid, the project purpose was questioned as it was failing to build a sense of community, with a mall feeling like any other mall in the world. Besides, the place is hard to reach as it’s only served by one unreliable subway line.
Hudson Yards greatly suffers from its gigantism and, compared to Cidade Matarazzo, it lacks human scale. Also, there is pretty much nothing happening at the street level, which remains an important key factor in retail performance, and urban and daily life appeal. Cidade Matarazzo seems to avoid such death traps.
Smaller projects with a purpose, bigger effects?
CSR is now a topic in itself, big enough to become the purpose of a project. The new Ikea store in Copenhagen city centre will be completed in 2023 and will serve two ambitions: helping the company become a circular business by 2030, and coming closer to customers living inside of the city centres. The project will offer an Ikea store with a café and a restaurant, but also a public rooftop park with 250 trees, 1,450 sq. m of solar panels, and 760 bike parking lots (knowing that half of the Copenhageners bike to work and only one third has access to a car). Here, Ikea is aiming to become a place to meet and not only a place to shop, by offering a “completely new experience for the Copenhageners”. While most of them will have to shop at Ikea at some point, the project is credible to both answer this need and be an anchor to the local community.
Cidade Matarazzo is set to highlight and serve local communities as they represent a significant part of the project. When it comes to its shopping attraction, the retail village offers a new place in Sao Paulo for more luxury and Western brands: this could be a key factor to appeal to the old rich elite but also to the emerging Brazilian upper/middle-class.
Another initiative, the recently opened Green Pea retail project in Torino in Italy is the first self-proclaimed 100% sustainable department store in the world. It tries to bring an answer to the following question: how to build a profitable business that takes for granted the sustainable approach? The building is 100% made in recycled materials, it uses the energy generated by the footfall itself to produce electricity, and heat pumps provide 88% of the heating needs. All brands sold in Green Pea are sustainable and a museum is here to educate customers about the need to care for the planet. While the project is solid, will its purpose be enough to create a fruitful business and recuring customers besides a single visit?
Cidade Matarazzo claim is not about sustainability but the project includes features relating to the topic, with tree planting and urban organic farms. While the project’s carbon footprint and environmental impact are unknown, the diversity and value of the activities offered should be enough to attract recurring customers looking for a concentration of shopping, culture and entertainment.
The retail industry is at a turning point, especially as consumer habits change due to Covid. More than before, physical stores and retail projects have to come with a strong and clear purpose, as well as a very precise customer target. The size of the project also greatly matters as it has to be kept at a human scale, not to forget what’s happening at the street level. Whatever the dimensions, any retail project now has to include shopping and entertaining activities, rich and varied enough to attract customers more than once. Considering the retailer’s large existing audience, Ikea in Copenhagen will probably succeed in becoming an anchor for the local community and attracting customers and city dwellers on a regular basis. Green Pea, on the other hand, bets on customer eagerness to know more about their impact on the planet, and possibly to lower it: but will the location, size, nature of the product offer and purpose of the department store be enough to guarantee a recurring customer base?
When it comes to Cidade Matarazzo, the ambition is to mostly attract wealthy customers while enhancing local communities. From culture to events, hospitality, housing and retail, all necessary features seem to be poised for the success of the project. It will also represent a great opportunity for Western brands to gain traction in Brazil. Unlike Hudson Yards in NYC, the project is also kept at a human scale. While the Rosewood hotel opened its doors at the end of 2021, the rest of the project should be completed next year but, due to Covid, it will probably be too soon to determine the success of this mixed-use project. Stay tuned.
Credits: IADS (Christine Montard)
IADS White Paper - A review of IADS members’ organisational changes
IADS White Paper - A review of IADS members’ organisational changes
Following a request sent by a member of the Association asking for more information on how other members were dealing with digital transformation from an organisational point of view, the IADS decided to dedicate its 2021 research to the topic by issuing the “Smarter department store organisations” White Paper. Through a review of department stores’ internal organisation evolution from 1928 to the current digital age, it appears that:
- Department stores have always been extremely complex structures since their inception,
- Adapting to an ever-changing context is part of their DNA. They have always adapted to successive market evolutions…
- …even though it often meant to answer complexity with new organisational layers and, ultimately, a more complex structure per se. Department stores answer to an increasingly complex world by an increased C-suite specialization and organisational inflation.
Also, it appears that aiming for a structural simplification will, this time, not be enough to fully adapt to the digital and sustainable age, which are both significantly challenging: it is all about re-engineering structures and processes with a new, more organic, approach. More radical changes might be needed in the mid-range to stay competitive.
Organic reinvention has been an organisational feature central to department stores from their inception, helping them to deal with an increasingly complex world
“Department stores are decathletes”. This sentence encapsulates the challenges embedded at the core of any department store in the world: their model concentrates a vast array of complex activities, and, in these days of omnichannel competition and digital unbundling, they have to be good at every one of them. This permanent necessity has translated into constant adaptation and the acquisition or generation of new and appropriate competencies. While such transformations have been relatively invisible from the customers’ point of view, each new iteration has left its mark on companies’ organisations.
While organisation charts are not an exact reflection of how companies work, they provide insight into a company’s perception of itself, as well as its formal internal power structures. They also allow comparisons, and the tracking of change over time. This is why the IADS has put together snapshots of store organisations during 4 key dates: 1928, 1994, 2015 and 2021.
In 1928, when the IADS was created, department store structures were already extraordinarily complex, in order to address the number of categories and products sold (as seen in the Harrods example shown in the White Paper). In addition, all stakeholders were taken into consideration (customers, employees, partners, shareholders), leading to the juxtaposition of many activities and competencies. This created a fertile ground for a subsequent complexification: with time, the C-suite progressively increased according to managerial evolutions and technological progress, without significantly altering a template that became increasingly anachronistic. With time, organisations became costly, complicated and difficult to transform.
This became particularly visible after 1994, the year when Amazon was created. While a few companies foresaw the danger and followed suit by launching e-commerce ventures (Macy’s in 1997, Nordstrom in 1998 and John Lewis in 2001), the rest of the department stores were still trying to solve the space productivity equation through a highly centralised organisation at the buying level. Even though a few IADS members looked for other approaches, this struggle persists today, and partly explains why adapting to a digital, highly-fragmented and individualised world has taken so long for department stores.
The temptation to answer complexity with increased specialisation and organisational inflation
2015 is the year most iPhones were sold in volume to this day. It triggered the development of m-commerce, a complement to e-commerce, adding to the difficulties of those retailers who were struggling to keep up with customer behaviour changes and the end of the boomer generation majority. Despite this, organisations remained mostly unchanged, with 4 to 6 direct reports to the CEO, covering “traditional” areas of the activity (Finance, Merchandising/Buying, Real Estate, Operations/Sales, Marketing and HR). It is striking that digital capability (whatever its name: digital, e-commerce, omnichannel) was not considered as a strategic feature per se at the time, but was rather integrated into a broader department. This difficulty of acknowledging e-commerce from an organisational point of view is a reason why Galeries Lafayette already had a Chief Transformation Officer, a fairly unique position at the time when compared to the others, to address this challenge.
The Covid-19 pandemic and the total reset of the retail industry that took place in 2021 accelerated the need for department stores to change and rapidly acquire the new competencies needed to strive in an omnichannel world. It explains why they responded to the increased complexity of operations by increasing the number of direct reports to the CEO, with one company for example increasing from 11 reports in 2015 to 18 in 2021. This organisational inflation also reflects a lack of clarity about the meaning of “digital transformation”: the answer will be radically different if approached through each of its components (platforms, channels, technology, products…) rather than through a more holistic approach.
Does structure always follow strategy? The digital transformation case
Should organisations have an individual dedicated to digital change, or re-engineer their structure into a “digital mindset”? Examples from other industries (mass distribution with Carrefour, water supply with Suez Group, luxury with LVMH) suggest that a digital transformation officer position is easier to implement than totally resetting and transforming an often century-old structure. However, the scope of these new positions rarely includes resetting the organisation as a whole, and often consists merely of injecting technological innovations, only contributing to increased complexity or worse, the creation of an additional silo.
The fact that different solutions are adopted is a signal that companies are probably in transition mode. Each of them has to make defining choices, between transforming the organisation as a whole or solely focusing on the customer-facing structures, and between creating a dedicated position at the top, or seeking to digitally pivot the whole organisation (and if so, how).
Two IADS members have set up a new approach to this question in 2021, by addressing the problem from the customer-journey perspective. Both of these approaches are radically different. Breuninger delegates the power to change organisations at the store level, by creating a new position with increased prerogatives and possibilities to change operational methodologies. Falabella on another side has created a new position at the HQ level, whose role is to detect potentially interesting ideas from within the company and implement them in a test & learn process, allowing, when successful, the definition of a new customer journey.
These examples suggest that there is a middle way and a soft method to answer this question. It also confirms that there is room for organisational innovation within the existing frameworks.
Simplifying organisations is key, but may not be enough in the future
These marginal improvements might not be enough. The recent new appointments at the Macy’s board of directors, namely the CEO of The Michaels Companies and the president of Zipcar, both experienced in organisational transformation, shows that department stores are well aware of the difficulty. Historically, department store organisations have been responding to immediate problems, by trying to adapt to the current “iceberg”, perfectly aware that other ones were coming but, understandably, unable to dedicate the necessary resources to deal with all of them at the same time.
This never-ending race is impossible to win. Even though their margin structure has allowed them to avoid icebergs so far, the market-changing conditions are now putting department stores at risk of running out of possibilities if they do not manage to radically reinvent themselves. This radical reinvention requires courage and obstinacy from the leading teams, as it involves long-term vision (strategic planning), radical questioning (unbundling of century-old activities as we start to see across the industry), and the capability to change machine-like organisations into more organic social bodies.
Credits: IADS (Selvane Mohandas du Ménil)
IADS Exclusive - Retail Review #1: Streetwear and Sneakers
IADS Exclusive - Retail Review #1: Streetwear and Sneakers
Keeping markets under close watch, IADS collected new, pure streetwear and streetwear-oriented store concepts from retailers around the world. This series shows various themes, experiences and displays, illustrating the richness and diversity of the streetwear culture and aesthetics.
Check out how retailers are using innovation, colourful layouts and modern thinking to upgrade the customer's shopping experience.
Louis Vuitton, Tokyo
Leaving behind its usual classic looks, Louis Vuitton’s revamped store is embodying a streetwear-oriented aesthetic. A dragon head in the window bears the initials ‘A’ and ‘N’, referencing men’s creative director Virgil Abloh and Nigo, guest collaborator and cult icon and founder of streetwear brand Human Made.
Off-White, Paris
Illustrating the luxury streetwear aesthetics, Off-White’s Parisian flagship store combines elegance with industrial rawness. A courtyard, a gallery and a market extending over three floors are gradually revealing Off-White’s diverse identity. On the third floor, the brand’s most iconic and beloved items, ranging from denim pieces to sneakers, are available to customers.
House of Vans, Mexico City
With its new Mexican store, Vans now offers an entire streetwear experience evolving around skateboard culture. The location houses a skatepark, a space dedicated to street skating, interactive workshops with artists and a gallery for rotating exhibitions. Visitors can also enjoy a movie theatre as well as Van’s kitchen, with some of Mexico’s best chefs.
More on House of Vans, Mexico City
Soldout Store, Seoul
The recently-established sneakers brand Soldout shows how physical retail and experience are key to the limited-edition sneakers market. Inspired by a winery, the space showcases a boutique and rare bottles of wine. The entire store consists of specialised spaces, including an examination room to check the sneaker’s authenticity, a packaging room, and a space to showcase the premium sneakers.
Supreme, Berlin
In Berlin’s hottest shopping neighbourhood, Mitte, Supreme offers a store with an industrial look as well as familiar elements, such as polished concrete flooring and a back wall plastered in iconography, all overlaid with skateboards. Furnishings are few and merely include clothing racks, a sales counter and a sculptural rock bench. The sound installation is a clear indication Supreme‘s new outpost isn’t only a transactional space.
Solebox, Barcelona
Barcelona’s new Solebox store offers a full range of streetwear products inside a market themed space filled with green plastic crates and boxes. The entire concept plays with the feeling of a grocery store with a fridge section displaying t-shirts and socks in the place of meat.
IADS Exclusive - Supporting retailers in their CSR journey: A talk with Pando Fashion
IADS Exclusive - Supporting retailers in their CSR journey: A talk with Pando Fashion
Created 2 years ago, Pando Fashion is a French company specialised in consulting for sustainable fashion. Its co-founders Laëtitia Hugé and Stéphane Piot are helping companies every step of the way in their CSR implementation, starting with a diagnosis using certification ISO 26000, to building custom strategies and embarking all teams. Pando Fashion is working with companies such as Moncler, Louis Vuitton, Zadig & Voltaire, Besson Chaussures, IKKS, Maje, Sandro, Lemaire, Institut Français de la Mode (French Fashion Institute) and with BTB fashion platform LeNewBlack. Why Pando? It’s the name of the oldest tree in Utah in the US, and it also means transmission in Latin.
Where and how to start with CSR
*IADS - How do you advise your clients to approach customer-facing initiatives (like product and brand certifications and labels) versus operational initiatives (using more efficient light-bulbs...)?*
Pando Fashion – First of all, they have to keep in mind that many factors are considered in a product lifecycle: raw materials and factories of course, but also logistics, carbon footprint, impact of store operations (such as energy consumption, waste…). Then comes the consumer’s part of the product lifecycle: use of the product, washing habits and recycling... Each step of the product lifecycle corresponds with specific actions: from customer-facing ones with the use of labels and certifications for sustainable or recycled materials for instance, to corporate communication for company energy consumption.
*IADS - Sustainability is a lifelong project, it has to be maintained over time. When does Pando step in or step out of the process and how do you set up organizations to tackle these issues for the long-term?*
Pando Fashion – Of course, we can start at any step of the CSR journey, whether it’s from the diagnosis phase or to support a company once its strategy is set, or on specific projects. We are helping companies that are at the very beginning of their CSR project, and others that are quite advanced. Sometimes companies think they have done nothing yet, but in fact they already have set actions which we will use as levers to move forward faster: that’s also what the diagnosis phase is made for.
Ideally, we step out when the company is autonomous on the CSR topic, which means they have enough knowledge and reflexes to continue implementation or run a new project by themselves. Also, there would be no point running long missions as we are helping companies to focus on what is the right part of CSR for them.
*IADS - Sustainability starts from the supply chain. How does your firm support optimizing it and creating a greener process from the beginning to the moment the products reach the customers?*
Pando Fashion – It’s a new mindset between manufacturers and brands. First thing is to get as much traceability information as possible on all production tiers: tier 1 is for the factory making the product, tier 2 for the fabric, tier 3 for the treads, and tier 4 is for the raw material. We will work on both processes (where the product comes from, how many tiers are they) and tools (helping to follow traceability). The more tiers you have, the more difficult traceability will be.
When we are dealing with questionable products, we will advise brands on how to help manufacturers improve their process, as you don’t change suppliers overnight. Pando is also helping brands to prioritize.
For instance, in the case of a leather bag, the biggest impact comes from the leather as the tanning process is easy to improve. Then comes the metal parts: since there is not much traceability for brass and steel, we will recommend the use of alternative metals.
How to avoid greenwashing
*IADS - How do you help your clients avoid greenwashing and achieve authenticity when tackling sustainability and communicating their efforts?*
Pando Fashion – The rule is simple: first, do something, be humble and then communicate. You must have consistent results before communicating to customers. Some companies want to start communicating as soon as they have their strategy set, but that is way too early. Sometimes it’s the opposite as some are too cautious. Several levels of communication are possible: proportion of sustainable materials, of local production, etc…
It’s also very important not to overwhelm customers with too much information. Consumers are focusing on what is in front of them: the product. It bears the first level of information: the product tag informing about materials or “made in”. The second level is the retailer’s website providing more information. Another level can cover the store energy consumption question, the HR inclusivity policy: usually such information is for the corporate communication level.
*IADS - What is the biggest mistake that you see retailers making when it comes to approaching their sustainability initiatives?*
Pando Fashion – The biggest one is about the amount of communication compared to the reality and authenticity of actions. For instance, H&M used to over-communicate on their Conscious line. It was too much knowing this line was only 10% of their global offer, so they were accused of greenwashing. Even though companies such as H&M know being more sustainable is necessary, their business model and price point don’t allow them to have more than 10% of sustainable products.
On top of that, H&M and most retailers have to address all customers in their communication. Usually, we consider 10% of consumers are engaged in sustainability, they are considered activists. 60% are interested in the topic but won’t necessarily buy sustainable products, 20% don’t care and 10% are against sustainability. In that sense, the easiest way to be sustainable is to be sustainable-native.
Pain points and success stories
*IADS - From your experience, what are the pain points retailers are coming across?*
Pando Fashion – The ambassadors of sustainability are the sales associates, and they are hard to convince since they consider that sustainability equals an additional workload. When it comes to sales associates, there are different strategies. With Besson Chaussures, we trained the sales managers in each store for them to become the store go-to person for CSR questions. Considering their position in the organisation, they were ideally positioned to encourage sales associates. With Moncler, we had distance training directly with sales associates. In any case, and as for customers, it’s important not to overwhelm them with too much information but feed them with key elements that can easily be shared.
*IADS – Resources are limited for retailers when approaching CSR. How do you help organizations find and allocate the resources, within the existing teams, to execute, promote and train on CSR?*
Pando Fashion – Since they don’t have any internal knowledge, most of the brands and retailers are asking for external help at the beginning of their CSR journey. On top of helping them start the process, we are suggesting the most efficient and least time-consuming organisation. The key idea is autonomy: CSR has to become part of the company processes as for instance; digital working is. We also help customers in their research of CSR managers. When the latter are being internally promoted, we are training and coaching them.
In CSR, we work with 3 pillars: environment, social and economics. CSR is often put under the HR umbrella because of the social component. What works best, according to us, is to have a CSR global director and one manager for social questions (working with HR) and one for environmental questions (working with product and marketing). In a way, as for digital functions, CSR functions might evolve, reduce or even self-destruct, once CSR is implemented and infused in the company.
*IADS – Can you share any success stories or examples of retailers that are excelling in their efforts or approach?*
Pando Fashion – With the multi-brand luxury menswear chain Lothaire, we started the process from the values and DNA of the company to build their CSR policy. For instance, they are very much committed to services and local communities. Starting from that, we helped them build and increase their repair service and to create a second-hand shop-in-shop.
At Moncler, the training of sales associates was organised online more like a conference than as a training. It was perceived as something motivating, and absolutely not as an additional task. They really felt proud to be included in the company’s CSR strategy. As a result, the training answered many questions: CSR of course, but also motivation, communication and belonging. These are key components, especially at a time where retail staff is scarce. Such actions are also part of the employer’s brand and of its attractiveness.
Measuring ROI
*IADS – What are the KPIs you’re using to measure the impact of Pando’s actions (cost impact, share of organic materials, carbon impact…)?*
Pando Fashion – There is no definition of sustainability today so it’s up to each brand and retailer to set their own definition and to be very clear about it. Yet, the first KPI all brands are monitoring is the share of sustainable products in their offer. The ‘made in’ share is also an important KPI. Limiting the number of SKUs and increasing the share of carry-over products is also monitored: in that sense, sustainability supports margins. The share of labels and certifications used along the supply chain is another KPI. KPIs will differ depending on retailers and CSR strategies, business model and DNA. In any case, retailers should prioritise and decide the KPIs to focus on.
*IADS – What are the most important KPIs retailers should use to measure the ROI of their sustainability efforts?*
Pando Fashion – The most important today is the share of sustainable products in the offer. It’s also the easiest message to convey to customers, especially with all the labels that can be confusing to shoppers.
Issues with labels
*IADS – There are many labels (BCorp, Amfori, GOTS, etc...) that are very confusing. On top of that, retailers are starting their own labels. What are your thoughts on the over-complication and multiplication of sustainability labels? Does this really help consumers or is this something that retailers are doing to showcase their efforts?*
Pando Fashion – As long as we won’t have a global and single label, it will be very difficult to facilitate communication with customers. Yet, labels are of some help to customers as they are speaking to 70% of consumers (the 10% activists and the 60% open to CSR questions). We advise brands to focus on 6 or 7 labels, not more: among them are GOTS (Global Organic Textile Standard) and OCS (Organic Content Standard) for organic raw materials, GRS (Global Recycled Standard) and RCS (Recycled Claim Standard) for material recycling, RWS (Responsible Wool Standard) for animal welfare and LWG (Leather Working group) for responsible leather.
As for labels such as Galeries Lafayette’s Go For Good and Printemps’ Unis Vers Le Beau, they are helping the consumer in the end. It’s a good initiative since we don’t have a global label yet. For sure those labels have weaknesses as they cannot be perfect, but they are transparent: you can go on the corporate websites and have reliable information about the rules and criteria used. Of course, such labels might become useless when a global label will exist.
*IADS – Do you think any particular label or certification will outlast the others as the main one that retailers should obtain?*
Pando Fashion – The strongest is GOTS especially because of its traceability rules. GRS really secures authentic recycled materials. When it comes to animal welfare in wool production, RWS is the best. In any case, in order to facilitate communication and be pedagogic, retailers should explain in a few words what are the labels and why they are good.
*IADS – What are the main topics/issues that your firm is focusing on in the next 2 years?*
Pando Fashion – In the next 2 years, Pando Fashion will work more on the customer’s autonomy. To that end, we will give access to more information on our website to transform it into a platform. All companies have to enter the CSR topic. Right now, it’s still considered as an added value. In 2 years, it will be a standard so retailers should act fast. The sooner the better!
Contact: Stéphane Piot
stephanepiot@pandofashion.com
+33 6 63 78 12 19
Credits: IADS (Christine Montard)
IADS Exclusive - Retail Review #6: disruptive stores
IADS Exclusive - Retail Review #6: disruptive stores
Keeping markets under close watch, IADS collected creative disruption concepts from retailers around the world. This series of stores offers astonishing displays that will give customers a whole new view of today’s physical stores.
Check out how retailers are using creativity, technological innovation and modern thinking to upgrade customer’s shopping experience.
Anya Hindmarch, London
Anya Hindmarch‘s audacious opening of five separate establishments creates the illusion of a small village in London‘s chic Chelsea shopping neighborhood. The innovative cluster of spaces is anchored by Anya Café, a stylish place to sit and have a bite or a drink. ‘The Village’ is set up as an evolving retail concept, and as such the cluster of spaces will see regular tweaks aligned with Anya Hindmarch‘s creative scope as time goes by.
MORE ON Anya Hindmarch, London
Choosebase, Tokyo
Seibu’s new Choosebase store tackles the OMO trend (online merges offline). Through the use of QR codes, the customer’s chosen products are virtually placed in baskets to be picked up at the exit of the store, removing shopping carts to enhance the Instagram-worthy experience.
Haus, South Korea & China
Haus is Gentle Monster’s new innovative and disruptive step in upping the ante to develop shopping experiences. The concept incorporates the experiential creativity and vision of Gentle Monster, while encompassing sensual artisan cosmetic brand Tamburins and fantasy-inspired dessert restaurant Nudake. The spaces are infused with contemporary art pieces including a wall art installation covered in tree branches which aims to express the intersection of luxury and rawness.
More on Haus, South Korea & China
Harmay, China
Harmay, known for creating design-led retail spaces, has opened impressive experiential stores in Shanghai and Beijing. The company’s turnover is largely based on online sales, but it uses the physical stores as an e-commerce fulfillment site. On top of typical beauty products, the stores extend the offer by selling fruits and tech products.
SuperMarket, Toronto
The latest outpost of Toronto's Stackt Market is ‘SuperMarket’, a cannabis store with a playful design. The new store is located in a shipping container and features an interior design aesthetic that is inspired by a traditional neighbourhood grocery store: retro elements are infused with a palette of popping colours, giving a slight cartoon impression.
Figure Eight, NYC
Figure Eight is a 100% sustainable popup in downtown Manhattan that is all about green and vegan goods, not to mention women’s empowerment and climate action charity. The luminous boutique offers a beautiful selection of sustainable brands and during the tenure of the pop-up founders aim to offset 100% of its carbon emission and water consumption, verified by a certification body.
IADS Exclusive - Business Case #8 – Green Pea: building up sustainability from within
IADS Exclusive - Business Case #8 – Green Pea: building up sustainability from within
*IADS has reported how IADS members accelerated on the sustainable front since the beginning of the pandemic in 2020 (see our latest report on IADS members’ initiatives here). They transformed their organisations from within (with dedicated committees benefitting from increased powers, and often in direct liaison with the C-suite) and communicated initiatives and changes in a crystal-clear manner to the final customer. This also translated into pain points as all these initiatives require resources, which can be overwhelming given the number of certifications and labels, and can also, sometimes seem too far-fetched compared to the immediate challenges posed by the state of the business. In other words: just like digital transformation, sustainable adaptation is costly, takes time and energy, and requires organisational re-engineering.
This is the reason why we decided to look at “Green Pea”, a new type of sustainable business, the first self-proclaimed 100% sustainable department store in the world, and which reverses the problem. Green Pea tries to bring an answer to the following question: how to build a profitable business that takes for granted the sustainable approach?
We looked at the key learnings from this business case and tried to isolate the most interesting ones for IADS members.*
Context
Green Pea has been founded by the Farinetti family, who also founded Eataly back in 2007.
At the time, the reasoning for Eataly was simple: Italy as a concept was a strong brand recognized worldwide, and the Italian cuisine was also universally recognized. Eataly therefore capitalized on the possibility to enjoy fresh food direct from the producer, that could be either bought or eaten on the premises, combined with ideas, images and clichés customers might have about Italy as a country and a way of life. The first Eataly opened in 2007 in the city of Turin, on 12,000 sqm (for comparison, the Milan store measures 5,000 sqm and the Rome one, 10,000 sqm).
Today, Eataly represents 42 stores in 16 countries, operated either directly (including in joint-venture) or through partners. The first market for the company is the US, which, with 8 stores, represents 65% of the total turnover (estimated as a whole around € 690 – 720 M pre-pandemic). To have an idea in terms of turnover, the historical Turin store achieves € 32 M a year on 12,000 sqm, to be compared with € 75M in New York (5,000 sqm) or € 44 M in Chicago (6.300 sqm).
Based on this success of an “all Italian plates and ingredients” formula, the Farinetti family then decided to capitalize on the “Eataly of things” with a focus on what the country is reputed for: food, fashion, design. And in the same manner as Eataly, which is all about local, proximity and “slow food” (a novel positioning back in 2007 for a supermarket), this new project should also tackle sustainability in retail in a new manner.
The claim
Green Pea is the first “green” retail park in the world, opened in December 2020 in Turin, in the same building that hosts the Eataly store, on 15,000 sqm and 5 floors (it is not clear what the Green Pea founders mean when talking about a “retail park” as the format resembles very much a department store one). It aims to answer a seemingly unsolvable question: “should we stop consuming to preserve the planet?”. Green Pea aims to show that it is possible to responsibly consume by setting sustainability as a non-negotiable prerequisite and make it desirable by surfing on the “Italian” aspect of its offer and approach.
The whole company has implemented sustainability at the core of its business model, by setting up a self-imposed Manifesto in 10 points that provides clear and strict guidelines on how the business should be conducted, from day-to-day operations to strategic vision. For instance, Green Pea affirms that in order to efficiently contribute to society, a department store should address new categories beyond selling fashion goods and other “traditional” categories, to prove that it is possible to live in a sustainable manner at no additional cost. This is why Green Pea sells energy (100% clean), transportation (e-cars, e-bikes…), in addition to furniture, design, cosmetics and fashion.
To exemplify the level of detail, the Manifesto states, in the furniture category for instance, that sold items should not (of course) compromise on design and quality, but also abide by strict self-imposed rules (such as limiting formaldehyde emissions, using wood coming from renewable sources and biodegradable and recyclable plastics). The company also commits to planting a tree for each piece of furniture sold, to help consumers recycle or return their pieces when not needed anymore, and to show suppliers’ information about the manufacturing process in total transparency and clarity.
Even though the Italian aspect of the business (fashion, design) is clearly visible, the most striking in this Manifesto is probably the strict methodology applied in every operational and sourcing aspect, as well as the clear communication in simple words about it. It is clear that the main focus is to ensure that customers do not associate sustainable options with high prices.
In parallel, and this also transpires during the visit, the “Eataly of things” aspect somehow misses the point as the Italian-focused offer somehow distracts from the fact that entering Green Pea is all about deciding, as a customer, to have a new approach to consumption.
How does it translate in reality?
First of all, the building itself has been fully built with recycled material (wood, metal, glass) which can all have a second life in case the building has to close. In other words, the architecture can be fully taken to pieces and used to build another structure. The structure is classified Nearly Zero Energy Building (A3) thanks to the materials used, but also the approach to energy:
- Photovoltaic panels (which are integrated into the decor, in the form of giant flowers) and wind turbines provide near to 90% of the energy needed for the lighting of the building.
- It also uses the energy generated by the footfall itself, in a quite literal manner: in all floors, piezoelectric zones use the energy diffused by the steps to also produce electricity.
- Heat pumps installed in the foundations of the building provide heating of both the building (88% of the need) and water (87% of the need), which is also kept circular thanks to a closed-circuit allowing the building to be free from external water supply (it also recycles the rains).
- Within the building, 2,000 trees and plants are also grown, which contribute to purifying the air while also setting up a nice setting for customers.
However, a green building is not enough to make a sustainable strategy. This is why Green Pea founders have spent 2 years prior to the opening to assemble a 100% sustainable product offer that goes beyond the usual categories found in other department stores (fashion, design), totaling more than 100 brands and partners in this adventure.
A department store, really?
The approach taken might seem counter-intuitive for any person familiar with department store structures, with a disturbing floor plan:
- Ground floor: museum, energy and transportation goods
- First floor: home, furniture and design goods
- Second floor: fashion
- Third floor: beauty, books and restaurant
- Fourth floor: members club, sauna, swimming pool and recreation surface.
Starting with a museum to educate customers about the need to care for the planet and how to behave sustainably seemed crucial for the founders. This is why the first things seen at the entrance are the structure and construction details of the building, explained and dissected in simple and amusing ways, to entertain and educate both adults and children. It shows how the building saves energy and water. This is the first touchpoint of a customer journey mixing discovery with education as all floors also contribute to sharing knowledge by explaining how materials are produced and how they impact the planet compared to non-sustainable options.
Also on the ground floor, the founders wanted to address the most basic customers’ needs: energy, money and communication. This is the reason why they have offered green energy suppliers (Enel X, Iren…), new and second-hand cell phone sellers (TIM, Samsung…), green banking players (UniCredit, Mastercard…), green & perchloroethylene-free laundry, and an electric vehicle manufacturer (Stellantis, which displays all the e-cars produced by the brands pertaining to the consortium, including Jeep, Chrysler, Peugeot) a significant retail and showroom space, to educate and sell.
At this point it is key to note that during the visit, the CEO stressed his two main goals were:
- To contribute to making the sustainability topic an everyday cultural one (i.e. knowledge should help customers to address this topic with more confidence, and help them make enlightened decisions). This translates into a large amount of information made available across the ground floor (but also in the other ones), as well as tips and behavioural advice to make an impact in the everyday life, streamed in the Green Pea app, downloadable for free.
- To propose only sustainable options that do not cost more than non-sustainable ones. This means that prices are always clearly displayed and explained, including their margin components, to help customers to make arbitrations.
These two aspects are a constant when visiting the upper floors.
On the home & furnishing floor, for instance, customers can have a fully equipped, 100% sustainable kitchen, ready to be set up, for as low as € 3,500 VAT included. Green Pea worked with manufacturers on materials to reach this impressive retail price (which also helped Green Pea launch its own private label, Green Pea Casa). Of course, the range of products offered also includes more luxurious brands, leading to higher prices (from Whirlpool to FontanaArte, including also Guzzini or KitchenAid). All across the floor, customers are informed of the nature of the components and materials, where they come from and to what extent they impact the environment, as well as a comparison with non-sustainable options.
The fashion floor displays 65 brands in corner or shop in shop formats, of which 70% are operated by the brands themselves. This includes local brands (Esemplare, Antidoto 45, Giampaolo, PT Torino) or larger ones such as EcoAlf, K-way, Timberland, Superga, Kappa, Sebago, Borbonese, Napajiri or Patagonia. All staff are paid by the brands and trained by Green Pea. The RTW section continues on the third floor as a small section of the beauty floor is dedicated to luxury and fashion, with exclusive shop in shops (specific to Green Pea) from Cucinelli, Herno, Zegna and Sease. Both floors (fashion and beauty/luxe) also propose tailor-made experiences, be them via personalization ateliers (from specific details to the production of the whole garment if needed) for fashion items, or via individually formulated cosmetics according to each one’s skin, exclusively developed on site with Alkemy Spa.
When it comes to the food offer (located at the cosmetics floor), the pricing range is also quite wide, from a bar with entry price point snacks (using all Eataly ingredients and suppliers) to a Michelin-starred restaurant.
Finally, the rooftop is dedicated to the member’s club, including a restaurant, a terrace, a sauna and an infinity pool. To be a member of the club costs 300 euros a year and gives full access to the location (to be noted: the regular customer loyalty card, which does not offer access to the club but the same benefits otherwise, from anticipated sales, points and special promotions, only costs 50 euros a year).
What can we learn from this model?
Green Pea is all about being “green” without being suspected of greenwashing. Having a fully sustainable building and displaying only sustainable brands is of course impressive and nice but does not fully support the “first sustainable retail park” claim of the retailer as these initiatives can be also spotted elsewhere in the world. This is the reason why the educational part of the customer journey is key, as it helps the retailer to achieve 3 goals:
- Contribute to expanding the general public’s basic knowledge on materials, practices and behaviors.
- Show in quite a literal manner the initiatives they have taken.
- Promote the selection of brands they have made.
This focus on information is key, as it differentiates them quite a lot from other retailers who promote certifications, initiatives and labels, but who do not really contribute to educating customers on a broader level and, from there, influence culture as a whole. In other words, they are using their physical retail space to create and pre-empt content on sustainability.
This is completed by a specific approach when building the assortment and selling it:
- All salespeople are paid by the brands but fully trained, on a regular manner, by Green Pea on sustainable topics (they are given information to be able to stand a conversation addressing their brand of course, but also the rest of the assortment, Green Pea’s approach and even broader conversations).
- The price range is adapted and answers concerns customers might have about having to pay more to have the same products, but made sustainably.
- By proposing a paid loyalty program (a strategy the IADS is very much supportive of), they astutely create a club of “those who know vs. those who don’t”, therefore creating some kind of social curiosity and interest for sustainable topics, through a membership giving access to an exclusive location at a reasonable price.
Binding all these elements together helps Green Pea to be credible when they claim to be the place to be (and to shop) when it comes to sustainability. However, is this enough to make a business? Many questions are raised when looking more in detail at the model.
First, in terms of traffic, it is of course extremely probable that a 100% sustainable “shopping temple” is attractive to many customers, at least to see what it means. But how is it possible to make sure they come back twice or more? The ground floor, with its utilitarian offer (green energy, finance and communication), is, without a doubt, interesting but raises questions that are more about the customers’ lifestyle than the simple joy to go shopping. Is that amusing for them in the long run? Moreover, one might wonder to what extent a ground floor with such an offer (including a museum to educate customers) could be reproduced elsewhere in the world, in a more competitive context than this specific part of the city of Turin.
This leads to another crucial question, the business potential of the store. When asked about the profitability of the model, Green Pea’s CEO answers that the store has not been built with sustainability seen as a perk, but as a key constitutive element. As a consequence, the brands’ margin model remains the same as for a ‘normal’ business, as sustainability does not create a specific economic advantage or handicap. For him, it is just the way to see things today.
However, it is not really possible to know how well this concept can perform yet. For one thing, it opened in December 2020, in between lockdown episodes, in Turin, which is a smaller city than Milan or Rome. Therefore, KPIs are not relevant for now. Secondly, during the visit, it seemed that the Italian approach of things was too diffused to be as impactful as in Eataly (plus: does it make sense in the same way?). As a consequence, this side of the marketing approach might be less impactful than simply relying 100% on the “first sustainable retail business model”. At the same time, relying 100% on the first “sustainable business model” might limit the number of brands that can be part of the concept, leading to questions on the maximum profitability of the model: can it be comparable to what we know in other department stores? What do you do for instance when Louis Vuitton or Chanel do not fit with the commitments made in the Manifesto? And is the “first sustainable retail business model” enough to become a long-lasting attraction for customers that can get easily bored, and who might not enjoy being reminded of serious things every time they take a trip to the store?
So far, even though the whole Green Pea concept consolidates a series of new approaches and proposals to the customer in the same way that Eataly did back in 2007, it seems that it is still in the laboratory stage, not in terms of maturity of the concept (which is already quite convincing), but in terms of realism of the economic equation. The ingredients that made the success of Eataly (local, circularity, Italian identity) might not be enough to be transferred as such in the Green Pea retail concept, at least outside of Italy.
Credits: IADS (Selvane Mohandas)
IADS Exclusive - Sustainability: An acceleration post-crisis
IADS Exclusive - Sustainability: An acceleration post-crisis
If the pandemic wasn’t hard enough already on retailers, it also accelerated topics such as sustainability. Consumers have become more aware and educated on CSR related topics while they were stuck at home with more time to think about their environmental impacts - especially as this relates to retail. This has created increased importance for retailers to ramp up their sustainability initiatives as well as communicate them.
A snapshot of sustainability before and after a global pandemic
Before the “first wave” of the pandemic in March 2020, IADS polled its members about their overall vision and approach to sustainability and its structure. We had 5 members complete the questionnaire (Breuninger, El Corte Inglés, Manor, Sogo, and The SM Store). The survey asked members to define their sustainability vision, how they communicated internally and externally at the time, as well as clarify its organisation and programmes.
After the first couple of waves of the virus, which had interrupted business for department stores across the world, IADS performed another survey to check in on our members to better understand what main areas of sustainability have accelerated by July 2021. Six members participated in the survey including Beco, Breuninger, Magasin du Nord, Manor, Sogo, and The SM Store. From this survey, we wanted to understand what our members were focusing on in these unprecedented times, how they were communicating with customers, what pain points they have specifically faced, and what has changed organizationally due to sustainability’s heightened importance in the past year.
Enhancing communication and avoiding greenwashing
In the first survey, conducted in March 2020, members cited various ways that they approached the communication of sustainability efforts and protocols:
- Some used internal tactics by either creating a dedicated website page or promoting sustainable products through their own logo. Manor for instance would add a ‘Manor Respect’ tag on physical products and on the website to indicate sustainable products.
- Breuninger shared that they communicate initiatives and spearhead projects through an employee app which allows them to easily store guidelines and share progress on projects and initiatives.
- Other mediums mentioned used to share sustainability involvement included social media, marketing campaigns, and store displays.
During the second survey, conducted in July 2021, a new and major challenge of communication was to avoid greenwashing, but this is easier said than done. IADS members have shared their approach to ensuring that their messaging is not construed:
- Hard facts: Sogo certifies that the contents of the messages to customers are factual without ambiguities and supported by relevant certifications. Manor focuses on only hard facts communication.
- Cooperation: SM works with their suppliers and consigners so that the messaging is more seamless across all external partners and they make sure that the eco-friendliness of the products are communicated consistently across their different channels.
- Tone of the communication: Magasin believes that being consistently honest and authentic will eventually win over any sceptic as it is hard to argue with a proven track record.
Evolving organizations
Organizationally, most of the respondents shared in the first survey conducted in March 2020 that they have cross-functional committees with representatives from different parts of the organization, thus ensuring cooperation and information sharing across divisions. These committees typically have a link to the C-suite. Sogo, for example, has an ESG Committee which is headed by the Executive Director and comprises members from all major departments. This committee is in charge of formulating ESG strategies, sustainability reporting, stakeholder engagement, materiality assessment, monitoring the performance of initiatives, and the promotion of ESG issues internally and externally.
By the time the second survey was conducted in July 2021, IADS members had recognized that CSR topics require dedicated resources to be able to carry out and monitor initiatives:
- Beefing up the CSR team: Breuninger has hired more people in the corporate responsibility unit as well as in the buying department to meet the growing needs. Manor will be reinforcing the sustainability department by one headcount.
- Doubling down on the pre-pandemic committee approach: The SM Store created a sustainability steering committee made up of executives from different functions to ensure a singular message. Magasin du Nord does not have a dedicated CSR team, but members from the marketing and HR teams have been used as project managers to address changes, implement training, and manage external contacts. Sogo has not had any changes and continues to support its ESG Committee.
- Looking for external support: Beco has decided to start a sustainability programme and has hired a company to help them go through the initial steps.
Introduction of new pain points
When conducting the first survey (March 2021), IADS did not know to what extent sustainability topics would progress in the coming years, but through the second survey (July 2021), conducted 15 months later, the Association witnessed the face that CSR topics have become top of mind for many of our members. The global pandemic has accelerated the awareness of consumers as well as the importance of making a stance regarding overall impacts for businesses. But this heightened awareness has also introduced new pain points for retailers.
When posed the question about what major sustainability pain points members are being faced with, they all had different answers:
- For Breuninger, they find that the multiplication of labels is difficult to grasp as well as setting up green logistics, green packaging, and a sustainable supply chain.
- Sogo expressed that it is difficult to set medium-term goals and targets as well as raise the awareness of employees regarding ESG issues.
- Manor shared that they are struggling with having enough resources to implement all the initiatives around sustainability. On a similar note, Magasin du Nord stated that sustainable options do not highlight themselves and that it takes extra resources in stores and online to arrange and label these items. They also mentioned that educating customers on more sustainable options is not simple.
- Finally, SM shared that the pandemic as a whole led to a disruption of their sustainability rollout.
Programmes and initiatives
IADS members have rallied their troops to be able to step up to the new demand that sustainability has imposed. There has been a lot of progress made in terms of programmes and initiatives, especially ones that were fast-tracked due to the pandemic. From members who are taking their first steps to tackle CSR topics to those that have extended resources to meet growing demands, all members have some very exciting and noteworthy activities they have been working on since the beginning of the pandemic. Almost all members were focused on reducing overall waste, especially in the form of offering alternatives to the use of plastic and paper bags at the point of sale. These programmes have matured and progressed quite a bit in the past year.
Breuninger has replaced plastic bags with reusable ones and added a green option for online sales to remove any additional packaging. They also revised their guidelines for sustainable articles, prepared a responsible sourcing policy, and prepared an animal welfare policy targeting future goals. The retailer has also introduced digital receipts through their mobile app to reduce overall paper waste in stores.
Magasin du Nord has focused on their own brands to achieve the best certificates and higher composition of sustainable materials. They also are committed to using more sustainable packaging without compromising durability and strength. And they are focused on reducing food waste and getting more out of less when it comes to electricity and other resources in general. They have also partnered with a popular second-hand store (Time’s Up Vintage).
Manor has stopped offering free bags in store, started a hanger recycling program, and implemented reusable containers for internal deliveries. They also rolled out their partnership with Too Good To Go (a mobile application that connects customers to restaurants and stores that have unsold food surplus) nationally as well as launched the rebranding of their sustainable label and reinforced it with internal guidelines and training.
SM Investments Corporation sealed its commitment as a supporter of the Task Force on Climate-related Financial Disclosures (TCFD) in a strong bid to ensure its businesses meet global sustainability targets.
Sogo has decided to focus their marketing on digital mediums rather than physical ones. They have also created an emergency response team to devise strategies around virus preventative measures, ensured that food waste is composted or turned into animal food, organized charitable events and donated face-masks and gel, and pushed the use of the Sogo Rewards Mobile App to reduce the use of physical gift certificates.
Beyond those that completed the survey, IADS members have been incorporating new programmes that are worth noting for inspiration.
El Corte Inglés is involved in a wide range of CSR projects touching on logistics, merchandise and energy consumption. They partnered with Llewo, a company specialized in social and eco-sustainable logistics management: they will work together to evolve and grow the last-mile delivery from a sustainable and social point of view. The Spanish retailer also joined the Sustainable Apparel Coalition (which is responsible for the Higg Index), an international alliance for sustainable production within the footwear and clothing industries. In terms of commodities, El Corte Inglés reduced its electricity consumption by 25% in just five years and uses renewable energy sources to run its business in Spain and Portugal.
Since its Go For Good programme launched, Galeries Lafayette opened (Re)store, a new women’s fashion space. The section features second-hand labels and circular fashion brands, ranging from affordable clothing to luxury handbags. This month, they opened a Pangaia (loungewear brand) carbon-neutral pop-up store: they nailed both a hot and sustainable brand as well as being able to operate responsibly.
Falabella is also very much involved in CSR questions. They committed to supplying 240 stores in Chile and Peru with 100% renewable energy by 2022. On top of that, 34 stores in Chile, Colombia and Peru received the international certification in Leadership in Energy and Environmental Design (LEED), a distinction granted by the U.S. Green Building Council (USGBC), an organization that aims to promote sustainable construction and development.
Measuring progress
The conducted surveys reveal that there has been an increased awareness and importance put on topics revolving around CSR. Some members have even noted that CSR efforts have a direct correlation to business activity and performance. The survey revealed that sustainability programmes and investment in these types of efforts will continue to accelerate. With the increased activity, there will also be more focused working groups formed cross-functionally and even additional headcounts brought in to help manage the new initiatives.
As members are implementing new programmes and investing money in sustainability efforts, it is important to understand what happens next. How are initiatives measured and how do they know if the time and investment were worth it? All members mention that they define relevant KPIs to quantitatively track predefined targets as well as gather feedback from stakeholders, including customers. Some of these KPIs are:
- Energy consumption per operating area
- Amount of food waste recycled
- Fewer paper mailings based on a specific year
- Percentage of CO2 reduction
- Percentage of turnover of sustainable goods (private label or other brands)
- Percentage of reduction of packaging, waste, and plastic
- Measuring the composition of sustainable materials in each product sub-category
- Tracking customer feedback and brand awareness (El Corte Inglés uses Reptrak as a way to measure reputation, brand, and ESG performance)
IADS also conducted research on the efforts and initiatives of American players such as Amazon, Walmart, HBC Group, and Macy’s Group which all have a robust offering of CSR communications. Comparatively, and as IADS members are quite heterogeneous, some members are in line with the American retail giants, while others are just getting started. This is normal as the prioritization of these efforts heavily depends on the markets they serve as well as customer demands.
Overall IADS members are ramping up their CSR projects and teams and have seen an accelerated demand for such initiatives in the past year. Sustainability programmes used to be ‘nice to have’, but they are now becoming crucial among retail organisations. As commitments to responsibility are made, it is important to follow through and share results through defined KPIs and transparency at each step of the journey. IADS members have found that facts-based communication (sharing KPIs and progress) is a key way to avoid greenwashing and include the customer in the brand’s sustainability journey.
Credits: IADS (Mary Jane Shea)
IADS Exclusive - Do department stores still need private labels?
IADS Exclusive - Do department stores still need private labels?
*Private label development is in full swing for some retailers, especially for the big-box ones in the United States, reflecting a successful business model that Millennials are also favouring. The penetration of private labels amongst Millennials is 1-2 points higher than prior generations and continues to grow.
Usually considered as a margin enhancer, a great tool to recruit customers, a way to develop loyalty thanks to attractive price points, or an asset to emphasize the store brand message, private labels can meet tremendous success for retailers such as Target. But for others, they struggle to reach profitability.
To stay relevant these days, private labels not only have to offer an excellent product implying a great deal of research and creativity, but also differentiate from competitors, and even outdo national brands. As retail consultant Stacey Widlitz sums it up when discussing Target’s success in launching private labels: “They’ve basically been going around saying, ‘Who does it best and who does it worst?. Let’s replicate what the winners are doing and take on the losers and do it better.’” Is it really that simple?
Private labels currently represent an average of 6-7% of the IADS members’ turnover (data from IADS Merchandising meeting dedicated to private labels, January 2021). This part of their business has been reorganised in the past years and months raising critical questions: do department stores still need private labels, are they still good at this historical part of their business?*
The price appeal
It’s a well-known fact that price is a key component when it comes to private labels. It’s even the first idea that comes to mind, especially in the food area. With Covid, such products have recently grown even bigger due to newly price-conscious consumers finding themselves with less money. According to a McKinsey study from November 2020, when consumers are asked why they switched to private labels, more than 45% said price was the primary reason.
A Nielsen study from 2018 also states that 67% of customers think that private labels are extremely good value for money. This high percentage reflects the fact that own brands are not about being the cheapest they can be, but more about being cheaper than national brands (and filling a void on the market), whatever their price points are. As for department stores, they have no interest in trying to be the cheapest: they would put themselves in direct competition with Amazon Basics own label, a competition that we know is lost before even beginning…
So, should department stores continue using private labels to offer an entry price point to customers? Does a relevant product offer have to come with a low-price positioning? With its ‘Monoprix Gourmet’ brand, Monoprix (the French urban “variety” store) shows that the key factor is not about being the cheapest, but about being cheaper. Relying on upscale urbanites willing to pay more for quality food, the retailer developed a range of 700 gourmet products. There were no such products in supermarkets: ‘Monoprix Gourmet’ filled a void and became extremely popular with rather expensive products.
The Monoprix Gourmet example shows that a cheaper price point works if it comes with a strong dose of creativity, in all possible ways: in that case, it comes with strong consumer needs analysis and a great deal of research and testing with many potential food suppliers. It may be obvious to retailers that the price point is not enough, but it remains difficult to be creative enough to find the sweet spot giving a product range its needed added value and competitive edge.
Right now, Target is probably the best retailer when it comes to both being able to offer cheaper prices while having a "’cheap chic’ image and changing the cheap and low-quality perception that store-owned brands have had for many years.” In 2021, the US big-box behemoth accounts for 48 private brands. Ten of them are worth one USD billion dollars.
In the department store business, Le Bon Marché also achieved a significant performance, yet at a very small scale, with its menswear brand Balthazar: while being cheaper than national brands, it’s also recognized for its quality and designs. Through the years and the eyes of the consumers, it even became a ‘true’ brand and is not just considered as a private label anymore.
A 2020 survey by Numerator (a US data and tech company evolving in the market research industry) also shows how decision-making factors in choosing brands are shifting when it comes to price. It is still key, but its importance greatly decreases with ‘modern’ consumers (the price factor drops from 87% for ‘traditional’ buyers to 69% for ‘modern’ buyers), with quality and product claim gaining more importance instead.
Creating loyalty and additional sources of revenue
Good pricing brings loyalty, that’s for sure. In that sense, private labels remain a great way to recruit and retain customers. Very recently, own brands benefited from the unavailability of some products during Covid. According to McKinsey, 40% of customers switching brands will likely continue purchasing the new brand once Covid is over. With products usually being good value for money, the short-term switching behaviour can obviously transform into long-term customer loyalty. Considering customers are more and more unfaithful to brands and retailers, and costs of customer acquisition are sky-rocketing, having a solid and loyal customer base is more crucial than ever.
When it comes to the loyalty factor, Galeries Lafayette is an interesting example. According to company private labels management, they are benefiting from a very strong loyal customer base thanks to their women’s ready-to-wear considered as qualitative, affordable, timeless, colourful and easy to ‘mix and match’ with customer’s wardrobes. The Galeries Lafayette brand relies on recurring customers favouring the store brand over national brands. This great success built itself throughout the years /nbsp]meaning the customer base has now to be rejuvenated.
The loyalty effect is also interesting when it comes to gathering key data about consumers’ shopping habits (demographics, products, price, cross-selling…). It’s even more important in department stores where the concession operating model is widespread, and consequently the relating data is owned by brands. Having a direct relationship with customers that are buying different items and brands, department stores are benefiting from a true competitive advantage when compared to national brands. Not only can the data help private labels to become more appealing to customers, but the richness and depth of this data makes it a great asset to be valued and sold to national brands and partners. Especially at a time when department stores are evolving their business model to find additional sources of revenue.
Loyalty has some limits though. In 2001, Le Bon Marché tried a ‘spin-off’ Balthazar store in Boulogne, a Parisian wealthy suburb where a fair part of the store customers actually live. It wasn’t a success, and it closed a few years later, but the experience remains of some interest as an attempt to try to make a private brand live outside of its native ecosystem.
A tool to differentiate from competitors
Amit Philip, SVP and chief strategy officer at TreeHouse Foods (producing private label packaged foods in the United States), believes that “you can get national brands in any store but retailers establish unique brand and value propositions that are only available in their banners. The more sophisticated retailers even have price tiers within their private brand portfolios. Historically private label was seen as perhaps a cheaper, lower quality option and the standard was to try to match national brands. Today, retailers are looking to exceed national brand standards and create new and higher value propositions.”
El Palacio de Hierro is an example of a department store digging into the unique brand and value proposition as they are developing more and more brands coming with different price points. In ready-to-wear for instance, brands are ranging from the Entry price point with Catamaran (designed for the 17-28 y-o with a EUR 27 average price is), Mid-range with Epsilon (designed for the 30-45 y-o with a EUR 45 average price) to Premium price point with Chester & Peck (designed for the 35-55 y-o with a EUR 93 average price).
Creating such a high-value proposition to differentiate from competitors, and succeed, depends a lot on research and creativity. Among pure players, Asos is a good example when looking at their ‘Asos Curve’ private label. When national brands were still lagging behind in terms of inclusivity, Asos was ahead of its competitors in terms of trends and filled a void on the GenZ fashion market.
Visual identity has also become an asset to the private label business. Monoprix is again a fair example of innovation in that area. The “Monoprix” brand covers basic needs with more than 2,000 products. As there is no excitement in buying eggs or detergent, Monoprix draws attention to such products thanks to a strong brand image using bright colours and an unprecedented factor: the fun. While own brands packaging usually imitate national brand looks, the French retailer uses bold colour-block designs and funny quotes, transforming boring products into eye-catching ones. When this new packaging launched, customers were even talking about the funny jokes found on cans of beans. Such packaging came with an ad campaign that drastically reinforced customer loyalty to the label.
Attracting customers, but also brands
With enhanced private brands, comes new perspectives in terms of advertising. Promoting a price point is replaced by promoting the product itself: its claim, quality, and difference. In that case, private brands can become a great tool to advertise the store image itself, and to leverage social media to reach more customers. Also think about the importance recently taken by the unboxing trend on Instagram: it has been adding new and supplementary visibility for brands and products.
When thinking about private labels, collaborating with other brands is also something to consider to promote the store image itself, gain new customers and create excitement on social media. Once again, Monoprix is succeeding when launching collaborations with designers or brands, this year with edgy fashion designer Vincent Darré or interior designer India Mahdavi. In such cases, direct revenue is not the point as very few products are produced and sold in the end. But they have proven to be a great way to draw customers attention and reinforce the store image.
Post pandemic, even the most endangered retailers are willing to use collaborations as part of their private label strategy. The last example to date comes from bankrupt and relaunched JC Penney partnering with the infamous Juicy Couture brand, also resurrecting from the dead. It’s a smart move though, considering Juicy Couture is still a famous and impactful name able to draw shoppers attention. The brand is considered a pioneer when it comes to athleisure, a trend that is not predicted to end soon.
Ultimately, private labels collaborating with selected brands can become instrumental to attract new customer groups. At a time when some brands are adopting more and more direct-to-consumer business models (as we know it’s the case with major luxury brands, Nike, Adidas…), private labels could be a key part of an attractive product offer, assuming they have developed a great value proposition.
Another option to be considered is to develop new private labels, especially in the fashion area, using a brand licensing model or even by buying brands and relaunching them exclusively under the department store umbrella. Still, caution is in order in that case. Even a powerful retailer like Walmart faced difficulties when acquiring brands. In 2017-18, the retailer bought a bunch of direct-to-consumer ready-to-wear brands. At that time, comments on the buy-out were harsh on social media, customers worrying about Walmart lowering the quality of such brands. In 2019, the retailer even sold one of these brands, bought 2 years earlier.
A way to prove commitment to CSR questions
For many retailers, private labels are now a way to benchmark sustainability progress and prove ‘transparency’ to customers. For instance, Macy's private brand uses the Higg Index Environment Module but also its Facility Social and Labour’s to gauge the environmental and social performance of manufacturing facilities. Audits in factories supplying the private labels are conducted every 18 months. Hudson’s Bay has enforced a Supplier Code of Conduct applying to all vendors producing private labels (based on the United Nations Human Rights Declaration, the Amfori Business Social Compliance Initiative, to name a few).
Nordstrom is also an interesting business case. They reorganised their private labels by reducing them from 40 to 12, but they are growing the business anyway, thanks to an embodiment of the CSR topics. In 2020, 64% of “Nordstrom Made” product volume was produced in factories using the Higg Index Facility Environmental Module. They also tackle body inclusivity questions by appealing to different age groups, communities and body shapes: for instance, they launched Henna and Hijabs x Nordstrom, designed for the modern Muslim woman, and Nordstrom x Christina Martinez to celebrate Latinx heritage.
A department store is a house of brands. Even though they cannot take responsibility for partners' ways of producing, department stores could become accountable, if not already, for having brands considered not sustainable or responsible enough by customers. Developing sustainable private labels is a way for them to have more control over the CSR issues. In that perspective, Magasin du Nord’s main priority is to improve the entire private labels’ value chain to ultimately be able to market its products as honest, authentic and sustainable. In general, IADS members are very ambitious and target 100% of sustainable offer: by 2024 for Galeries Lafayette and Magasin du Nord, and by 2025 for Breuninger and El Corte Inglés (data from IADS Merchandising meeting dedicated to private labels, January 2021).
*In theory, there are many reasons why department stores should continue developing private labels: offering an interesting price point, filling a void on the market, attracting new shoppers, developing loyalty, differentiating from competitors, anticipating potential national brand withdrawals. Own brands are also supposed to increase retailers’ margins. But the situation for department stores’ is contrasted when it comes to profitability as we know some are struggling. And also, are they still really attracting customers, even after some internal reassessments, or changes in organisation and offer? Considering the challenges ahead, IADS members’ CEOs have decided this year’s IADS Academy will be dedicated to the private labels topic.
Furthermore, there is no ‘one size fits all’ when it comes to private labels, which makes it an even more challenging business. IADS members are not following the same trend in terms of development. For instance, El Palacio de Hierro tries to multiply the number of its own brands (having a different name for each of them), while others like El Corte Inglés or Magasin du Nord reduced the number of brands.
In any case, this part of the business remains a challenge as consumers’ expectations won’t lower. On top of that, private brands have to find their way online. Creativity, research, imagination will surely be key to meeting all expectations. A unique value proposition based on sustainability seems to be the best tool available right now.*
Credits: IADS (Christine Montard)
IADS Exclusive - The anatomy of a department store - Organisation structures under the microscope
IADS Exclusive - The anatomy of a department store - Organisation structures under the microscope
Organisation charts, while not a perfect picture of how companies operate, nevertheless provide some insights into how companies are shifting over time, how they are dealing with complexity, and also how companies differ in their perspectives and priorities. A sample of IADS members have shared organisation charts prompting some thoughts about department store structures.
Organisation charts: a reflection of complexity
Organisation charts are not an exact reflection of how companies work. Many business writers, sociologists and anthropologists have commented on what is missed by these charts such as the nature of the flow between the function boxes, pain points, and, perhaps most importantly, the reality of the roles and responsibilities as they are exercised in day-to-day business.
However, they still provide some insight into a company’s perception of itself, of formal internal power structures and rewards, and they allow comparisons to be made between companies at one moment in time as well as to visualise changes in companies over time.
The IADS has collected some members’ current org charts and has been able to draw some conclusions. We have also found charts dating back 5 years which highlight some major, sometimes surprising, changes over that period. What is clear above all is that organisation charts of department stores reflect the complexity of the business. Buying departments manage many different types of contracts with merchandise suppliers. The suppliers are constantly changing. The types of contracts are continuously being renegotiated. The Retail department is dealing in store with own staff, brands staff, demonstrators, part-time, seasonal, as well as with space rental, payments and security. The fact that many department store companies have been in existence for over 150 years means that almost all have accumulated layers of history piled upon each other, often not well adapted to current circumstances.
The C-team
A number of functions headed by a C-level leader answering directly to the CEO can be found in most of our sample of department stores and form the skeleton:
- Finance and Administration including accounting, controlling, planning, and often legal and procurement, which has recently had to deal with cash flow problems among other pandemic-related issues
- Buying and Merchandising covering the assortment from fashion to food with widely fluctuating sales patterns over the last 18 months
- Retail Sales or Operations in charge of the stores, facing questions of traffic, selling space and customer service and experience
- Marketing which is shifting at present and involves communication and media as well as customer data and experience
- Supply Chain and Logistics under the spotlight at the moment since it has had to deal with disruption at the same time as a reorientation of inventory and fulfilment issues
- IT covering company-wide tech architecture as well as payments, security and other systems serving the company, and which has been at the centre of considerable investment decisions and controversies
- HR playing several roles: an administrative one as well as a strategic one, a centralised one as well as a dispersed one around regions or stores, and which has also had to deal with staffing, costs and remote work in the pandemic
- Digital has now moved into a full functional role in its own right and more often than not has a seat on the management board, and covers at least ecommerce, omnichannel, marketplace and often more. Its leader is sometimes described as Chief Customer Officer
- Strategy, Transformation or Innovation has emerged in several companies as the seat of future orientation. In the 1930s, the IADS promoted the creation of “Research” departments in its members which would most closely approximate this function.
- Real Estate covers store planning, construction, maintenance, architecture and works, and development. It is more important if the company owns property, and is currently dealing in some cases with closing stores, and in other cases with designing and opening new ones.
Most but not all of these functional leaders will have a seat on the management board.
It should be noted that in some cases, strategy alone may not be the sole reason for the content or the importance of a function. Strong personalities may convincingly argue that different functions should be included under their remit. History also plays a significant role in how a company is structured at any one time.
Adaptive changes 5 years on
Probably the most striking shift over the last 5 years has been the emergence of ecommerce which has now resulted in a separate “digital” function in most companies. While 5 years ago, ecommerce would have been subsumed under another function, it has now almost universally acquired its own responsibilities and status. It may have moved out of Marketing (Manor), Finance (Palacio), Merchandising (Breuninger and Globus), or Distance Retailing if the company had an already existing mail order business (Stockmann).
As the newest department store function, it often brings together people with rare technical skills, and with considerable experience in different parts of business management, especially if they come from start-ups. Furthermore, the current “digital” departments often started as small projects which were only later integrated into the company.
Similarly, IT has emerged as a much more important and independent function servicing most areas of the business after being hidden within the Finance function in most cases (Galeries Lafayette, Palacio, Breuninger).
Several years ago, the Merchandising department in some companies decided to separate the buyers’ role from planning, resulting in the so-called “buyer-planner” organisation model (BPO). While this was adopted in several companies, some (such as Globus) decided later to reverse the decision and to return the planning function to buying.
Another company which grouped Purchasing, Operations (stores and logistics) and Marketing under one single Commercial department leader reporting to the CEO, has now pulled out the main merchandise categories as separate functions reporting directly to the CEO. One company appears to have done the exact opposite, moving from individual merchandise categories reporting directly to the CEO, towards a model with a merchandising leader covering all the merchandise categories (as well as marketing).
A company which had Supply Chain and Logistics reporting to Finance and Organisation, has now created a separate Supply Chain entity reporting to the CEO, although not part of the Executive Committee.
If a trend were to be identified over the last five years, it would probably be towards a somewhat less hierarchical structure as companies have had to deal with an increasing level of specialised skills. While there are exceptions to this, in general CEOs have had less of a buffer between themselves and specialist units in their structure, with whom there will have been in more direct communication. However, multiple divisions or functions within any organisation puts a premium on communication between them. Whether that is taking place is something an org chart will not reveal.
Various morphologies
While the skeleton remains more or less recognisable over time, the morphologies of department stores shift. The current shape of the department store can be described along several dimensions which characterise their functions.
The most centralised: In spite of recent changes brought about by ecommerce, some functions still benefit importantly from economies of scale. These are Finance & Administration, IT and Supply Chain/Logistics. These are functions which serve the whole organisation and which lose efficiency when fragmented. It is also these functions which are most likely to be outsourced. IT and Supply Chain also require large investments which need to be amortised across the company. While important to the future of retail, IT does not always get its own seat on the board as it is seen as a service to other departments and can be subsumed under Digital or Innovation for example (Palacio). However, IT is often the flattest organisation as it is the one where the most “agile” structure is operated.
The most dispersed: While Human Resources still has an important central function, many of the activities of HR are now performed locally in order to adapt to the specific needs of stores, regions, countries, or sometimes skills. Recently, perhaps because of its dispersed nature, HR has taken on the role of sustainability guardian (Galeries Lafayette, Manor).
The most confident: Merchandising and Retail Operations are still at the core of traditional retail activity (buying and selling). Members of each of these functions see themselves as key to the whole business, they produce the revenue and are part of what Geoffrey Moore has called the “productivity zone”. This aura of unassailability partly explains why there can be big variations among retailers in how they are organised: a buyer is a buyer no matter where they are placed in the chart. We also often hear about “natural selling skills”. However, this certainty applies less to the food category which is why it is almost always separated from the mainstream buying department.
In some companies, it has been deemed appropriate to include buying (as well as some other functions) under a flagship store division when it is felt that the flagship is unique (Food under Galeries Lafayette Haussmann, or Home under BHV/Marais). Companies might also choose to treat Outlets differently.
The merchandising department is of course only necessary in a wholy or partly wholesale model. Businesses that lease space will operate instead through a Leasing department operating alongside a Sales department (Sogo).
Visual merchandising can be seen as belonging in Retail Operations (Manor) or in Merchandising (Beco). The Merchandising department of Manor is unusual in that it includes also Marketing.
The most connected: The relatively recent Digital department is the one with the most direct impact on other areas of the company since it involves not only ecommerce and web design but also omnichannel relations with the traditional physical company, the marketplace (increasingly popular), customer experience and data, and even CRM and loyalty card (Breuninger). This department is often headed by a designated “Chief Customer Officer” which puts them in charge of some of the traditional marketing functions. In one, a “Chief Innovation Officer” will head IT, ecommerce, and logistics (Palacio).
The most contested: The Marketing department has been undergoing a revolution for some time. Indeed, an increasing part of its budget is getting redirected to online and social media. A part of its activity concerned with customer knowledge and data has now become so technical that it is better handled by a new breed of marketeers, data scientists and techies. In fact, the responsibilities of the traditional marketing department have sometimes been transferred to a Chief Customer Officer heading a digital department (described above). In one case, Marketing is the responsibility of the Chief Merchandising Officer (Manor); in another, the two are also combined but only at corporate level (Falabella).
The most autonomous: A small number of companies have instituted Strategy or Transformation departments devoted to strategic planning and projects. This area is probably the closest to one of the original goals of the IADS looking to the future on behalf of member companies. Such departments have the ear of the CEO and impact the company as a whole only when projects become reality or when they enter the “transformation zone” draining investment from other areas.
The IADS includes several members with international operations. These are often structured separately, especially if they are a mixture of owned, partly owned or franchised businesses. One member with a fully owned and operated international network is Falabella with department stores in three countries. This implies a “matrix” structure with a country head in charge of national operations as well as a divisional function head in charge of a function across all countries.
Unsurprisingly, structures become more complex with time. The youngest IADS member company founded in 2003 has adopted a structure with two joint Executive Directors overseeing 15 or so separate functions including Advertising separate from Marketing, Ecommerce separate from IT, Administration separate from Finance (Sogo HK).
Does structure follow strategy?
It is clear that, although the department store sample shows many common points in terms of basic organisation structures, there are also significant differences between companies which sometimes may point to different directions for the future. Organisation charts are not stable, and respond to strategic objectives, environmental and market conditions, technological changes and customer expectations, as well as to individual talents within the organisation.
Three key questions:
- How to achieve digital transformation?
There appears to be a trend towards a separate Digital department headed by a Chief Customer Officer. As well as the expected responsibilities related to ecommerce and the website, this role also includes omnichannel and therefore needs to play a strong cross-functional role. Is a separate department the best way to achieve this? While it underlines the importance of digital by putting the CCO on the Executive Committee, it does not guarantee that digital initiatives will be distributed across the organisation.
- Are we serious about sustainability?
In companies where sustainability is mentioned in the organisation charts, it is tucked away in the HR department. This might be the right move given that sustainability and CSR need to run across responsibilities such as merchandise, selling, relations with suppliers, maintenance and construction etc. and HR as we have seen is the most dispersed department. However, this is an area that has become highly specialised, which might well be coordinated through HR, but which requires very specific technical skills to achieve credibility with increasingly critical customers and pressure groups.
- What is special about flagships, outlets and food?
The answer is that these are three areas which do not fit comfortably within the standard skeleton structure outlined above.
Flagships sometimes have a distinct customer base such as tourists, which means they have to adapt their assortment, marketing, and indeed elements of the business model. At the same time, they carry a large proportion of the brand value of the company.
Outlets used to serve only as temporary channels to evacuate surplus merchandise. They have become a format in their own right, sometimes with their own website, and growing fast. They no longer sell only discounted stock but also include specially purchased goods. They operate on a slightly different business model.
Food has traditionally been recognised as a separate business from fashion or home and therefore featured in a special place in the organisation charts. Today, food is increasingly linked to wellness, to gifting, to luxury, and to consumption in many parts of the store. Should it be reassessed?
Conclusion: dealing with complexity
It would probably be a mistake to attach too much importance to companies’ organisation charts. Nevertheless, many uncertainties, hesitations and vacillations are revealed through an examination of these charts, and these may reveal present and future pain points. As BCG has pointed out, companies (and department stores in particular) need today more than ever to respond to the complexity of contradictory demands:
- Speed and reliability
- Innovation and efficiency
- Standardisation and customisation
- Global consistency and local reactivity
The answer has tended to be a proliferation of structures, responding to complexity by complicatedness. The confusion apparent in department store organisation charts comes from the complicated response to the complexity of the operation. In this sense an examination of organisation charts acts as an indicator (in the chemistry sense) of deeper problems or shifts which are probably as yet still unresolved.
Cross-functional activity, or the lack of it, is one such revelation. The different solutions to problems adopted by different companies is another which signal that companies are probably in transition mode. This is clearly the case with Digital and Marketing. We foresee that a high degree of uncertainty will be touching the Selling/Retail Operations area in the near future.
Credits: IADS (Dr Christopher Knee)
IADS Exclusive - Designing a relevant customer experience: A talk with Héroïne
IADS Exclusive - Designing a relevant customer experience: A talk with Héroïne
*Héroïne is a retail design agency dedicated to Client Experience. Thanks to their ROX™ method, they are able to program in-store experiences and develop unique design concepts. The company works with different industries, such as cosmetics, food, fashion, telephony...
The company created some of Clarins' Experience Ceremonies to support their strategic launches through their retail network in different key markets. They also collaborated with Armani for experiential pop-up stores, and with French jeweller Fred on their new retail experience. Héroïne also works with companies such as Estée Lauder, Orange, L’Oréal, Rémy Martin.
Héroïne was founded 2 years ago (3 months before Covid), with the strong belief that physical retail is not dead but has to reinvent itself through customer experience. While this trend is on every retailer’s lip, we tried to better understand how to make it work. To that end, Héroïne’s founders Rémi Le Druillenec (CEO) and Quentin Obadia (Creative Director and Strategist) have answered IADS’ questions.*
Good customer experience
IADS - How do you define good customer experience in 2021? What do you think is missing? Do you see a gap between customer’s expectations and what brands and retailers offer as a whole?
Héroïne - When it comes to defining good customer experience, the answer is simple and complex at the same time. Good experience should of course match with what customers are expecting from a store visit. It looks simple, but it implies that brands and retailers, not only know their customers’ expectations in terms of product, price point…, but also in terms of experience. As it’s relatively new, this is the complex part. And it’s a preliminary phase, before even starting to shape the customer experience.
There is sometimes a gap between retailers and customers’ expectations. Retailers want to develop experiences in order to directly sell their products or their services. But from a customer point of view, the experience is not necessarily about directly buying something, but more about discovery, feelings and emotions. Of course, at the end of the day retailers’ purpose is to sell. However, it’s important to help them change their mindset to become even more customer-centric, which is the very purpose of the customer experience.
If we think about stores (and especially flagship stores), they were designed as temples using a ‘top-down’ approach for many years. As a result, they have sometimes transformed into “brand ego trips”, in a way separating the brand from its customers. There is a lot of work to be done here. After Covid, brands and retailers are more and more aware that they have to really understand their clients, which differs whether they are in Paris, or in French secondary cities, in China or in the United States. Brands now try to adapt their stores and their offer, in a more ‘down-to-top’ way.
Engage with GenZ
IADS - What do you think are GenZ's expectations in terms of customer experience?
Héroïne - As the first generation to be born and raised with smartphones, they discovered the world through internet. It means that digital has to be fully integrated in every step of the customer journey. It still happens that we meet with brands showing us their ‘experience zone’ consisting of a big screen or an iPad! The experience should both live through smartphones and in store. Most of all, such customers are expecting a full integration of the real life into the virtual life, the real life being augmented by the virtual life. In that perspective, all the digital assets should offer the possibility to continue the experience after the in-store visit, to ultimately lead to a purchase.
It’s even more difficult to track GenZ customers as they might not buy in store, physical retail being just a touch point among others. They might come in store, share pictures with friends first, then on social media, etc…, and eventually buy online…, or go back in store. In such circumstances, we not only have to measure the quality and efficiency of the experience, but also track how this experience influenced the purchase.
Develop and measure customer experience
IADS - How should a retailer proceed if they want to transform selling spaces into experiential spaces? What method are you using?
Héroïne - The method we use is based on the evaluation of 5 pillars, which are reflecting what a store is made of:
- The Immersion: it covers all that is linked to the DNA of the brand including store concept, retail design.
- The Usage: how the brand helps customers understand what's inside the store, the customer flow, where they can find everything. It includes signage and also tools helping customers try products.
- The Services: they are both transactional (alteration, delivery, payment…) and relational (interactions with sales associates, small gifting…).
- The Proof: retail is the place for the proof as you can see and try products.
- The Sharing: the store becomes a media and facilitates the experience sharing, from good lighting for Instagram posts to challenges to engage with communities.
Once the evaluation is done, we can then work on 3 to 7 personas which are the results of our observations through the pillars, analysis of the environment, interviews of sales associates, ethnologic studies…). Such personas are adapted to each store’s specific needs. Then we build the experience which has to be seamless and not overlooked as “plugged” into the store.
IADS - You’re using a new KPI to measure results: the ROX (Return On eXperience)? How does it work? Is it easily adopted by retail organisations, or do you see resistance? How do you overcome that?
Héroïne - Once the customer experience is on, we will evaluate each pillar again to know the ROX. There are ways to overcome retailers’ resistance. For instance, when it comes to the Sharing pillar, we will measure the hashtag success on Instagram, showing the success of the experience, if it’s easily sharable and if the store is becoming a media. For the Usage pillar, we will for instance observe and measure the “breaking of flow” corresponding to the moments when the sales associate leaves the customer alone. The audit can also be done on a regular basis to measure evolution.
The results we see are different from one brand to another. They share a common trend though: the sustainability question, which is relating to the Proof pillar and have to become part of each customer experience. The Service pillar, as it involves individuals, usually raises questions. The store staff needs training especially given they are more and more having to multitask. As the Service pillar involves the intervention of different departments from marketing to sales, it sometimes reflects issues in the brand organisation, such as for companies organised in silos.
IADS - Services are more and more mixing with experience: how do you articulate both?
Héroïne - Services, as they are an extension of the Proof, are important to create long-term in-store relationships that can also be measured (think about product repair). Services also demonstrate how the brand speaks to customers, besides just selling products. In that regard, Rimowa New York’s experiential store featuring a passport picture service, is a great example as it elevates the brand from luggage selling to a travel experience.
IADS - The customer journey now accounts for 6 touchpoints (instead on 2 touchpoints 15 years ago): what is the role of the customer experience here and how do you use data?
Héroïne - Like glue, experience brings consistency to all these touchpoints, links them together (ad campaign, digital, brick & mortar…) and pushes customers to engage with the brand.
Since many brands don’t have data (or they have data but don’t know how to use it), store staff remains a great source of information, especially to really know who the actual customers are.
Current trends
IADS - In your book ‘Le Magasin est-il mort’ (translating to ‘Is the Store dead?’) coming out today (13 October 2021), you identify 5 innovation trends : What are they? What has Covid changed forever? Please share from the customer point of view and from the brand/retailer point of view.
Héroïne - The 5 trends we identified that existed before Covid, but the crisis has also emphasized:
- Social retail: social media defining new journeys and touchpoints in store.
- Conscious retail: more sustainability is key, especially in-store.
- Humanized retail: the need to connect with people is more important than ever. How to reach clients with mobile stores rather than opening huge flagship stores which have been the answer to retailers’ questions for many years.
- Automatized retail: access 24/7 to products in a fast way.
- Virtual retail: how to create a virtual store offering a specific experience and not just replicating a brick & mortar store.
We are convinced about the future of retail, that’s what we wanted to demonstrate in the book as well as showing how we work. But knowing we can do almost everything from our couch, a trip to any store should be worth it and most of all, a place where people can connect and live experiences.
Contact: Rémi Le Druillenec
+33 6 11 38 40 49
Credits: IADS (Christine Montard)
IADS Exclusive - RFID attempts a comeback in retail
IADS Exclusive - RFID attempts a comeback in retail
There is so much more to come from RFID technology than we have experienced so far in the past few years. The technology and its implications have transformed rapidly, leading to more interesting use cases for the retail format. Unfortunately, the implementation of RFID can take a lot of time and money. So how can retailers make the most of it? Once implemented, what potential does RFID have for retailers and where can it lead?
What is RFID and how does it work?
Radio Frequency Identification (RFID) technology is a form of wireless communication, using radio waves to identify objects remotely. All RFID objects have their own unique tags for identification, and allow objects to communicate with each other through wavelengths.
To use the technology in stores and in warehouses, retailers will need both an RFID tag, which is usually embedded into the product or on price tags, as well as an RFID reader. Unlike traditional inventory tracking systems that require employees to “point and shoot” the item identifier, RFID readers can capture the information from a broader range, thus saving time when gathering inventory information.
The information captured from RFID readers can then be used to get an overview of the entire operations of the business, enabling companies to make informed decisions about their supply chain in real-time. Following the pandemic, RFID is being considered as an asset again as it can help solve a lot of the various logistics and inventory management issues that have arised throughout pressure tested supply chains.
A comeback for RFID in retail
RFID first became popular in 2003 when Walmart announced that all of its suppliers needed to have their pallets tagged with RFID in under two years. This forced adoption from the major retailer ended up leading to RFID’s demise when the project resulted in the realization that the costs, at the time, outweighed the benefits; and the project was deemed a failure in the retail industry.
According to IDTechEx, in 2019 only 10% of the addressable apparel market has RFID tags. But as omnichannel services increase use cases across retail, RFID has been given another fighting chance to prove its worth in the retail market. RFID technology links physical and digital stores, allowing a mostly accurate picture of where inventory is at any given moment.
In Mango’s new Barcelona flagship, the retailer can harness the technology to know where garments are at all times, whether that be in the dressing room or if they have left the store, allowing associates to make sure that items are available. But that use case is only the beginning, having RFID trackers attached to products and having readers placed throughout the store can also monitor and improve sales by informing retailers of their “hot” and “cold” zones of the stores that lead to the most and least sales. By understanding the store flow and the placement of products, retailers can create a unique customer journey based on what and where products are being sold.
As retailers spend more time and investment in RFID technology and its implementation, they are also trying to expand its use cases to be able to achieve the best ROI possible. RFID can be coupled with endless other technologies, such as the Internet of Things (physical devices that are embedded with technology and can be connected), to be able to offer more unique experiences to customers. According to Accenture, information captured from RFID technology can be used in collaboration with blockchain, supply chain analytics, self checkout, supporting omnichannel fulfillment, reducing stock outs, improving customer engagement with smart technology, and inventory tracking and visibility.
It will take time….
As RFID can offer real-time accuracy of almost 100%, the technology can be leveraged to improve customer experience associated with omnichannel services. The technology allows retailers to know where their stock is at any given moment, which also allows them to guarantee availability across all channels, whether that be in-store or online. The information can also be used to understand where products are located to reduce shipping costs, split shipments, and delivery times. Understanding the location of products empowers in-store pickup options. Levi’s, for example, reported 98% inventory accuracy in stores where RFID is fully operational with inventory counts only taking 20 minutes to conduct. This allows for multiple checks per day, making the real-time data more accurate and strengthens the omnichannel. Having accurate inventory visibility is a revenue factor as well as a customer service factor.
RFID tags and readers allow retailers to understand where their inventory is at all times, whether that is in the dressing room, on the wrong shelf, or in a warehouse. Some retailers like Ralph-Lauren, Rebecca Minkoff, and Puma have used the technology to install smart mirrors in dressing rooms that bring up product information and suggest other clothing items that are similar in style to the ones that the customer chose. This creates a personalized shopping experience while empowering the consumer with all the necessary information to make the best decision based on their wants and needs.
An RFID success story: the Prada example
Prada has gone all in with RFID implementation with 100% of products containing a microchip. This allows Prada to enable connectivity with consumers, not only in stores, but also throughout the life of the products. Embedded RFID brings more transparency to the overall lifecycle of the product, with information that can be used privately by the retailer and information that can be shared publicly with customers. For example, retailers can see when an item was received in a warehouse and the time it took for it to get to a store, and customers can gain visibility about how and where their specific product was made. Prada has even created an app where customers can scan the chips to access images and videos of their specific item moving through the supply chain and get to know the people that help create their goods.
RFID’s shortfalls and substitutions
RFID has the potential to be extremely useful, but implementing it can be time consuming and costly. There are equipment costs, installation costs, tag costs, software costs, ongoing license costs, maintenance costs, and integrator costs (if you use a third-party expert). This might be the reason why Rebecca Minkoff’s store stopped using smart mirrors, the cost of maintaining the service might have outweighed the benefits. And technology does not come without its hiccups. RFID is prone to two main issues: reader collision, when a signal from one RFID reader interferes with another, or tag collision, when there are too many tags and an RFID reader is overwhelmed with too many data transmissions.
One of the major shortfalls of RFID is that it is physical, and now there are a lot more advanced technologies that can cut out the pains associated with implementing hardware into each individual product. For example, computer vision might be a major competition for RFID. The Amazon Go convenience store that allows customers to pick up products and walk out of the store and be charged automatically without using a cash register was rumored to originally use RFID for its touchless checkout tech. But now the retailer uses a mix of RFID and computer vision, and is applying similar technology used in autonomous driving to retail. These technologies allow the inventory management system to identify the customer (via facial recognition, user ID, GPS, or through an app) and recognize which products are in their possession with the help of cameras, sensors, and microphones.
While RFIDs implications are very interesting, the cost and time it takes to implement every single tag into individualized products might make autonomous technologies more enticing for retailers. But even newer technologies like NFTs used by the Aura Blockchain Consortium can be combined with RFID tech to attach information to products, helping anti-counterfeit and loss prevention efforts. This makes the RFID initial investment even more so attractive.
A fully transparent supply chain
The greatest struggles and roadblocks of RFID are quantifying its cost, identifying the right suppliers and partners, and having the ability to train employees. It takes a long time to pilot and implement, but with the right use case, the benefits will pay off in the long run. Once retailers decide to invest, they will need to push through the difficult change management stage to realize the potential and very beneficial ROIs associated with the technology. A successful transformation will require the whole organization’s cooperation.
When it comes to gaining visibility on supply chain operations overall, software companies like Avery Dennison, Kinaxis, E2Open, OracleEPM, and Anaplan offer added insight to inventory management and should also be considered, no matter where you get your data from, to reduce risks and cut costs. These tools can optimize the supply chain and add an extra layer of visibility through what-if simulations from RFID data, giving retailers the control and foresight when unexpected circumstances, like a global pandemic, may arise.
Whether RFID is right for your organization or not will need to be determined for each individual use case, understanding the time and costs that are associated with a calculated ROI. For organizations that have already invested, it could be an exciting time to couple the data output with new software and services to gain more from your initial investment. For organizations that have not yet invested but are considering such a solution, it might be wise to evaluate other emerging innovations as well to ensure the right fit for your strategy and needs.
Credits: IADS (Mary Jane Shea)
IADS Exclusive - Work reassessment: how to make retail attractive again?
IADS Exclusive - Work reassessment: how to make retail attractive again?
In America and Europe, retail is a major employer, especially for women and young people. Retailers are the largest private-sector employers in America with 32 million workers, and a staggering 2.4 million retail jobs were lost in March and April 2020. In Europe, about one in six workers have retail or wholesale jobs. Whereas they have never been easy, with low wages, permanent pressure over turnover, chronic understaffing, no weekends…, retail jobs have become risky positions pushing workers further away from stores.
At the same time, such jobs have drastically changed, and not in a good way according to the staff fleeing from stores. In a survey done by RWRC (a marketing agency working exclusively in retail) in December 2020, 75% of the 500 British store associates involved think that their job became more complex since Covid. In the United States, a recent survey by retail operation platform Zipline says 42% of retail workers are either considering or planning to leave retail post-pandemic. Some moved to distribution centres, but this is not a solid option especially given warehouses are far from cities, and jobs are more physically demanding which might not be suitable for women.
At this point of the year in 2021, retailers are facing a real staff shortage putting at risk a much-anticipated business rebound. Government support plans and the fear of catching Covid while working may be of some influence on the current state of labour. Also contributing to the transformation of retail staff becoming a rare breed in the United States, fashion retailers are hiring sales associates at a rapid pace unseen in the last decade. But that doesn’t explain the whole labour issue. What’s happening to retail staff? What should be done to make retail attractive again?
The retail days of yore are over
Not long ago, if you were a sales associate, your responsibility was to sell stuff in store, period. Those were simpler times. Nowadays, and with Covid putting more pressure on business and more expectations on retail staff, anxiety has increased while responsibilities were dramatically shifting, and higher flexibility was required to adapt to unprecedented conditions.
It has become an understatement to say that retail is not only about selling things anymore, and so are retail jobs with store staff transforming to multitasking employees. Now they have to be able to sell both physically and distantly, prepare and ship orders, organise kerbside pickups, become tech-savvy, be brand ambassadors through social media (or “mini-marketers” as Marc Metrick recently said about Saks sales associates), provide experiences to customers, and learn wider and wider marketplace product catalogues. Worse, retailers being in a very difficult position, an additional compensation is not always part of the equation. And in the end, due to Covid closures and massive digitalisation, jobs are truly at risk and sales commissions are vanishing. To a certain extent, sales associates find themselves stuck between fighting to increase the company’s turnover (as well as their own revenue) and defending their sales commissions against the online business, accused of taking away sales that associates judge to be theirs.
Overcoming resistance to digital…
Changes are massive and not everyone wants to (or can) adjust to such transformations. Facing online competition, brick-and-mortar retailers, along with their staff, have to adapt. The crucial and human relationship between sales associates and key customers is becoming digital. Even though they were used to texting their clients, store staff had to adopt additional tools such as WhatsApp, Instagram and WeChat.
Now retailers, especially in the fashion area, are adding clienteling software on top of existing tools. For instance, Neiman Marcus acquired Stylyze, a software making outfit recommendations based on what customers have looked at or purchased. That’s great, but such a tool heavily relies on data and less on sales associate skills, which might be demeaning for some. Anyway, two months after the technology was rolled out and integrated into NM Connect (the digital software staff uses to communicate with customers), it resulted in USD 60 million in incremental sales. In order to handle relational shopping operations, Magasin du Nord also successfully launched a digital communication solution with Clientela.
… And rethinking incentives
The first thing coming to mind when thinking about attracting employees is money. While retail jobs are often low paid, it is a long process to increase salaries mostly because there is no turning back. Walmart and Target entered such a process before Covid. With the pandemic, Target doubled down on its investment in the workforce by giving out bonuses six times in a row since April 2020. Last May, sportswear brand Under Armour did the same by increasing its minimum wage in the United States from USD 10 an hour to USD 15, hoping to fill some 3,000 available positions in stores and warehouses. Kohl’s also recently rewarded loyalty by giving USD 100 to USD 400 bonuses for store and distribution centre employees staying on long-term. Some American retailers also offered immediate sign-on bonuses.
As increasing wages is becoming a broader trend, retailers also have to adjust their commission schemes if they want to overcome resistance to e-commerce and make digitalisation a success. Fighting resistance is crucial and sales associates have to embrace digitalisation as part of their job. In regards to such evolution, El Corte Inglés has set a successful policy to involve store staff and make its 2-hour delivery really work. During the IADS Merchandising Meeting dedicated to Cosmetics & Beauty, they explained that orders, placed online, are prepared in-store, and employees preparing them receive a bonus while commissions on sales are assigned to the store.
During the 2021 third IADS CEO Quarterly Exchange, Fnac-Darty CEO Enrique Martinez explained the store’s incentive strategy. E-commerce was considered as the enemy among store staff. But thanks to a new scheme integrating digital sales, store associates are now seeing them as a financial opportunity. With incentives on sales usually representing 10% to 15% of their pay check, sales associates are now benefiting from the same incentives as soon as the store is involved in some way in the selling process, whether it’s the inventory, the delivery or the salesclerk being part of the operation. One question remains though: should sales happening 100% online be integrated into the store metrics? For sure, such integration would reinforce staff loyalty.
Reinventing working conditions
But money is not the only way. Improving working conditions can be of some help. Even though working from home has not been a picnic, it has allowed many people to keep their job through the pandemic and onward. As the world is expecting other major disruptions in the future, retail jobs will be impacted again, and this is not very enticing. Even though some people benefited from government or company support, what they really want is a steady job and not feeling at risk about their position. This is raising the question of how retail working conditions could evolve to both be able to manage disruption and retain employees. Since everything is digitalising, including sales, some retail staff could work from home, offering them both more security in their job and possibly better working conditions at a time when some stores very existence is questioned.
Madison Reed, an American hair salon chain, paved the way in that sense. When salons had to shut down last year, the company decided to keep its 100 hair colourists and to launch online ‘colour parties’ where they would act as virtual consultants helping women colouring their hair at home. It was a huge success in terms of revenue but also in terms of employee loyalty. A year later, and even with salons reopening, the party is still going on and it seems it’s a permanent change for the company workers. Eighteen new colourists have been hired since then to meet the increasing demand.
Another example is coming from Apple. Called “Retail Flex”, a bunch of retail employees will test a hybrid in-store and at-home working model for 6 months. These workers will deal with online sales, customer service and technical support, moving between their store and their home depending on where the customers demand is. Paychecks will be the same whether working in-store or from home, and internet expenses, as well as office equipment, will be partially supported by Apple.
Training and promoting
The rapidly changing retail ecosystem is requiring additional skills that sales associates don’t necessarily have. So, they need to be trained to feel comfortable and efficient doing their job. While younger workers might need more knowledge about products and selling technics, seasoned sales associates (who are usually taking care of the top customers) might need a little help on the technology side. But in any case, training is a tricky question for retailers. Considered more an expense than an investment, they are often reluctant to spend money on expensive and questionable training programmes. Especially on retail staff whose turnover rate is usually high: in the United States alone, the annual turnover rate among part-time store employees was 76% in 2019, according to Korn Ferry.
Obviously, training on product knowledge is highly necessary as a lack of it is repellent to customers. Employees at Trader Joe’s supermarkets, for example, are expected to taste products. It prevents them from boredom and most importantly, they can answer questions about what they sell. This kind of effort contributes to why Trader Joe’s is in the top 5% of similar-sized companies for employee retention, according to Comparably, which rates company cultures. Another example is coming from Sephora where the training programme includes tailored development plans, a “Daily Dose” of training, and free classes at Sephora University.
“The retail workforce is almost more important than in pre-pandemic days,” said Ron Thurston, vice president of stores at Intermix. “These are the people with the most knowledge of your brand, the customers and product feedback.” Despite such enthusiasm, it’s a well-known fact that retail employees are rarely considered to climb the company ladder and have access to better positions. Thurston adds: “At Intermix, every employee sits down with a manager on a quarterly basis to discuss career goals, create individual development plans, and share any open headquarter roles that may be available.” If really enforced, such HR policy can allow companies to develop employee knowledge and perspectives, really identify people with strong potential and ultimately increase loyalty.
Enforcing creative measures
Knowing a part of the retail staff has switched to other jobs during the pandemic, there are additional measures that can be taken to attract workers back. For instance, Vashi, a British jewellery company, decided to offer perks to store employees: they are entitled to a pension plan, 29 days of annual leave, free gym membership, life insurance, access to an online physician and prescription service and a mental health counsel. Such measures come at a price but who wouldn’t join? Kohl’s, when recently hoping to hire 5,000 associates, made publicity about some competitive edges such as flexible schedules, and an immediate 15% Kohl’s associate discount.
To be in step with younger employees, retailers are being innovative in areas some wouldn’t think of. Korean department store Hyundai has completely revamped its reporting system to better collaborate with Millennial and GenZ staff. Accounting for 80% of its workforce, their habits and expectations had to be taken into consideration by lifting bureaucracy burden as well as simplifying and digitalising reporting tools. Employees are now simply sending notes through a messenger app.
***
Covid pushed retail workers to reflect on the meaning of their jobs. While communication between each level was off, or in jeopardy during lockdowns, deep questions probably arose such as engagement versus wages, work direction, career opportunities, and empowerment. Such topics are usually missing in the normal work routine, and with Covid, some jobs lost their meaning and value to the very eyes of the ones involved. Besides improving pay checks or working conditions, companies should add significance and direction to the retail they are rebuilding. More and more people want to be proud of the place they are working in and feel they are part of something exciting and bigger than them. As they picture themselves as part of a community in their daily lives, they want to relate to a company culture. Will retail be up to it?
Credits: IADS (Christine Montard)
IADS Exclusive - Rethinking the retail supply chain
IADS Exclusive - Rethinking the retail supply chain
Several aspects of retail supply chains have been revisited during the Covid pandemic. Retailers have been dealing with the crisis using different fulfilment strategies which integrate online and physical stores more than ever. Some of these will probably last into the future, or at least have an impact on future retail models. Many of these new ways to serve customers are in fact supply chain questions which are becoming an increasingly important part of the retail business.
Fulfilment from stores: an additional role for the store
In the US, Target had been developing a “click-and-mortar” model well before the pandemic hit. It was fulfilling orders from stores, in part thanks to its acquisition of Shipt in 2017. This company provided on-demand grocery delivery allowing customers to shop online and have their orders delivered from their local stores. Target now offers delivery to home from as little as one hour by using their 1900 stores. In the second quarter of 2020, Target e-commerce sales doubled compared to the previous year, and 80% of e-commerce orders are now fulfilled from stores. Most importantly, the average unit fulfilment cost has been cut by 30%. Same day pick-up and drive-up options which don’t require packaging and delivery are now Target’s most profitable fulfilment options.
However, fulfilment from operating stores may require using store personnel which is also more expensive than warehouse staff (especially given the recent minimum wage increases announced by some of the large retailers) and, in the long run, than a robotic warehouse picking system. Even if these issues can be solved, the problem remains of what a large-scale fulfilment operation from an working store would do to the stock and indeed the attractivity of that store. And delivery services require a lot of space. As previously noted, SM in the Philippines has been integrating a “call to deliver” system in its stores which accounts for over 15% of sales.
The trick here is to use data-driven inventory allocation to compensate. A central warehouse able to sort items into packages intended for particular store aisles, allowing store staff to unpack directly onto the fixture, bypasses the backroom of the store. Deliveries to stores may be sorted in trucks so that unpacking follows a predetermined order.
Dark stores: a micro-DC close to customers
However, “classical” online sales requiring a box, a shipping label and a carrier pickup are also growing, and this type of operation uses a lot more space than the same-day options. To overcome the limitations of using operating stores for online orders, some retailers have been looking at abandoned sites in malls to use for order fulfilment. Others have been converting their own stores to “micro-distribution centres”. Indeed, these sites labelled “dark stores” are often better situated closer to customers than the traditional warehouse or DC operations.
The design of such buildings, often with several floors is not necessarily suited to high density deliveries. Although parking is sometimes available, at least for sites in malls, there is only one entry for incoming goods rather than the double inbound and outbound channels needed for quick turnaround fulfilment. Certain laws govern traffic and deliveries in populated areas, at night for example, which is not a problem for warehouses or industrial locations, but may be for more central dark stores.
Whatever the problems, it remains that having centres closer to customers could mean transferring the job of pick-up and delivery to consumers which would create considerable savings. It also opens up the possibility of allowing customers to return goods themselves instead of packing them up and taking them to a delivery office. Some companies like Tesco in the UK or Walmart in the US have been experimenting with dark stores for some time. Other companies are increasingly interested in the idea, such as El Corte Ingles in Spain for example.
Paradoxically, retailers without stores appear now to be considering a presence in retail stores as well as micro-distribution or dark stores. If, as it has been suggested, vacant Sears or JC Penney stores in the US were to be used as dark stores by online players for delivery and returns, it is only a short step to offering customers a little more during their journey and beginning to return the store back to its original purpose.
Returns management: shift some logistics to the customer
The NRF estimates that total returns by customers to retailers doubled in 2020 to 10.6% of total retail sales. This will include returns to e-commerce operations with a return rate estimated at over 25%. We can safely assume that, since apparel and shoes have the highest return rate, department store returns will be higher than that. A return is not only a failed sale, and one which has incurred selling costs, but also an operation which generates its own additional costs through reverse logistics. This reverse logistics process is one which is a prime target for refinement.
In this vein, even before Covid, Amazon partnered with Kohl’s to integrate the department store into its reverse logistics process thus supporting Amazon’s optimised returns while bringing an estimated 2 million extra customers into the Kohl’s stores. That the process creates increased revenue to stationary stores has not been ignored by retailers, some of which such as Magasin du Nord in Copenhagen, have set up a click and collect counter and storeroom on the ground floor to serve customers from a range of other retailers.
This vision of stores as a sales and logistics platform would appear to be a significant advantage held by store-based retailers. It allows them to place inventory close to customers in a situation where e-commerce is growing fast and the costs of fulfilment are taking off. Amazon’s fulfilment costs grew in 2020 by 45%, outpacing their online sales growth (estimated at 37%).
Thus, in effect, stores or dark stores are shifting some of the logistics costs of fulfilment and returns to the customer.
In-store retail: the rule of resilience and the hybrid store
Of course, even if e-commerce has been growing tremendously, most department stores are maintaining in-store retail as their core concentration. Some have been forced to close down, under the pressure of a sharp rise in the cost of shipping, substantial decreases in customer footfall, supply chain disruptions that proved too much for legacy planning and inventory management tools, and inbound inventory delays. According to Advanced Supply Chain survey, up to 92% of retailers have experienced inventory management issues. What some have described as the “supply chain strain” is not only the result of the Covid pandemic. The leaner the supply chain, the greater the strain it is put under by any disruption at all, such as the recent Suez canal incident.
It has become increasingly clear that, in a situation of uncertainty, just-in-time does not work. Many retailers are eschewing the once-popular lean model and thinking about a “just-in-case” model (see FT Just in time planning). Instead, they are broadening warehouse footprints to localise inventory for improved availability to their customers. Only a quarter believe that just-in-time inventory management is still relevant in the post-Covid environment. All gazes are turning towards the question of how to build resilient supply chains. Many are recognising also that investment in cutting-edge digital solutions to improve inventory management and visibility is part of the process of bolstering supply chains.
Furthermore, uncertainty and lower footfall has resulted in a new interest in local retail. Any method is welcome which will help provide shoppers with more reasons to visit a store. Diversifying ranges to attract and retain customers may transform stores into a model closer to the convenience store or the US drugstore, albeit with one dominant category. The desire to increase footfall might well bring operators in other retail sectors to serve consumer needs outside of their specialty.
As early as 2013, Forbes reported Macy’s pulling goods from stores and developing algorithms in order to limit out of stocks at store level, and achieve faster delivery as well as buy online pick up in store. In a strangely prescient piece, given the developments at John Lewis and Marks & Spencer for example, it also mentioned condensing the selling area and allocating more space to the backroom.
Imagine a store in which the selling area has been shrunk and converted to more of a showroom with interactive experiences; the rest of the store serving as a separate zone in which pickers would assemble a customer’s purchases; and digital technology would allow shoppers to select and pay for products on display. The resulting order might then be delivered to a kerbside collection point for the customer to pick up without having to wait in a checkout queue. Such a hybrid, traditional plus dark store, would answer many customers’ desire for a store experience without risk while allowing retailers to be flexible with both conventional and e-commerce formats as required. It would also serve as a collect and return point for online customers.
Logistics has become a customer issue
Many of the questions raised by omnichannel, and which have been put under the spotlight by the Covid pandemic, are in fact logistics questions. The recent customer expectations we are struggling to fulfil are in fact issues for supply chain and logistics: fulfilment from stores; dark stores; buy-online-pickup-in- store; click-and-collect; buy-online-return-in-store. All these are trends dominating the current retail scene and which have been accelerated by Covid. They are all heavily dependent on efficient and adaptable supply chains, and they all place logistics under consumer scrutiny. In the same way that steam and electricity transformed manufacturing, so digitisation is having an equally important impact on supply chains. As it matures, digitisation will be increasingly used to fulfil customer expectations in terms of time and availability, as well as offer a profitable and resilient fulfilment solution to retailers.
Credits: IADS (Dr Christopher Knee)

