IADS Exclusive Articles

IADS Exclusive – A cruel awakening: what the macro-exposition of Department Stores means
IADS Exclusive – A cruel awakening: what the macro-exposition of Department Stores means
Ever heard of the term “polycrisis”? French theorists Anne-Brigitte Kern and Edgar Morin coined this phrase in 1993 to characterise ‘the simultaneous occurrence and interaction of multiple crises that cannot be reduced to a single common denominator’. While the phrase was picked up by EU Commission president Jean-Claude Junker in 2016 to describe Europe’s governance during the Greek debt crisis, Russia’s first aggression against Ukraine, impending Brexit, and the Syrian refugee crisis spilling into Europe, it was popularised in 2022 by historian Adam Tooze, seeing the current world affairs in a situation where ‘disparate crises interact such that the overall impact far exceeds the sum of each part’.
Such a context requires businesses to look at their macro-environment in a new way, and ‘connect the dots’ between seemingly unrelated facts and data points. Before the summer, the IADS interacted with four different worlds: the FIRA retail federations meeting in Berlin, a column by the historian Adam Tooze, an article in The Economist, and a workshop convened by EM Normandie on the politicisation of business. While these are disconnected when taken in isolation, they suggest the emergence of a new macro-economic and political environment when read together. While this does not mean having a crystal ball, and the purpose of such an exercise is not to forecast, this allows for new angles that department store leaders interested in the transformation of their business should consider in their strategic reflection.
Department stores have long thought of themselves as national commercial institutions with a customer, a proposition, and a margin. While there are some exceptions for those who went international (such as Galeries Lafayette), they seldom see themselves as macro-exposed outside of their supply chain. The four reads below suggest that this posture is increasingly hard to defend: their flagship stores, their long-cycle inventory, their significant cash positions, their pricing latitude, and, above all, their trust are all connected to regional or global political and economic instruments that, until recently, were in the background of their strategic planning process. However, this background seems to be moving into the foreground, and retail leaders might need to consider new questions as they plan their upcoming strategy. Our hypotheses are based on four horizons derived from our analysis of four sources.
First horizon: where retail stands as of now
Last April, the IADS attended the mid-year meeting of the Federation of International Retail Associations (FIRA) in Berlin (report available here). 18 delegates from 14 national federations sat at the same table and described the same operating environment.
Concerns about the energy were universal. The consensus was that even an immediate reopening of the Strait of Hormuz (in hindsight, a vain wish) would not bring prices down for at least six months: petrol fluctuates quickly, and the cascade runs through transport, packaging, and petroleum-based inputs. India brought the most concrete second-order picture: shortages of liquefied petroleum gas cylinders had already pushed restaurants to alternative fuels, and the urea and fertiliser shock would surface only after the rainy season, with delayed pressure on food prices.
Inflation was another issue. Prices are still catching up to the 8% shock of three years ago, working their way through wages, rents, and contracts. A potential return to 3 or 3.5% inflation isn't relief: prices don't fall back; they just climb more slowly from an already-inflated base. This is why consumer confidence shifted from budgetary to behavioural: Belgium and Germany reported that households were parking money rather than lacking it; Germany's e-commerce channel grew by more than 3% in Q1 precisely because consumers were using online for price comparison and bargain-hunting. Australia recorded its worst consumer confidence since 1968 (including during COVID). Ireland’s consumer confidence lost 18% between February and April. Italy's stable volumes were considered to be masking speculative pricing by operators.
However, two other points caught our attention.
The first was Shein and Temu. Every European delegate and the Australian delegate cited them by name. Australia now records a 5% share of the entire national fashion category for what its retailers call "Sheemu", only two years after Shein and Temu entered the market. The diagnosis was unanimous: these players operate outside the safety, sustainability, and consumer-protection regime that binds incumbents. Customs and tariff reforms are in train, no association reported by then, a measure that had yet moved volumes.
The second was European regulatory paralysis. Many European associations complained that Europe has lost its capacity to think strategically because it had been firefighting since COVID. The competitiveness agenda, regulatory simplification, and the response to third-country platforms compete now with three further fronts: unfair trade practice rules between brands and retailers, an ongoing sustainability review that has been simplified but not lightened, and a geopolitical paradox (the need to open new trade partners, Mercosur, Australia, even China, while confronting Chinese platform competition at home). The textile sector's stop-and-go on circularity was the clearest illustration. Brussels, a delegate observed, now needs "to simplify the simplification procedure."
While none of this is breaking news, what was striking was the unanimity among peers from geographies with entirely different institutional and consumer conditions, suggesting that we are not in a cycle but facing a structural difficulty that won’t be resolved through tax cuts or elections, especially in Europe.
Second horizon: How policy could evolve in reaction, tomorrow
If the environment remains durable, the next question is what governments could do about it. What is noticeable about it is a radical change in vocabulary.
In May, Gita Gopinath, until recently the first deputy managing director of the IMF, now returned to Harvard, used an op-ed in the Financial Times to warn that governments constrained by fiscal space may rely on "broad-based price controls, financial repression, nationalisations, and pressure on central banks to absorb fiscal risk." While she did not endorse those instruments, she flagged them as a scenario that markets are currently not pricing.
Adam Tooze, the Columbia University historian, extended the argument on his Substack feed (link), observing that the ‘Washington Consensus’ (in his words, the framework defining which policy instruments were respectable and which were not) had already been quietly loosened. Emerging market central banks have been combining inflation targeting with foreign-exchange intervention, capital controls, and macroprudential measures for years. According to Tooze, even the IMF and the BIS moved to rationalise these practices. What Gopinath called the "Four Horsemen of Heterodoxy" (price controls, nationalisation, fiscal-monetary coordination, financial repression) are not the arrival of something new, but, in Tooze’s view, the acknowledgement of something already underway:
- Price controls, not in the crude 1970s sense of a state-set price for milk, but in a much more modern sense: category-specific caps, windfall taxes, mandatory margin disclosures, or coordinated pressure on food, energy, and household basics. In Berlin, Spain's retail federation and EuroCommerce flagged food as the next political battleground after fuel, which is where this instrument could land first.
- Financial repression, in practice, means real interest rates deliberately held negative for an extended period. Not as an accident of monetary policy, as during the pandemic, but as policy, with financial regulations designed to prevent avoidance. For a business whose cash reserves earn nominal returns and whose long-term debt was contracted at higher real rates, financial repression is a wealth transfer of significant scale. It is also, historically, the least politically visible of the four instruments, which is precisely why governments could choose it.
- Targeted nationalisation, or, as Tooze puts it more accurately, the threat of such measures. The instrument works even when not in use. In sectors with strategic exposure (energy, telecoms, critical infrastructure), the credible possibility of state intervention shapes corporate behaviour. Retail is not first in line. But flagship real estate in politically sensitive city-centre locations is closer to the frontier than many CEOs assume, particularly for members whose flagship building has cultural or heritage status independent of the retailer occupying it. The recent example of the Paris mayor considering buying the BHV building is an illustration of such a change (link to the news and our analysis of the BHV case here).
- Fiscal-monetary coordination: central bank independence is not being abolished but renegotiated, with a direction toward greater accommodation of fiscal deficits. The implication for members whose treasuries hold non-euro or non-dollar balances is that the "backstop" investors are pricing may become a policy commitment rather than a discretionary intervention, with consequences for currency stability, cross-border capital flows, and the cost of any debt not held on a hedged basis.
None of these instruments is for real now; however, they are on the policy table in ways they were not five years ago, and retailers should not be wondering if they might be used by governments, but prepared for the potential when.
Third horizon: there might be a bigger, more structural shift coming in the long run
The Economist recently observed that for most of the past century, rich countries shared prosperity through a simple settlement: raise revenue mainly by taxing labour and consumption and redistribute through cash transfers (link to our report). That model may not survive the advent of artificial intelligence.
The reasoning is that if AI shifts income from labour to capital at anything like the scale its promoters suggest, the tax base built on labour income collapses. Governments will still need revenue (probably more, if unemployment is high), but they will have to find it elsewhere. The average OECD member currently raises about half its tax revenue from labour and roughly a third from consumption; the United States, which has no national consumption tax, is especially dependent on labour. The obvious substitutes are heavier consumption taxes, capital taxes, and, more radically, spreading ownership of the technology itself through equity distribution, sovereign wealth vehicles, or expanded public pension shareholding.
This is obviously not going to happen tomorrow, but it might be a reality within ten to fifteen years. A department store CEO signing a twenty-year lease on a store is implicitly betting on the demand structure of an economy whose tax and distribution logic may look very different by the time the store amortises.
Two implications matter for department stores:
- The first is that consumption taxation (VAT in Europe, sales tax in the United States, GST across most of Asia) is the shock absorber most likely to be adjusted upward. Every point of consumption tax is, at the margin, subtracted from the department store proposition. Members whose businesses are most exposed to price-sensitive segments should model this explicitly rather than treat it as background noise.
- The second is that the political legitimacy of large capital-owning organisations will be examined in ways it has not been for a generation. Department stores are not tech giants, but they are visible, publicly recognised holders of significant real assets, and in a number of markets, they are among the largest single occupiers of prime urban real estate. In the tax-and-redistribution conversation that AI will force, they will not be invisible.
The fourth reading: the end of neutral ground
At the end of June, IADS attended the opening session of a three-year research programme run by EM Normandie's AGORA institute, in partnership with Georgetown University and Florida Atlantic University, on the politicisation of business (report available here). Practitioners from L'Oréal, Google, Ubisoft and Airbus sat with academics from four American and two European institutions. The question was simple: can a company still credibly claim to be apolitical?
The workshop concluded that the answer was a clear no, or at least, not without effort. Once corporate activism has become the norm, neutrality is itself a position. It can be defended, but only if it is asserted and practised consistently. Silence is legible as a choice (and legible differently to different constituencies).
Two of the workshop's findings added up to the first three horizons mentioned earlier in ways that are directly relevant to the department store:
- The first is procedural: the credibility of a corporate position does not come from the position itself, but from the transparency of the process that produced it (who sat at the table, whose incentives dominated, whether an ethical voice was present at the strategic level rather than in an advisory function). In a politicised environment, decisions are read cynically by default, and only procedural discipline earns the benefit of the doubt.
- The second is structural: size changes the rules. Formal procedures, ethics functions, reputational exposure and lobbying capacity all scale with the organisation. Large firms hold a structural advantage in regulation (legal complexity and access to institutional channels favour the better-resourced), but that advantage shades into regulatory capture when they are the only actors able to shape the rules. For a format whose members are often among the largest single retail employers in their market, this ambiguity is not academic. It is the terrain on which every ESG commitment, every tax-optimisation choice, every sourcing decision will now be read.
For a format that trades on a century or more of accumulated trust, this matters. Trust takes years to build. It can be destroyed in a single decision. The calculation for any political position is not "Is it correct?" but "What does it cost in trust, and is that cost recoverable?" That calculation argues for procedural discipline over substantive boldness, which, paradoxically, is an issue for a format looking for reinvention.
What the newfound macro-exposure of department stores means
Department stores are macro-exposed in a way most operating conversations do not yet acknowledge. While conversations on customer traffic, category performance, and format innovation remain obviously crucial, they are now nested inside a set of political and macro variables that used to be in the background. This suggests that, when starting new commercial cycles, CEOs should ask their organisations an additional new set of questions, taking into account a macro-political focus:
- On cash and debt: if real interest rates are held negative for an extended period as a deliberate policy, how does that change the cash strategy, the debt posture, and the willingness to hedge?
- On pricing: if category-specific price controls or windfall measures land on food, energy, or household basics, does the assortment structure absorb the change gracefully, or does it distort the proposition?
- On consumption taxation: if the largest market raises VAT or its equivalent by two to three points over the next decade to substitute for eroded labour taxation, does the value proposition hold, or is there a need to reprice?
- On real estate: do the flagship locations sit in cities whose political posture toward large capital-owning organisations is stable, or is there a need to model exposure scenarios?
- On corporate posture: have retailers consciously chosen their position on the questions their society will force on them, or are they relying on a silence that is now legible as a choice? And if they have chosen, is the process that produced that choice defensible under scrutiny?
None of these questions has a universal answer; they depend on context, market, and governance. However, they are meant to be run.
Credits: IADS (Selvane Mohandas du Ménil)

IADS Exclusive – Is department store beauty as we know it dead?
IADS Exclusive – Is department store beauty as we know it dead?
Beauty in department stores offers quite a uniform picture: the first thing shoppers smell and see, sitting on the ground floor to drive traffic and conversion. Despite this long-standing model, the category is challenged as department stores are no longer the primary channel for beauty discovery. Competition from speciality retailers, e-commerce, and social media has eroded their historical leadership. For example, only 24% of US shoppers now visit a department store to learn about new products, with 71% turning to Sephora or Ulta Beauty, showing that consumers want more than traditional brand-counter organisations. The proliferation of discounts and new brands also brings additional challenges.
However, despite that bleak situation, many department stores recently invested in their beauty floors, from John Lewis to Macy’s, to benefit from the current category momentum. Indeed, in 2023, global beauty market retail sales grew to $446 billion, up 10% from 2022. In 2025, McKinsey expected beauty to continue growing at 5% over the next five years. The outlook is still positive in 2026, and the category should reach $590 billion by 2030. In that picture, department stores have the weakest outlook, having already declined by approximately 2% annually since 2019 and facing a similar outlook in the coming years. So, is beauty still worth it for department stores, or could it go extinct? If so, what could replace it and drive similar traffic and conversion?
The new beauty floor: assortment, services and productivity
Product categories to drive growth
For now, beauty remains a key category, though category leadership has shifted in recent years. According to McKinsey, fragrance has overtaken colour cosmetics as the third-largest beauty category. It is expected to continue growing across price points, driven by new behaviours such as using different fragrances for different occasions. This growth is supported by masstige brands as well as prestige and niche scents, as exemplified by the recent addition of new brands such as Argentinian brand Fueguia at Galeries Lafayette Haussmann, or the renovation of Selfridges’ fragrance hall. Overall, as stated by most IADS members, there is no sign of slowing down in niche fragrances.
On the other hand, skincare is at a crossroads. With inflation and information at hand, consumers are less convinced that higher prices automatically mean better performance, as dermatologist-backed, K-beauty and dermo-cosmetics brands show customers that lower-priced offerings can achieve similar results. In parallel, as IADS members note, the traditional anti-ageing skincare promise is being challenged by the notion of longevity, a more holistic perspective that includes supplements, wellness, and aesthetic treatments.
The colour cosmetics category has been under pressure after several years of minimalist makeup trends, but now shows renewed interest in bolder makeup looks and hybrid makeup-skincare products.
In addition, IADS members mentioned that beauty is expanding into adjacent categories: hair care and specifically scalp care, supplements, sleep care, nutrition, sun care, nail care, aesthetic services, and at-home devices such as LED masks and radio-frequency tools. Finally, men’s beauty is growing across markets according to IADS members, with brands such as Nivea For Men, Biotherm Homme and Horace.
Making beauty services visible and valuable
Access to the product categories above is a given for customers. What makes a difference is the customer experience, including services. Mostly in treatment cabins, services are hidden for obvious reasons of intimacy. Usually managed by brands, they are sometimes not even advertised in the store, making them invisible to customers. Department store executives and brands should challenge their location and visibility, as services could serve as a floor-animation tool, as shown by department stores’ wellness initiatives.
First on the trend, Harrods opened their Wellness Clinic in 2017, an appointment-only 1,000 sqm space on the fourth floor in Knightsbridge. Closed-door, yet advertised, the space was never intended to be a traditional spa or beauty salon. Harrods envisioned it as a high-end, results-driven clinic offering a curated selection of treatments designed not for pampering, but rather for measurable results. The range is unusually wide for a department store, covering everything from injectables and body contouring to cryotherapy, DNA-based personalised skincare, IV vitamin infusions, dental services, osteopathy, podiatry, physiotherapy, personal training, nutritional coaching, and more, making personalised service a reason to visit. Second, with a different approach, Galeries Lafayette opened their Wellness Galerie in 2022, with a full 3,000 sqm floor, including an unprecedented 60% space share given to highly visible services: a gym, infrared sauna, and a hyperbaric chamber, to name a few. Some services are now discontinued, though, showing how challenging it is to make those offerings successful and profitable compared to product-selling core activities.
Fewer SKUs, more cash
In a world where discount is king, it is no longer worth carrying some brands, as department stores can never compete on prices. This is the case for premium fragrances for some IADS members, for example. Instead, shifting to niche labels can act as a footfall and growth driver. This comes down to the department store role in discovery rather than offering the broadest assortment.
For some, the game is on cash. Challenging brands to reduce quantities in each SKU (Estée Lauder’s Double Wear 54 shades of foundation are certainly not selling equally), down to individual lipstick or foundation lines, has unlocked cash savings without degrading how customers perceive assortment breadth. In that case, stores are graded A, B, C, D with quantities aligned to the grade. This is typically a beauty‑specific problem, underscoring how being an efficient merchant includes negotiating with brands to reduce the number of SKUs carried. This is no easy task, though, as department stores must ensure customers still believe they are offered a broad, diversified assortment. Department stores must manage this contradiction: “simulate” a broad yet curated brand and product assortment while rationalising SKUs and quantities.
Bringing beauty to another level, or dimension: space, placement and the question of digital
The need for renewed differentiation
With inflation and the proliferation of information, consumers are more value-conscious and knowledgeable. As a result, they are increasingly buying across price points, mixing mass and prestige products within the same routine. For example, around 20% of brands carried by US speciality beauty retailers are also sold at Walmart, illustrating how price and channel boundaries are blurring. As assortments become more similar across retailers, exclusive and differentiated products become competitive advantages. Without a differentiated assortment or shopping experience, consumers choose the retailer offering price, convenience, delivery speed or loyalty benefits, especially for replenishment purchases where loyalty to a retailer doesn’t matter. To differentiate and make a trip to the store worth the effort, department stores are creating alternative offerings through multi-brand areas selling small, niche brands or French pharmacy spaces, as exemplified by Falabella and Galeries Lafayette.
Borrowing from Sephora: the agnostic model
Sephora and Ulta Beauty had trained consumers to expect an agnostic experience with open shelves and independent expert advice. Even though department store beauty counters as we know them cannot replicate this agnostic model, building new experiential spaces has become a growing concern.
Falabella gives the most advanced answer to this problem with Beauty F, its own specialist beauty format, designed, built and operated fully in-house: an enclosed space with a single entry point within Falabella department stores that functions as a standalone retail business, not a collection of brand concessions. The open-shelf layout integrates testing stations and advisory zones. The sales force consists entirely of Falabella employees, avoiding competing loyalties. Falabella deals directly with brands, importing and curating the selection, including younger, trend-driven, celebrity brands and K-beauty brands, and supports CapEx costs.
One of the most commercially significant Beauty F successes is re-engaging customers who haven’t shopped in more than 12 months. Twenty per cent of the customers are aged 18-35, a cohort that has largely abandoned department stores. According to Falabella, the share of young customers and new customer acquisition have both doubled since the format launched, and new brands introduced through the format contribute significantly more than the legacy assortment.
Beauty as a vertical journey
Another differentiating option exemplified by Galeries Lafayette is to spread beauty across three floors, a deliberate vertical journey. The -1 floor offers an updated, more realistic version of the Wellness Galerie initially launched in 2022, oriented towards care brands and beauty services. The ground floor centres on fragrance and makeup, including recent additions such as Victoria Beckham, Louis Vuitton makeup and 13 niche fragrance brands. Creating a destination within the luxury RTW floor, the +1 level brings together luxury fashion, jewellery and beauty, with high-end perfumery spaces for Loewe, Dior, Chanel, Maison Francis Kurkdjian, Officine Universelle Buly 1803 and more.
This overhaul aims to differentiate Galeries Lafayette from competitors by blending luxury and beauty and giving the luxury RTW floor a more lifestyle feel. Now accounting for about 10% of the store’s annual volume, beauty has posted double-digit growth in 2025, continuing into 2026. The beauty selling space has expanded to 3,700 sqm, an increase of 500 sqm, bringing the total brand count to 440. This demonstrates that, despite a bleak outlook, department stores can still play their cards right.
Beauty growth is moving online, TikTok accelerating the shift
E-commerce is expected to drive most of the beauty sales growth through 2030. Globally, e-commerce already represents the biggest channel at 28% of beauty sales, ahead of grocery at 19%. The US market illustrates this. Amazon, Ulta Beauty, Sephora and TikTok together account for just under half of US beauty sales. Amazon and TikTok’s combined beauty sales could soon exceed Sephora and Ulta combined sales. TikTok is a complete commercial channel, as US beauty sales on the platform have grown at approximately 260% annually since 2023. This is not a niche youth phenomenon, as the 35-55+ bracket makes up 49% of daily users.
Department stores are not built for the content TikTok demands. The format that wins on TikTok Shop is high-frequency and creator-native, a volume and style of content most legacy retailers are not resourced to produce, and simply repurposing existing brand assets does not work. Department stores don’t have the beauty-native content muscle of Sephora (nor the lower cost structure that lets them channel more funds to online), and maintaining a content presence for every brand on the floor is not viable at department store scale. A cheaper way to close part of this gap is to translate viral discovery into physical offerings. This is what Sephora has built with their ‘hot on social media’ in-store visibly labelled spaces, a feature department stores could take cues from. With its constantly changing beauty ‘newsroom’ in-store sections, Mecca is also a beauty retailer to watch.
In that digital-first environment, department stores have steadily ceded beauty share to online retailers and speciality players with strong e-commerce operations. To defend their positions, IADS members have strengthened their online operations, resulting in modest growth in average share compared to competitors, from 14% of the beauty business in 2024 to 16% in 2025. Some, such as El Palacio de Hierro, set up dedicated beauty accounts on Instagram and TikTok, knowing social media economics remain challenging because of promotions, affiliate commissions, and high customer acquisition costs.
If not beauty, then what?
The easy option: more products
What could replace beauty with equivalent traffic potential? The temptation to fill the ground-floor, highly visible space with more products would be strong. Creating or expanding the number and surface area of pop-up spaces to feature commercial exhibitions comparable to what Le Bon Marché offers, or these spaces to brands for rotating product discovery, is an option. Another option is to offer larger concession spaces, especially to luxury brands, allowing them to present their full brand vision in one space, such as a free-standing store. Though both solutions would generate short-term revenue, they would transform the ground floor into a mall-like environment and compromise the store's identity. Besides, none of these options would avoid e-commerce cannibalisation unless spaces are filled only with exclusive products. Non-product-selling businesses would avoid that, though they raise the question of how to achieve the same commercial results as product selling.
F&B as the new footfall driver
F&B offerings present opportunities, as food experiences drive significant dwell time, repeat traffic and purchases for food replenishment. Harrods measured that when customers engage with the store’s restaurants and bars, they spend twice as long in the building and twice as much money. Department stores already have F&B options, but the goal here would be to make it a true destination for meals and food purchases, such as the La Grande Épicerie de Paris store in Paris, or the food floors at KaDeWe in Berlin and at Isetan in Tokyo Shinjuku. But it raises the question of how to push customers to other floors for cross-category shopping. So, replacing beauty with F&B would probably require more than repurposing a floor. It would require an entire store reshuffle to include more food offerings across floors.
Selling entertainment over products
Paid experiential and entertainment concepts could fit, as The Cinema at Selfridges or The Selfie Experience at El Palacio de Hierro in 2022. Made up of several striking backgrounds for visitors to take selfies, The Selfie Experience drew large crowds from its inception. In 2023, El Palacio de Hierro renewed the initiative, in collaboration with Mattel, for a new Barbie Selfie Experience in their Polanco store. An average of 900 visitors per day could also purchase dolls and accessories at the end of the tour. The third edition in 2024 consisted of a tribute to David LaChapelle. In 2025, two editions were launched, one about Tokyo and one for Christmas. Repeat editions show the initiative's success in attracting customers at least once a year, but it also implies a constant renewal of concepts.
Community and membership
With their central urban locations and historic architecture, department store ground floors would be natural candidates for community spaces. Monocle makes a clear case for stores functioning as third spaces, lounges, community hubs, or destinations rather than purely transactional environments. Merci in Paris is a realistic, successful example of combining a café, second-hand books, fashion and home retail and cultural events. From that perspective, a department store’s well-designed lounge floor with books and magazines, beverages and comfortable seating could draw a loyal daily community of urban professionals in exchange for a fee. But again, this option raises the question of how to push customers to buy something besides enjoying the space. A more relevant option is to use the freed space to build a private members' club, such as Selfridges’s 40 Duke club. With tailored spaces, F&B offerings, exclusive services and concierge, a private club demonstrates an attempt to further increase loyalty and customer engagement. The freed floor space could also allow different options catering to different levels of VICs.
The beauty floor becomes a diagnostics hub
Tech and medical services could replace beauty. The freed space could house diagnostic technology such as Zoi body scanning checkups. Malls have started leasing anchor space to clinics, as exemplified by Simon's Smith Haven Mall in Lake Grove, NY, now having a hospital-system clinic where a Sears store used to be, or the Mediclinic at the Dubai Mall. That's a new category for the mall format.
Though some of these ideas already exist, the IADS doesn’t think beauty will disappear from department stores. Its replenishable nature drives repeat purchases. As a category that includes low prices, it draws traffic and sales thanks to the ‘lipstick effect’ when other product sales are slowing in difficult times. Without a radical retail overhaul, the challenge is to reinvent the beauty department while maintaining profitability. Department stores are already launching projects to build renewed beauty floors, be it through massive renovations, wellness services, or new multi-brand formats.
Alternatives to beauty could generate foot traffic, but they would require a floor-plan rethink, constant refreshing of entertainment concepts, or entering healthcare's unknown territory. In any case, it would imply giving up on product selling. By contrast, beauty is a replenishable category department stores already know how to run, and the ground-floor logic still stands. The question department stores are tackling is ‘how to change beauty’, rather than ‘beauty or not’. Department stores are already making distinct choices that don't all point in the same direction. Increasing fragrances is only a category adaptation. Assortment strategy means smart brand portfolio and SKU-refined management, both skills department store executives have. Space strategy means whether services stay hidden or become visible floor activity, understood as a customer draw, not just a treatment room. Alternative formats mean deciding whether to keep the counter model or completely change the beauty business model, trading brand partnership for full control. This is the bolder and riskiest choice of all. Here, Mecca is a beauty retailer to watch: beautiful, service-led, experiential spaces, 200 exclusive brands, and "best beauty friends" guiding customers across the whole store regardless of brand, a service model with no rigid brand-dedicated sales spaces.
Credits: IADS (Christine Montard)
IADS Exclusive: How a century of Greek department stores led to Attica’s IPO
IADS Exclusive: How a century of Greek department stores led to Attica’s IPO
On 2 July 2026, Attica Department Stores began trading on Euronext Athens, 21 years after opening beside Syntagma Square in Athens, and therefore becoming the only listed department store in Greece. The listing was a secondary offering: the selling shareholder offered to sell up to 29.92% of the company, but Attica itself received nothing. The offer was 3.9 times oversubscribed and priced at the top of its range for a day-one capitalisation of €192.5 million.
To understand such a move, it is important to grasp the fundamentally different nature of the Greek retail market, where the “everything under one roof” idea disappeared in one generation and was replaced by a premium proposition. In that context, Attica’s IPO is less a financial transaction than the latest instance of a tension every fund-owned department store knows: what happens to a patient, relationship-driven institution when the capital that steers it reasons in exit horizons?
A century of Greek department stores
From a department store paradise to a land of desolation
The first modern Greek department stores appeared later than in the rest of Europe, but in numbers: Dragonas (1896), Athenee (1898), Klaoudatos (1900), Lambropoulos Bros (1901), Akron Ilion Krystal (1925), Minion (from a kiosk founded by Ioannis Georgakas in 1934 to a full department store from 1944) and Katrantzos Sport (1939).
Minion, dubbed the “Greek Harrods”, was leading the pack. By the 1950s, it carried some 120,000 different products, employed around 1,000 people, and, by the 1970s, ranked among the largest department stores in Europe. Minion introduced fixed pricing, escalators, air conditioning, television advertising and a Christmas celebration in Greece that is still remembered in 2026. Katrantzos Sport was an eight-storey reinforced-concrete building with sixteen escalators and a separate goods-handling system. Lambropoulos completed the trio: “meet me at Lambropoulos” was a common sentence in the city, thanks to Greece’s first climate-controlled entrance, introduced in 1965.
A dramatic break occurred on the 19th of December 1980, with a coordinated arson in Minion, which was destroyed, and Katrantzos, which partially collapsed. Combined damage was estimated at roughly two billion drachmas (€133m adjusted for inflation, as of 2026), against which Minion was reportedly insured for only a fraction. The terrorist action was claimed by a previously unknown group, the “October ’80 Revolutionary Organisation” and the case was never solved.
A second wave followed from June to July 1981, damaging Klaoudatos, Athenee, Dragonas and, in Piraeus, Lambropoulos. In hindsight, according to the Greek press at the time, these firebombings “ended the era of Greek-owned department stores and cleared the way for foreign multinational retailers.” This sequence of events radically differentiates the Greek market from others. Elsewhere in Europe, department stores lost ground slowly, to malls, to fast fashion, to changing city centres, and had two or three decades to adapt or fail. In Greece, the format was removed at its commercial peak, in eighteen months, before that competitive pressure ever arrived. The malls and the fast-fashion chains came afterwards, into space that was already empty.
Minion never recovered: debt-laden after the fire, it was nationalised in 1983, bought back by Ioannis Georgakas, the founder, in 1991, and closed for good in 1998, with its building standing empty for nearly three decades. Most of the remaining department store companies went bankrupt in the mid-1990s. The last one, Lambropoulos, was sold by the family in 1999 to the Papaellinas group, and the store was renamed Notos Galleries Lambropoulos, before being integrated into the Notos group in 2001.
In the meantime, competition changed in nature: while Marks & Spencer had entered the country as early as 1978 with the support of a supermarket leader, the Marinopoulos family, Zara opened on Ermou in the mid-1990s, and H&M in 2007, as the environment favoured new players and fast fashion, thanks to the appearance of a new format: malls. The Mall Athens, 58,500 m², opened in November 2005, followed by Golden Hall in 2008, transferring footfall from the historic centre toward Marousi and the suburbs.
Such a new environment encouraged the opening of a new department store in the city centre, Attica, in 2005, with a significant change from the former generalist emporiums that Athenians were used to in the past: it was the first curated, premium, fashion- and beauty-led department store of its kind in the city. Attica inherited nothing from Minion or Lambropoulos: no building, no company, no staff. That lineage passed to Notos. What Attica inherited was the absence: a capital city of four million with no department store of scale, and a generation that remembered what one felt like.
The financial crisis came in as a full reset
The 2010s sovereign debt crisis was, in effect, a filter that separated healthy and fragile retailers (a phenomenon the world would experience in 2020 with the COVID-19 crisis). By August 2012, nearly a third of the shops in central Athens’ prime commercial triangle stood empty, and vacancy on top-tier streets such as Ermou ran near 10%. By 2015, store closures spiked as the recession and austerity returned, but, most importantly, Greeks, who had long relied on cash, were forced almost overnight to use cards, seeding the electronic payment habit on which the country’s later e-commerce growth would rest. The parallel collapse of the Marinopoulos supermarket empire into Sklavenitis in 2016–17 showed the shock's magnitude, while Notos entered a long managed contraction, closing its Home store in 2019.
But, as the saying goes, “nothing beats a good crisis”. In September 2023, IDEAL Holdings, an Athens-listed investment company, acquired 100% of Attica for €100 million, financed by €65 million of bank debt and €35 million of equity. By 2025, Attica operated four stores in Athens and Thessaloniki totalling roughly 69,000 m², carried close to one million products, drew some 6.9 million in-store visits, and posted a series of records: revenue of €244.2 million (+5.3%), comparable EBITDA of €30.4 million (+11%), comparable pre-tax profit of €23.6 million (+19%), and net cash of €40.7 million, including €10.8 million of card receivables. In parallel, in April 2025, the Minion building reopened, not as a department store but as a mixed-use complex, with offices, planned apartments and a Zara flagship as its retail anchor.
However, things did not end up rosy for everyone: in May 2026, the owners of the Notos building declined to renew the lease, setting its permanent closure for 31 August 2026.
The current state of the Greek market and why Attica went public
When listing in 2026, Attica was navigating a healthier market, as the rents on Ermou (Athens’ high street) suggested: while they collapsed to roughly €1,800 per square metre per year in 2013 (the 31st most expensive street globally), by 2025 they had recovered to around €3,720 per square metre per year (the 15th most expensive globally and 6th in Europe). In top-tier streets (Ermou, Kolonaki, Glyfada), vacancies fell from around 10% in 2015 to under 5% by 2025. A tourism boom and the return of international brands to the centre drove this recovery.
In parallel, although Greek customers were already accustomed to e-commerce (a €9-10 bn annual market in 2025), the market has room to grow, as online retail still accounts for a high-single-digit share of total business, which is low by Western European standards. Fashion is the largest online category, an opportunity for Attica. However, two features of the Greek market make the digital opportunity harder than it looks:
- A large share of online spend leaks abroad: Temu and Shein capture a substantial portion of Greek fashion demand, and the largest domestic player by volume is the Skroutz marketplace, not a traditional retailer.
- Greek shoppers research heavily and abandon carts at rates around 75%, rewarding operators with deep CRM and logistics rather than a mere transactional website.
Attica’s e-commerce remains a low-single-digit share of sales, though growing fast, and its stated 2026 plan leans on omnichannel, CRM, and a new beauty store. By listing, Attica effectively commits to this curve rising.
How and why Attica went public
The listing was a secondary offering: KYMORA Limited, the Cyprus-based vehicle holding IDEAL Holdings' main investments (Attica, Byte, Barba Stathis) and in which the credit fund Oak Hill Advisors then held a 25% minority, sold existing shares, without issuing new ones, and Attica received nothing. 18 million shares (29.92% of the existing) were placed at €3.20 (the top of the range). Valid demand reached €212 million, 3.9 times the public offer, for gross proceeds of €57.6 million, of which €54.7 million from the public offer and €2.9 million from a parallel private placement. Day one market capitalisation was €192.5m.
The €40.7 million net cash reported at year-end did not reach the market: Attica paid its shareholders a €32 million dividend ahead of the listing, and net cash stood at €3.6 million on 30 June 2026, two days before the first trade. On that basis, the €192.5 million capitalisation implies an enterprise value near €189 million, or roughly 6.2x comparable EBITDA of €30.4 million. That figure excludes IFRS 16 lease liabilities of about €261 million; including them would raise the multiple substantially, but precedent department-store transactions are quoted on a pre-IFRS 16 basis, so the comparison holds. Precedent department-store transactions in the United States clustered around 6–10x EBITDA, and the banker analyses prepared for the Nordstrom take-private valued the sector at mid-single-digit multiples. In Europe, El Corte Inglés, earned €628 million on €17.2 billion of revenue in its 2025–26 year, with net debt down to 1.3x EBITDA, its lowest level in nearly two decades. Attica therefore came to market at the low end of the 6–10x precedent range, not the premium one would expect for a company with record results and a transformation plan, but the discount a small, illiquid market applies to any listing on it.
So why such a listing? Attica did not need capital: it generated €23.6 million of pre-tax profit in 2025, funds its investment plan from its own cash flow, carries no bank debt, and had enough surplus cash to pay its shareholder €32 million before listing. A capital increase would have diluted existing holders to raise money the company did not require and would have signalled a need that does not exist. A secondary sale avoids both, and allows it to crystallise value, establish a public reference price, and retain control.
This means the listing was not about choosing between a public listing and private financing, but about the nature of the owner. IDEAL Holdings describes itself as the only company listed on the Athens exchange that “invests with the philosophy of a private equity,” seeking companies with a “visible path to exit.” This is a far cry from the usual ownership in the department store industry, which lives on decade-long relationships with the brands that grant it exclusives, the buildings it makes into destinations, the customers and staff who give it a reputation, and investments whose returns arrive over years, not quarters. A controlling owner reasoning toward an exit and a public market reasoning in quarters add a new and conflicting time dimension.
The Greek market structure helps explain this. For Attica, the survivor of a fragmented market, a listing is defensive: it provides acquisition currency to consolidate a still-fragmented field, an external discipline that sharpens operations, and a governance standard no family-owned competitor can match. But the discount is the pressure. Listing below sector multiples means the transformation story Attica implicitly promised the market (omnichannel, CRM, digital experience, a new beauty concept) is not yet priced in, and someone now needs it to be. That someone is IDEAL, whose remaining stake converts to a return only if the multiple re-rates before it sells. A public company is expected to show that curve rising visibly and steadily, while a department store’s deepest work is invisible for several quarters before it pays.
Attica has to be both at once.
A Greek specificity or a foretaste of what is coming?
Department stores across the world increasingly sit inside investment vehicles, funds, holdings, family offices edging toward liquidity, and each must reconcile a patient format with an owner’s return horizon. Steen & Strom, Stockmann are two examples from the Nordic region, Nordstrom has been taken private by its founding family and Liverpool; El Corte Inglés manages a delicate balance between family branches and outside capital; in Asia companies are in the hands of giant conglomerates, and others sit in the hands of funds whose clocks are ticking. Attica is the most recent instance of that reconciliation being tested in public, with three things worth watching:
- The sincerity of IDEAL on the long range, when it says it does not intend to sell down further, but only at the end of the lock-up period,
- What happens to capital expenditure when the investment plan will meet a disappointing quarter,
- How e-commerce will aggregate, and not cannibalise, the store business.
The first data point arrived on 2 September 2026, two months after listing: H1 sales of €113.6 million, up 7%, with comparable EBITDA of €12.4 million and e-shop sales up 23%, but footfall flat and comparable EBITDA growing 3% while sales rose 7%. The same day, IDEAL announced it would buy out Oak Hill Advisors' 25% minority in Kymora for €118.75 million, on a €475 million valuation of the vehicle, taking its indirect stake in Attica from 52.5% back to about 70%: one fund's clock stopped, and the controlling owner's exposure to Attica increased. Management, for its part, guides full-year 2026 revenue and EBITDA growth of 7% to 9%, which would mean the first-half margin gap closes in the seasonally heavier second half. Margin compression in the first reported half is the second watch-item arriving early: not the disappointing quarter itself, but its shape. Attica has bet that market exposure protects a retailer rather than exhausts it. Two to three years of results will settle whether that was foresight or the moment a patient business took on an impatient owner's clock.
Credits: IADS ( Selvane Mohandas du Ménil)
IADS Exclusive: Sustainability as financial discipline
IADS Exclusive: Sustainability as financial discipline
A department store carries the environmental cost of its business model on every line of its accounts: hundreds of thousands of items sourced, a store estate to heat and light, and a delivery network built to move parcels quickly. It takes title to the goods it sells and holds the estate it trades from, so the emissions of the assortment and the emissions of the asset base both affect its own accounts rather than a supplier's or a concession partner's. Both therefore belong in the capital plan. Across the sector they are argued instead in the vocabulary of impact, materiality and disclosure — a language with no line in the accounts just described. IADS found the same during its Sustainability Operation Meetings in 2022 and 2023: the strategies were sound with reporting improving every year, and the case still had to be translated before a board would fund it.
The case has improved because two things happened: institutional investors converted a stated preference into an applied filter, and quantifying environmental exposure stopped being expensive. The obstacle was the cost of building a shared vocabulary. This has now collapsed with the ability of large language models to read a company's disclosures against its financial statements, work that was once laborious but not conceptually hard. The IADS position is that sustainability should now be run as capital allocation, subject to the same tests as anything else, rather than as a communications function with a budget attached.
The translation problem
Sustainability proposals in retail rarely fail on merit. They fail because a lighting retrofit or a packaging redesign is described by its carbon saving rather than by its effect on gross margin, and the two are never reconciled. Falabella's 38% year-on-year fall in regional Scope 1 and 2 emissions is a case in point: the reduction is reported as an emissions figure, while the energy efficiency and logistics changes that delivered it necessarily moved an operating cost line that isn’t stated beside it. The retrofit was costed in tonnes for an audience that allocates in margin points, and nobody converted it.
Carbon Trust found that a 20% cut in energy costs delivers the same benefit to the bottom line as a 5% increase in sales. A department store — a large, old, centrally located estate trading long hours — is the most leveraged possible case in a sector where retail buildings are already the largest consumers of energy among non-residential buildings in Europe. Yet the number that would move the decision, expressed in points of like-for-like sales, is left unstated.
The reporting frameworks were not built to close this gap and do not. The four pathways by which any investment creates economic value: reducing current costs, avoiding future costs, protecting revenue and securing investor access carry unequal weight for a department store. Each is examined in turn below. Whichever the pathway, a board weighs it on return and risk alone — and a proposal reporting neither is not competing for capital.
Some effects are quantifiable; others can only be argued directionally, and forcing the second kind into a precise number produces business cases that collapse under questioning. A department store commits capital on incomplete data routinely — an autumn buy placed six months out against a weather pattern nobody has, a concession agreement signed on a brand’s own unauditable sell-through projection — quantifying what it can and bridging the rest with argument. Sustainability proposals alone are asked to prove returns to a precision no other category faces. The evidential bar should be the one the store already applies to its buying and refurbishment decisions.
There is a second, larger distortion. The less-sustainable path almost always appears cheaper because the model has not formally priced regulatory exposure, customer or talent backlash, or eventual disposal costs. Pricing those risks explicitly, whether in figures or in stated direction, and then comparing the sustainable option against the fully loaded alternative typically narrows considerably and often closes entirely.
One feature of the department store model makes this translation harder than it is elsewhere. Between 90% and 95% of a retailer's total emissions sit in Scope 3, and the upstream part of that is, in substance, the emissions its suppliers generate in their own operations and their own supply chains. A department store therefore carries, on its own disclosure, a footprint generated inside businesses it does not own — and a single store might account for only 5% of a given supplier's business, which is why no department store changes a supply chain by itself. The consequence for capital allocation is that the pathways a department store can act on alone are concentrated in the small share of emissions it does own, while the exposure an analyst will model sits in the rest. A proposal that does not say which side of that line it falls on is not yet a business case.
The pathways that pay
Operational cost reduction is the least contestable of the four pathways: energy efficiency across large store footprints, packaging reduction across distribution networks, and waste recovery that removes landfill charges improve margins without requiring any customer to pay a premium. The magnitudes are company-specific and rarely disclosed as savings, which is itself part of the problem. Where described, the mechanism is an ordinary one: a certified zero-waste programme recovering 90% or more of store waste removes landfill charges, reduces handling cost, and turns part of the residue into a revenue line. All of it lands in operating costs in the year it happens.
Avoiding future costs means pricing regulatory schedules: exposure belongs on the balance sheet rather than in a compliance register. Chile’s Extended Producer Responsibility law imposes progressively tightening recovery targets on producers and importers of electrical and electronic goods; obligations with a timetable can be modelled as liabilities, and the question is not whether the business is compliant today but what the schedule costs over five years. The same exercise is available to every member trading in Europe on a longer schedule — five instruments with published timetables, from CSRD to France’s AGEC law, which makes the retailer accountable for green claims made by the brands it carries rather than only for its own. The French retail federation costed AGEC alone at an additional €3.5bn a year across the sector, around 35% more than retailers were then investing.
Revenue protection is the weakest of the four, depending as it does on a customer premium the survey evidence says is not there. Where it holds, it runs through the supply chain — for fashion and home, traceability of inputs. Falabella verifies material composition, certification and documentary traceability from origin for products carrying environmental attributes — a system that also maps where the business is exposed if an input fails. Its limit is the size of the set it covers: verification runs on the products carrying an attribute, while the rest of the assortment — in a department store, most of it — is estimated. Sector practice has been to hold real data for private label and apply category averages everywhere else — so the published figure is a small verified core surrounded by a large approximation. That is true of every such system now in operation, and it is where the residual analytical cost has moved.
Investor access demands demonstrable competence in identifying and managing material risk — in this sector no longer only an investor preference but a contractual term. Sustainability-linked facilities are already in use among large European department store groups, with the bulk of the margin tied to a few KPIs: meet them and the cost of debt falls, miss them and it rises. Where such a facility exists, a lender has already priced the plan and the board follows the KPIs because the financing depends on them: whether sustainability is a financial matter was settled by the loan agreement, not by the sustainability team.
The measurement problem dissolves
Establishing the link line by line was prohibitively slow until recently, and the evidence that this has changed is still thin with one demonstration worth examining closely. It was published in Harvard Business Review as “AI Can Measure How ESG Really Impacts the Bottom Line”, by professors Robert Eccles and Shivaram Rajgopal mid-2026, applied four widely available large language models to ExxonMobil’s public disclosures. The objective was to test whether AI could take the environmental and social issues a company itself discloses as financially relevant, map them to specific income-statement, balance-sheet and cash-flow line items, and estimate the effect of performance on each. The same analysis had previously been performed by hand, at a cost of roughly 100 hours. With AI, the core work took approximately one hour, and parts of it were completed in minutes. The cost of a financially grounded sustainability analysis has fallen by roughly two orders of magnitudexxiv.
The limits are acknowledged in the work itself: the choice of model mattered, and human judgment remained essential to determine whether outputs made sensex. AI compressed the labour without removing the need for expertise. The exercise also concerns financial materiality — sustainability as value creation for the company — not a company’s total effect on the world, increasingly termed impact materiality. The reporting frameworks conflate the two into a single score, and the sustainability field has borne the credibility cost.
When this capability reaches individuals faster than ratings agencies, standard setters and fund regulators can adapt, the advantage long held by proprietary ESG scores begins to erode, and the centre of gravity shifts from arguing over whose rating to trust toward examining assumptions and dollar consequences directly. Investors, analysts and regulators can now produce a line-item sustainability risk assessment of a listed department store from its own public disclosures, without its participation. The analysis will be performed regardless; what remains open is whether it is performed internally, early enough to change anything, or read for the first time in someone else’s report.
A risk filter instead of a values mandate
Much retail sustainability strategy still rests on the premise that a rising generation of values-driven investors will reward environmental commitment with capital. Four years of longitudinal survey evidence, covering American retail and institutional investors, indicate that this premise has decayed. In the first year, roughly 70% of younger investors expressed strong concern about climate risk against 35% of older investors. By 2025, that gap had largely disappeared and willingness to sacrifice returns fell as sharply: young investors who once claimed they would accept 6–10% lower returns now report a tolerance of around 3–4%, indistinguishable from their eldersxxx. Support for fund-manager activism has fallen to roughly one-third of young investors, again broadly equal to older cohorts. ESG support proved far more elastic than commonly assumed.
The same decay is visible on the demand side. Two thirds of Gen-Z shoppers say they are more likely to buy from a retailer with strong ethical credentials; the premium they will actually pay for a sustainable garment has been measured at around €3. A department store cannot fund a transition costed in points of turnover out of a €3 premium: stated preference is high, revealed willingness to pay is not, and a plan resting on the first will be repriced by the second. ESG still matters to capital markets, but as a risk screen rather than a values mandate — a narrower and more reliable role.
Most consequential is the asymmetry in how institutions apply the filter. Poor ESG characteristics can disqualify an investment with otherwise strong fundamentals, while strong ESG credentials rarely compensate for weak financials. For a department store the implication is a spending rule: if the upside of an excellent sustainability narrative is bounded and the downside of an incoherent risk position is not, then money spent on communicating sustainability is money spent against a capped return, while money spent on identifying and managing exposure is money spent against an uncapped loss. The budget should follow that asymmetry, which in most retailers means less reporting and more analysis. Programmes built on stakeholder goodwill are fragile, because goodwill is procyclical and the survey data show it contracting under economic pressure. The likely consequence is not a loss of access to capital but a slow repricing of it. McKinsey and EuroCommerce put the cost of the sustainable transformation at 0.4% to 0.9% of European retailers’ turnover, inside a total transformation requirement of 4.4% to 5.2% against the 3.6% the sector was then investing — €315bn to €615bn across Europe by 2030, in an industry where turnover per square metre has been falling. At that scale the allocation question is not whether to spend but on which side of the asymmetry, and there is no version of the answer in which the communications line grows.
Producing sustainability performance
Amazon’s packaging programme in Australia shows AI applied not to measuring sustainability performance but to producing it. Shipping goods without additional packaging was constrained by whether a product could travel safely in its own retail packaging, requiring manual review item by item. Amazon deployed a tool that makes that judgement from product data, and reports adding 12,000 products in a single month, that took manual work almost 18 months to accomplish. These are unaudited company-reported figures but the mechanism remains transferable.
The saving is genuine on two counts: the tool determines the minimum packaging consistent with undamaged delivery, so it is not damage cost shifted onto customers, and eliminating an outer box removes material, weight and handling cost — the saving lands in materials and freight whether or not the carbon is ever priced. AI did not invent the packaging strategy; it removed the assessment bottleneck that had kept it sub-scale.
The objection is that Amazon owns the product, the product data and the logistics, and can therefore decide on its own that an item ships in the box it arrived in. A store trading concessions and third-party brands holds no such authority over most of what it sells, and for that part of the assortment the mechanism does not transfer at all. It transfers to private label — up to 30% of turnover in some houses and considerably less in most — the single category in which the product specification, the supplier relationship and the packaging decision sit in the same hands, and where department stores have already done this work by hand, at the pace hand-work allows. Macy’s has reported cutting box volume, waste and virgin plastic use by half on the same logic.
Falabella: from principle to practice
The most detailed department store case available is also an unfinished one. Falabella Retail’s 2025 sustainability reporting — still in draft, with its regional policy awaiting board approval — makes environmental performance a condition of its omnichannel strategy, over the period of which the company reports moving from a US$200 million operating loss to a US$200 million profit. Falabella frames sustainability operationally in its sustainability report, which is not a neutral venue, and which earns its credibility from the numbers rather than from the framing.
The link runs through physical infrastructure. Falabella’s regional network — 290,000 square metres of logistics estate moving 30.9 million e-commerce parcels a year — is built for service speed and is also where the environmental gains are won or lost. Regional Scope 1 and 2 emissions fell 38% year on year, achieved through energy efficiency, renewable transition and changes to how stores and logistics centres are run, against a Net Zero 2035 commitment at group levelxlv. The same assets carry the service proposition and the intensity improvement, which is why this part of the investment case requires no customer premium: faster fulfilment and lower emissions per square metre are outputs of the same operational discipline.
While intensity per square metre fell 13%, Falabella’s total emissions rose 19% against 2024 — driven mainly by higher commercial activity feeding through to emissions from the purchase and use of products sold. This is the more useful disclosure of the two, and by some distance: it states a problem no growing retailer has solved, in that intensity and absolutes move in opposite directions because the efficiency gains land on owned assets while the emissions land on sold products. Falabella’s method — targets, measurement and scalable decisions rather than an accumulation of initiatives — does not resolve this divergence: a target on intensity and a target on absolutes cannot both be met by a growing business.
The IADS position is that the two numbers are not both achievable on the current department store model, and that saying so is more useful to a board than another target. If the great majority of emissions is generated by the goods sold, absolute emissions are a function of volume, and a growing store cannot reduce them by running its own assets better. Efficiency lands on the estate; emissions land on the assortment. Falabella’s disclosure makes that visible. The exit usually proposed is circularity, and its most ambitious form is untested. Selfridges’ target of 45% of turnover through rented, refurbished, recycled or resold goods by 2030, from 1% when it was announced, is the right bet even if it is missed. It has not cleared the margin test: at that share of turnover the mix effect on group gross margin is material, and it has not been published. Until then, the defensible position is to be judged on intensity, to disclose absolutes without softening them, and to say which of the two the business is running. A board that has chosen is in a better position than one that publishes both and commits to neither.
The tools required to quantify exposure and construct a case a CFO will accept now run on commercially available models applied to disclosures the company already publishes, at a cost measured in analyst hours rather than consulting engagements. For a department store the constraint is no longer whether the number can be produced but whether anyone in the building is accountable for producing it. The obstacle is now that no one owns the calculation: sustainability teams lack the financial mandate to produce it and finance teams lack the environmental data to check it. Tax is overlooked here as sustainability investments routinely involve credits, depreciation and incentives that never reach the business casel. And the test a CFO should apply is not whether the return is high but whether it was measured on the same basis as the rest of the capital plan.
Analysing what a company discloses is now cheap, acquiring what it does not yet know is not. Reading a set of accounts against a sustainability report is a closed problem with every input present; obtaining primary data from several thousand third-party brands and suppliers is an open one, and as recently as 2023 department stores were still assembling it in spreadsheets, without a traceability tool that covered their needs and without an agreed standard for exchanging Scope 3 data between companies. The measurement excuse has expired for the part of the picture the company controls; for the rest it has become a budget line — and the money that used to go into reporting is the money that should now go into acquiring the data the reporting has been approximating.

What damages financial performance is not sustainability spending but sustainability risk nobody has priced. The reason to do the calculation first is that someone else will do it, using the same disclosures, and a board that has not seen the result before an analyst does will be answering questions rather than asking them
Credits: IADS (Anchita Ranka)
IADS Exclusive – Transformative, not cosmetic: How Falabella retains beauty leadership
IADS Exclusive – Transformative, not cosmetic: How Falabella retains beauty leadership
With increased competition, the proliferation of discounts and the relentless launch of new brands, the beauty model in department stores is under strain. The traditional brand counters on the ground floor are no longer enough for customers seeking agnostic advice. For Falabella, Latin America’s largest department store group with operations across Chile, Peru and Colombia, the answer is Beauty F. In November 2025, they launched this new format, a new in-house beauty space inspired by the Sephora and Ulta Beauty models, built within the department store and then becoming a standalone business. This article analyses Falabella’s bet. Early results show it could help department stores maintain their leadership in beauty, but the investment intensity remains a challenge to building a specialist retailer within a department store. But beyond beauty, Beauty F tells a story of transformation.
The strategic problem: the new pace of beauty
How small brands are rewriting the rules of the beauty shelf
Large French-heritage brands occupying department store entrances (such as Hermès, Chanel and Dior) and conglomerate-owned brands (such as L’Oréal’s Lancôme or Puig’s Jean Paul Gaultier and Rabanne) have been successful traffic builders for decades. While they remain beauty floor anchors, as department stores still show to this day, the rise of small, indie beauty brands threatens this old model. Customer habits have changed as brand loyalty erodes, with 70% of consumers worldwide in 2025 having switched brands because they enjoy experimenting.
With more than 25% of all new brands launched in the U.S. being beauty brands, the impact on beauty retailers is significant: conglomerates' market share was 71% in November 2024 and 68% in 2025, with indie brands growing 3% at their expense. Not long ago, they were a niche market with a reduced following. They are now becoming a segment, even though most fail to scale beyond a US$1-US$50 million turnover bracket. In 2024, indie brands grew +22.3% vs. only +6.1% for conglomerates such as L’Oréal and Puig, accelerating from +16.1% the prior year and continuing to siphon market share. Emerging players spark curiosity and drive volume while conglomerates rely more on price increases: specifically, 62% of indie beauty dollar growth stems from more shopping trips, and 64% of conglomerate dollar growth stems from price increases. Overall, indie brands are growing across all beauty categories even though conglomerates still own the lion’s share.
The wake-up call: the agnostic model
These numbers show how consumer behaviour has shifted, from relying primarily on the Maybelline, Dior or Chanel of the world to expecting renewed brand diversity. In the meantime, Sephora and Ulta Beauty had trained consumers to expect a free-flowing, agnostic experience with open shelves, product testers, expert advice, and constant discovery of emerging names. Even though department store beauty counters, managed by brands, cannot replicate this agnostic model, transforming traditional models into more open, experiential spaces has become a growing concern. So far, however, the question has been more about how to best adapt to this trend than about transforming the floor and the business model.
Falabella is a regional leader, with an average selective market share of approximately 50% across Chile, Peru and Colombia, leading in the fragrances, makeup, and skincare categories. Yet this traditional method of measuring brand power masked a strategic vulnerability. For sure, the department store was capturing significant rental income and foot traffic. But by acting more like a landlord rather than a retailer, the department store was giving customer relationships, brand curation, and trend agility to brands and other beauty retailers. So the risk was losing beauty market share and the younger, trend-engaged consumers most likely to drive the next years of retail growth, as Gen Z is the generation most structurally aligned with indie and new brands. Instead of merely adapting, Falabella gave a structural and strategic answer with Beauty F, facing the challenge of giving up the traditional rental and safer model.
The context of the local cosmetics market reinforced the potential for a beauty rethink. The Chilean beauty market reached US$443 million in 2025, projected to grow by over 10% by 2035. On its side, with a market reaching US$418 million in 2025, Peru maintains an estimated annual growth rate of 6-8%, driven primarily by the dynamism of the skincare and makeup segments. Colombia’s US$264 million market is expected to grow by over 4% by 2035.
Building a beauty retailer from within: Falabella's Beauty F and Glow Bar
Curation, staff and ownership: a beauty retailer built from scratch
Rather than awaiting the arrival of Sephora (both a recurring expectation and a threat to other beauty retailers), Falabella designed and built its own specialist beauty formats, operated fully in-house, on its own terms: Beauty F in Chile and Colombia and Glow Bar, a local adaptation for Peru.
Both formats share the same architecture: an enclosed space within a Falabella department store that functions as a standalone retail business rather than a leased corner or a collection of brand concessions.
A few ownership-based principles distinguish the model from the rest of the department store beauty floors:
- Closed space with a single-entry point.
- Open-shelf layout integrating testing stations, intuitive navigation, and on-floor advisory zones.
- Own sales force, with all staff across every Beauty F and Glow Bar location being Falabella employees, trained beauty specialists, not brand-supplied promoters with competing loyalties.
- Own imports with Falabella dealing directly with brands, importing and curating a much wider and faster-rotating selection.
- Private brands fully controlled by Falabella.
- Focus on younger, trend-driven, celebrity brands with Beauty F opening with over 100 brands across skincare, makeup, fragrances, hair care, and dermo-cosmetics, including a dedicated K-beauty section. Critically, 80+ new brands have been added since launch, of which 15 were first-time entrants to the Latin American market. Hero names, Rare Beauty, The Ordinary, Drunk Elephant, coexist with emerging labels discovered through social media trend cycles.
- Flexible assortment and presentation, as in some cases, legacy brands like MAC have been moved inside the Beauty F space, with the rationale that the concept avoids replicating items (each SKU is either inside Beauty F or in the rest of the beauty floor, not in both). Most brands offer no personalisation, but some, like Fenty, have a branded presence inside.
While Falabella still has traditional beauty counters, this model is that of a specialist retailer, implying additional complexity of managing different business models. Additionally, developing Beauty F is part of Falabella’s strategy to become a specialist in beauty, sports, home equipment, and fashion (particularly with its private labels), through separate business units and P&Ls.
Experience design as a commercial tool
The decision to enclose the space is experiential and commercial, not only operational. A high-touch beauty experience runs on a different register than the rest of a department store floor. Spanning 80 to 250 sqm, depending on location, Beauty F is designed around different sensory dimensions: its own soundtrack, distinct from the ambient store environment; a signature scent that creates a fragrance customers associate with the format; and warmer, more theatrical lighting, consistent with prestige beauty standards.
A single monitored entry point signals the transition into a different, specialised space. It also addresses a critical operational reality: beauty is among the most shrink-exposed categories in retail. A controlled threshold is both a material loss-prevention tool and an experience marker.
Proof of concept: what Beauty F has delivered so far
Beauty as a win-back and recruitment engine
One of the most commercially significant Beauty F successes is re-engaging customers who had been absent from Falabella stores for more than 12 months. The customer profile that Beauty F is attracting is 85% female and around 20% aged 18-35, a cohort that has largely abandoned the traditional department store beauty experience. Overall, as Falabella reported to the IADS, the share of young customers and new customer acquisition both doubled since the format launched, and new brands introduced through the format are contributing significantly more than the legacy assortment. The average basket is CLP40,000 ($43, approximately two products per transaction), indicating an engaged purchase rather than a transactional visit. Finally, e-commerce already accounts for a significant share of the Beauty F business.
The speciality beauty format is functioning as a CRM tool, reactivating dormant customers and introducing new demographic segments to the Falabella ecosystem. At a time when customer acquisition costs are escalating and loyalty is increasingly fragile, the ability to generate new visits and convert them is a powerful argument to justify the investment the format requires.
From pilot to platform: from one to 15 locations in nine months
Falabella set Beauty F up as a separate, startup-like company with its own leader and staff. When they opened Beauty F inside Parque Arauco in November 2025, it was presented as a cosmetics and personal care shop-in-shop format, a specialist zone within the department store. In July 2026, Beauty F had 10 stores across Chile and Colombia, with 9 more coming; Glow Bar had 5 in Peru, with 4 more coming, targeting upper-market segments where there is no Falabella store presence. This pace of expansion from zero to fifteen locations in under nine months is possible because the group retains full operational control. The specialist model, kept fully in-house, scales on the group’s own timeline. Falabella sees the standalone ambition as a natural evolution of the project. As a result, a standalone Beauty F is no longer a feature of the department store; it is a competitor in the speciality retail market, occupying the same category space as local beauty retailers such as Aruma and Dermotienda, two of Peru’s most important beauty retailers. This trajectory poses a direct question: when does an internal speciality format become a spinout competitor to the very department store to the point where it could cannibalise the traditional beauty floor? Beauty F is believed to have the potential to transform beauty for Falabella. By becoming a standalone beauty brand, Beauty F is expected to strengthen the traditional beauty floor, benefit the department store’s overall ecosystem, and create a precedent for its international peers.
The operational friction behind Beauty F's early success
Even successful, the new beauty format comes with operational challenges. CapEx intensity is high due to investments in fixtures and architectural elements, which decreases profitability and limits scalability. A lighter CapEx version is needed to extend the concept without diluting returns. With no comparable historical baseline figures, inventory management and forecasting at launch have been a challenge. In addition to the inventory-related financial burden, stock-outs at the time of opening damaged both the customer experience and commercial performance. Beauty F’s curation is oriented toward selective and prestige brands. Meanwhile, high-frequency, convenience-driven categories such as dermo-cosmetics are underrepresented, creating a missed opportunity to increase frequency, an assortment question for the next openings. Finally, even though the enclosed format reduces retail crime, the smallest and highest-value SKUs still require dedicated product-level staffing, adding costs.
Beauty F and Glow Bar are an argument about ownership of space, customer relationships and brand curation. The early results support the premise. Dormant customers are returning, younger demographics are engaging, new brands are performing above expectations, and formats are expanding at a pace few in-house retail projects achieve. Yet Falabella is not the first department store to pursue a beauty spin-off strategy and claim success for it. In 2020, Harrods launched H Beauty, a new concept of standalone beauty boutiques designed to attract younger customers and to claim territory before Sephora entered the market in 2023. Six years later, results are mixed, as exemplified by the absence of new openings and the recent Bristol store closure. The UK beauty market is certainly crowded with department stores and multi-brand retailers such as Space NK, Boots, Lookfantastic, Superdrug, Cult Beauty and Sephora. But also, H Beauty did not transform the beauty model as it mostly operated as a smaller department-store beauty floor with branded boutiques and a multi-brand attempt, mixing own-bought brands and concessions. Functioning as a startup company with its own staff, store concept and merchandise, Beauty F is about transformation. If Falabella’s bet proves right, Beauty F could be more than a retail success story. It could be a renewed way of selling beauty and, for a legacy department store, a beacon of retaining leadership in the beauty category.
Credits: IADS (Christine Montard)
IADS Exclusive: Homegrown AI and intelligence department stores should own
IADS Exclusive: Homegrown AI and intelligence department stores should own
AI capability is becoming more accessible, while the cost of production systems depends on the models, context, tools, loops and human review required by each workflow. For department stores, advantage will come less from access to a model than from control of the data, definitions, customer relationship and judgment that make its output useful.
Boston Consulting Group’s June 2026 analysis describes AI intelligence as increasingly scalable and accessible. Its July 2026 cost framework exposes the other side of that shift. Agentic systems may retrieve documents, make several model calls, use tools, carry context across steps and repeat actions before an output is accepted. Human review and correction add another layer of cost. Access to intelligence is getting cheaper while the cost of an accepted outcome can remain variable and difficult to predict.1
That tension matters because the cheapest model call does not necessarily produce the cheapest useful result. The relevant cost is what the store spends to reach an answer a buyer or a merchandiser can act on without sending it back. It also shifts the strategic decision from model access to organisational control. The store must decide which data enters the workflow, which commercial definitions it uses, how its output is evaluated, who can override it and whether the customer relationship remains with the store.
The argument for “homegrown” AI begins there. Homegrown AI can combine external models, private cloud and selected local infrastructure. What the department store retains is the business logic beneath those systems and the option to run workloads locally when economics, sensitivity or control justify it.
What homegrown AI means
From token cost to business value
For a department store, the bill that matters is the cost of an accepted outcome. BCG proposes measuring the economic return from an AI outcome against both the tokens consumed and the human effort required to initiate, review, correct, approve and operate the workflow.
Model price alone is therefore an incomplete guide. A more capable model that answers a buyer’s stock query correctly the first time can cost less than a cheaper one that takes three attempts and a merchandiser’s correction. For high-volume routine work, such as tagging product copy, the cheaper model usually wins. The comparison has to be made on the whole task, at the required quality, speed and level of risk.2
The three kinds of AI spend also behave differently on the profit-and-loss account. Building a reusable merchandising assistant is closer to an investment, running internal reports is an operating expense, and customer-facing inference behaves more like a cost of goods sold, rising with every conversation. Treating all three as one technology line hides where AI protects margin and where it quietly consumes it.
Reducing the time required to prepare a trading report does not automatically create value. The return appears only when the saved time changes a commercial decision: earlier action on inventory, more time with suppliers or better service. If the buyer still places the same order on the same day, the only thing that improved is the report.
Owning the intelligence layer
BCG’s token-competition argument weakens the case for treating access to a foundation model, a general-purpose model supplied by an external provider, as a lasting source of advantage.
For a department store, the part a supplier cannot bring is the store’s own meaning. Available inventory has to account for merchandise moving between locations. Concession sales have to be attributed consistently across the store, department and brand. Returns have to be read differently when they signal poor fit, product quality or a commercial problem. Those definitions shape what buyers, merchandisers and store teams can do with an AI answer. A general model arrives without them, and no supplier can supply them. Paolo Pedersoli of Jakala made the same argument at the NRF Big Show 2026, in a session titled “AI without semantic capital is of no use”: as powerful models and generic data become widely accessible, the scarce asset is an organisation’s own codified definitions and decision logic, made machine-readable rather than left as tribal knowledge.3
BCG’s 10–20–70 framework, which Forbes reported the consultancy was urging in a January 2026 report on agentic AI, assigns around 10% of AI-transformation effort to algorithms, 20% to technology and data and 70% to people and processes4.
Model location and organisational control are separate decisions, but location still carries consequences. For stable, high-volume workloads on controlled data, local infrastructure can offer tighter custody of sensitive information and greater cost predictability. It also brings hardware utilisation, energy, engineering, security and replacement costs. External models avoid much of that infrastructure burden but introduce dependence on provider pricing, interfaces and governance.
The trade-off is workload-specific. High-volume, stable work on sensitive data, such as enriching product records or answering associate policy questions across the estate, is the kind that can justify local infrastructure. Occasional, bursty or experimental work rarely does. In both cases, the commercial definitions and evaluation standards should remain portable enough for the store to change the technology underneath them.
The operating model beneath the technology
When AI scales the wrong process
An IADS member provides a department-store example of AI built around explicit ownership of the underlying information. At a recent E-commerce Directors Meeting, the department store described moving ownership of data quality from IT to its e-commerce specialists, pairing AI enrichment tools with human validation: the enrichment tools produced usable attributes only once the people who trade the products owned the definitions behind each attribute. The reported improvement in search and conversion followed that change in ownership and human validation alongside AI enrichment.
BCG found that the organisations producing stronger returns were redesigning end-to-end processes, concentrating on a limited number of high-value applications and tracking whether the gains reached the profit-and-loss account. Adding AI to an unchanged process may increase speed while leaving conflicting definitions, unclear ownership or badly designed incentives untouched. The NRF Big Show 2026 department-store panel drew the same line between AI applied to legacy systems and AI-native design, citing a 90% reduction in the cost of product data management as the kind of gain that follows only when a process is rebuilt rather than accelerated.5
A report assembled from incompatible systems can still produce conflicting answers. Product information can be returned quickly while remaining incomplete or inconsistently governed. A workforce system can reduce scheduled labour against a target that damages service. In each case, execution improves before the organisation has agreed what a good result means.
Starbucks provides a separate warning from the wider retail sector. Reuters reported that the company rolled out automated inventory counting across more than 11,000 company-operated North American stores in September 2025 and discontinued it in May 2026 after persistent misidentification and missing items forced employees to check or repeat its work.6
Reuters’ January 2026 reporting places those failures inside a supply chain already affected by fragmented suppliers, outdated systems, forecasting problems and limited store storage. The counting errors created new verification work for employees, while the fragmented suppliers, forecasting problems and storage constraints remained untouched. Nine months of automation had changed the counting process without resolving the supply chain beneath it.
Where build-or-buy moves the work
In Korea, Lotte shows why build-or-buy is the wrong binary. The department store used Strategy’s commercial technology but deployed eight analytics agents on a governed semantic layer applying common definitions across departments. Strategy reports more than 9,500 AI-supported analyses and answers delivered up to ten times faster in six months.7
Lotte answered the technology question by buying and was left with the harder half. The definitions its eight agents run on had to be written, agreed and policed inside the business, and they now live on a supplier's platform, which is where portability has to be defended rather than assumed. Buying a model or platform does not remove the work of deciding what inventory, sales, customers and performance mean.
Department stores should vary a system’s authority according to the consequences of an error and the amount of human interpretation the task requires. Product and policy retrieval can tolerate more automation because the answer can be checked against an approved source. A buying recommendation that changes an order still needs the buyer who understands the category and trading context. A staffing recommendation needs a store manager able to judge the service consequence.8
Recruitment, promotion, discipline and worker monitoring carry still higher stakes. The EU AI Act, which IADS identified as a governance framework for retail in its 2024 analysis of AI accountability, reflects that higher threshold by classifying specified employment uses (recruitment, promotion or termination, certain task-allocation systems and worker monitoring) as high-risk, subject to the regulation’s conditions and exceptions. AI may organise evidence and identify inconsistencies, but accountability for the final decision must remain with qualified people.
At the NRF Big Show 2026, the IADS panel on what AI can and cannot do for department stores placed governance at leadership level rather than inside IT alone. Data quality and taxonomy were identified as foundational constraints, while the complexity of product assortments and databases was singled out as an opportunity for automation. The warning was equally clear: efficiency gains should not be converted into cuts to sales staff or store investment but redirected towards customer experience and differentiation. The 2024 IADS Exclusive Navigating the AI maze in retail beyond the black box argued for proportionate oversight concentrated on high-risk areas, and for AI that supports rather than replaces human judgment.9 The authority given to the system should fall as the commercial, human or legal consequence of being wrong rises.
The customer relationship is part of the infrastructure
Distribution without disintermediation
The internal intelligence layer is only one part of AI sovereignty. The other sits between the department store and the customer. At NRF 2026, futurist and author Jason del Rey described AI platforms moving beyond product research towards transactions, with conversational interfaces experimenting with completing purchases inside the chat rather than sending customers to the retailer’s own website. He treated the shift as under way rather than settled. His practical conclusion was narrower than the threat: experimenting on external platforms is worth doing so products remain discoverable, but the priority is making the store’s own digital experience at least as good as the assistant’s. He described abandoning a retailer’s own site and getting a faster, more accurate answer from ChatGPT.
IADS members had already identified the underlying issue at the 2025 E-commerce Directors Meeting. Across their different app and omnichannel strategies, participants agreed that owning the primary digital doorway mattered to protecting brand equity and margins against marketplace giants. NRF added another layer. IADS summarised REI chief executive Mary Beth Laughton’s approach as “selective openness”: participating in external AI platforms while deciding which content, data and expertise remain exclusive to the retailer’s own channels.
The completed order tells a department store what the customer bought. The conversation that preceded it can contain the occasion, budget, preferences, rejected alternatives and future intent. If an external agent keeps that context and sends the store only an order, the richer part of the customer relationship sits outside the business.
Walmart offers one response. The March 2026 Forbes analysis describes the company placing its own assistant inside external interfaces while retaining more of the customer journey and checkout. The relevant lesson for department stores is control over continuity: an outside platform can introduce the customer, while identity, consent, loyalty history and the ability to continue serving that customer remain with the store.10
Selective openness buys reach by surrendering some control over discovery. The strategic choice is what the department store is willing to distribute and what it still needs customers to return to its own channels to receive. Based on IADS’s e-commerce and NRF report, IADS’s position is that department stores should use external AI agents as distribution channels without allowing them to become the permanent owner of the customer relationship.
What a general platform cannot reproduce
Physical and digital relationships remain intertwined for younger consumers. Edelman Gen Z Lab’s 2024 Rarely Heard Voices research found the cohort divided between enthusiasm and resistance towards AI. Seven in ten Gen Zers reported fact-checking online information even while shopping, while 49% of older Gen Zers preferred making purchases in stores and 40% of 14- to 17-year-olds shopped equally online and in store.11
The research also describes a “trust loop” in which brand action, advocacy and continued purchasing reinforce one another. That relationship extends beyond a single conversion.
Product comparison is where a general AI platform is strong. City-level presence, an alterations counter and a relationship built over several buying seasons sit outside its reach, and as more product discovery moves into AI interfaces, those capabilities carry more of the reason a customer chooses the department store itself.
The workforce is part of the intelligence layer
AI does not create expertise
Much of the knowledge that makes a department store function is not captured in its databases. It sits in how buyers interpret the relationship between sales and returns, how store managers balance labour targets against service requirements, and how associates adjust their approach to different customers. That judgment accumulates across products, seasons, trading cycles and exceptions. Transactional data records what happened; the experience of the people around it often explains why it happened and whether the same response should be used again.
A controlled experiment at IG Group, a financial-services company, helps isolate the role of domain knowledge. The study involved 78 employees divided among experienced writers, marketing specialists with adjacent knowledge and technologists more distant from the task. AI helped the adjacent specialists close much of the gap with experienced writers, but it did not turn employees without the relevant domain knowledge into experts. The researchers described an “AI wall”: the further users were from the required knowledge, the less able they were to evaluate and improve the output.12
Although the setting was not retail, the mechanism is relevant to department stores: employees still need enough underlying knowledge to recognise missing context, weak reasoning and commercially inappropriate answers. AI can accelerate people who already possess enough domain knowledge to judge the result; without that foundation, it risks increasing dependence rather than competence. The IADS NRF 2026 report reached the same conclusion from a retail perspective: Luc Julia, former co-inventor of Siri and Chief Innovation Director at Renault, and Pascal Malfoy, CEO of ADEO (Leroy Merlin), argued that AI does not remove the need for professional expertise, and that the strongest results come from combining domain knowledge with intelligent tools.
When production becomes faster, the scarce capability shifts towards judgment: whether a markdown recommendation suits the season, what trading context the model was never given, and who answers for the decision if it is wrong. Experience cannot be produced at the speed of a model response.13
The IADS 2024 White Paper on middle management treats reverse mentoring as one tool among several, alongside traditional and peer mentoring. That combination is particularly relevant to AI. Younger employees can bring familiarity with emerging interfaces and experimentation; experienced colleagues bring organisational memory, customer understanding and the ability to recognise exceptions. The IG Group experiment suggests why both matter: fluency with the tool did not compensate for distance from the underlying domain.
When efficiency consumes the apprenticeship
The workforce risk extends beyond adoption. It concerns what employees no longer learn once AI begins performing the work. First drafts, routine comparisons, straightforward customer requests, and low-risk recommendations can look expendable. They are also how people develop judgment: by doing work repeatedly, having it corrected and seeing the consequences of low-risk mistakes. Automating those activities without redesigning learning improves output today while weakening the organisation’s future expertise. Keeping some formative work in human hands also has a cost: the department store pays people to perform work that a competitor may automate. That choice should therefore be deliberate. The organisation needs to know which tasks are still buying experience, not merely labour.
BCG’s June 2026 study When everyone uses AI, companies risk losing critical skills, a global survey of 70 C-suite leaders and senior executives, found that half were already observing de-skilling, while more than 60% expected it to become a material threat within three to five years. The capabilities considered most exposed included judgment and decision making, problem understanding and framing, creative thinking, analysis and causal reasoning, and solution generation and evaluation, the same capabilities employees need when evaluating AI-generated work.14
The risk is especially relevant to department stores because much of their management and service capability has traditionally been developed through progression. Employees acquire judgment through customer-facing work, operational responsibility, recurring trading cycles and exposure to exceptions before moving into broader roles. The IADS 2024 White Paper on middle management describes a path in which sales associates could move through store management and potentially into director roles, gaining broader customer, operational, and commercial responsibility along the way. Centralisation and repeated reductions in the in-store management layer have already damaged succession planning and narrowed that traditional route into management.
AI can narrow it further by removing the lower-risk tasks and recurring exceptions through which employees learn to interpret evidence, make decisions under uncertainty and understand the consequences of being wrong. The risk is less that AI erodes leadership skills directly than that future managers assume accountability for work they have had fewer opportunities to perform and judge.15 When formative tasks are automated without being replaced by structured learning, an already fragile route from execution to expertise becomes narrower still.
A department store cannot rely indefinitely on experienced buyers and store managers to check AI output if it has automated the work through which the next generation of them would have been trained.
The recent IADS Exclusive, The $10 trillion management problem, reached the same conclusion from a management perspective. Technology reaches the shop floor through managers, yet manager engagement has fallen sharply, even as organisations expect those managers to translate AI into new working practices.16
The IG Group experiment, BCG’s de-skilling findings and Gallup’s evidence on manager support point to the same requirement for AI training. Shop-floor employees need more than familiarity with an interface. They need enough product and operational knowledge to identify a plausible but wrong answer, escalate uncertainty and reject output when the commercial context does not fit. A human in the loop adds little protection when that person lacks the experience or standing to challenge the system.
What department stores should build first
Start with governed knowledge
At NRF 2026, IADS reported a consistent message across several AI sessions: begin with a concrete business problem, clear objectives and the data required to solve it. Luc Julia and Pascal Malfoy argued for specialised, domain-specific applications rather than broad AI deployments, while the department-store panel identified product assortments, databases, data quality and taxonomy as practical areas where the sector’s complexity can be reduced.
BCG’s workflow framework and NIST’s AI Risk Management Framework add the evaluation discipline. BCG begins with a defined outcome, while NIST requires organisations to establish intended purpose, responsibilities, risks, measurement and continuing oversight. Applied to a department store, these principles favour a bounded and verifiable first project rather than a broad autonomous system.17
An associate-facing product-and-policy assistant fits those conditions. Three things already on the record point to it: the NRF department-store panel named product assortments, databases, data quality and taxonomy as the sector's most automatable complexity, the same panel cited a 90% reduction in the cost of product data management, and the quoted IADS member has shown that a department store can take ownership of that data layer without outsourcing it. It can answer questions about products, services, returns, delivery, appointments and approved procedures. Its answers can be grounded in approved product, service and policy information, the source can be shown to the associate, and unresolved questions can be escalated.
Lowe’s provides an adjacent retail example. Its Mylow Companion was deployed across more than 1,700 stores to give associates access to product, inventory and project information. A department-store version would have to accommodate the additional complexity of concessions, services, appointments, returns and store-specific policies.18
Preparing that knowledge is where the pilot becomes difficult. The IADS member treated data quality as a question of commercial ownership rather than a purely technical clean-up exercise, moving responsibility from IT to its e-commerce specialists and retaining human validation. The same issue would arise in an associate assistant: POS, CRM, inventory and product systems may disagree over whether an item is available, which department or concession owns the sale, or how a return should be classified. Store policies can also differ by service, market and location. The department store therefore has to decide which definition takes precedence, who owns it and how quickly an outdated answer is removed. None of this is free. Reconciling definitions, keeping formative work in human hands and staffing real oversight are costs the store carries before any savings appears, and they compete for the same budget as stores, people and logistics.
NIST requires systems to be tested before and during operation and reassessed against their intended purpose. For a first department-store pilot, that means testing the same set of real associate questions across the viable local, cloud, hybrid and non-AI options. The comparison should measure answer quality, response time, cost per accepted answer, escalation and manual correction, while also recording employee rework and variation across stores and languages.
Measure rework, not activity
The pilot should also test whether experienced employees consider the answers commercially useful, whether newer employees can explain why an answer is correct and whether the assistant builds understanding rather than conceals gaps.
Oversight should follow the retail decision itself, applying the NIST requirements set out above. An associate needs to see the product or policy source behind an answer and know when to escalate it. A buyer reviewing an AI recommendation needs the sales, returns and stock evidence behind it. A store manager needs the authority to reject a staffing recommendation that meets a labour target but leaves the floor unable to serve customers. Decisions affecting recruitment, promotion or discipline require stronger human control again.
Scale only the question types the pilot answered reliably, and leave the rest with people. The test of the pilot is whether associates keep using it once the launch attention fades, whether the cost per accepted answer is one the business would pay at scale, and whether the people supervising it can explain why an answer was right.
Owning the intelligence layer buys one thing above all: the freedom to replace the model.
A department store that keeps its commercial definitions, evaluation standards, workflows and customer identity separate from a supplier can move as the technology moves. It can adopt a better model, bring a sensitive workload closer to home or renegotiate with a provider without reconstructing the business around that decision. Once those assets are embedded inside one platform, switching becomes slower, more expensive and more dependent on the supplier.
Homegrown AI should preserve that freedom. Where a workload runs can change with economics, sensitivity and control. The product history, customer logic, evaluation standards and operating definitions that give the business its meaning must remain portable and under the department store’s control. The model can change. The department store should not have to rebuild itself around every change.
Credits: IADS (Maya Sankoh)
IADS Exclusive: Celine Dion, Taylor Swift, BTS: what landmark entertainment means for department stores
IADS Exclusive: Celine Dion, Taylor Swift, BTS: what landmark entertainment means for department stores
Nine million people registered for pre-sale tickets for Céline Dion’s September 2026 concerts. Compared with the total seating capacity across her 16-concert Paris residency, that’s nineteen wannabe attendees for every seat. That’s probably why, last April, Galeries Lafayette CEO Arthur Lemoine told French newspaper Le Monde that he expected a “significant positive impact” at the Boulevard Haussmann flagship this autumn.
His reasoning drew on a specific precedent: during Taylor Swift’s six French concerts in 2024 — four at the very same La Défense Arena, plus two in Lyon — Galeries Lafayette registered a measurable uplift in traffic. Lemoine specifically cited the impact of the Lyon dates reaching Haussmann, a remarkable observation given that Lyon is 470 km from Paris. If concerts in a different city generated spillover, the implication for 16 Dion concerts in the French capital itself is clear.
Lemoine’s comment was not wishful thinking. It was grounded in a pattern tracked across sporting events and entertainment phenomena over the past several years, and one that the data increasingly support: landmark cultural events function as demand shocks for premium retail, particularly for department stores positioned as destinations in their own right.
Céline Dion in Paris: fans’ hearts will go on
Céline Dion’s Paris residency is shaping up as one of the most significant entertainment events in Europe in 2026.
The residency comprises 16 concerts at Paris La Défense Arena (Europe’s largest indoor venue), spread across five weeks in September and October 2026. The total capacity is capped at approximately 30,000 per show (the arena holds up to 45,000, but production design limits seating), implying a total audience of roughly 480,000 concertgoers over the run. Over 9 million pre-sale registrations were recorded before the artist pre-sale opened on 7 April — a figure that signals massive unmet demand and, crucially, a large pool of international fans who will compete for hotel rooms, restaurant tables, and retail experiences. Six additional dates were added within 48 hours of pre-sale opening, on the back of what organisers described as “phenomenal demand.” Marriott Bonvoy is the official hotel partner, offering VIP experience packages — a direct indication that the event is structured to drive multi-day tourism stays, not just single-evening attendance.
The audience profile matters as much as the volume. Céline Dion’s fanbase skews older and more affluent than that of a typical pop tour. Her career spans nearly four decades; her peak commercial period — the mid-1990s to mid-2000s — means her core following is now aged 35–60, a demographic that aligns closely with the primary customer profile of flagship department stores: internationally mobile, with high disposable income, and inclined to frame travel around cultural experiences. This is further amplified by the emotional narrative of Dion’s return to the stage after years of public struggle with Stiff Person Syndrome[1], a rare neurological disorder — a story that has generated worldwide media coverage and deepened the event’s symbolic resonance. Over 200 million records sold worldwide make her the best-selling Canadian recording artist and the best-selling French-language artist of all time.
In the past, Céline Dion’s two Las Vegas residencies at the Colosseum at Caesars Palace (2003–2007 and 2011–2019) grossed a combined $681 million (€578m) in ticket sales and attracted over 4.5 million spectators across 1,141 performances. Her second residency averaged $693,000 per show (€588,000). That Las Vegas track record demonstrates that a stationary artist can serve as a sustained tourism magnet, generating consistent demand for hospitality, retail, and dining over multi-year periods[2].
What Swiftonomics already taught us
The “Swiftonomics” phenomenon is documented (read the 2024 IADS Exclusive here), and provides the most granular evidence base for projecting the retail impact of the Céline Dion residency — all the more so because Taylor Swift performed at the very same venue.
Taylor Swift played four concerts at Paris La Défense Arena in May 2024, launching the European leg of her Eras Tour, followed by two additional shows in Lyon in June. Around one million people registered for tickets in France. Arthur Lemoine’s specific reference to the Lyon dates generating a measurable impact at Haussmann — despite Lyon being 470 km away — suggests an additional echo in Paris, beyond the four La Défense shows. As a consequence, the potential impact of Celine Dion’s concerts might be at two levels: a direct effect from Paris concerts, as demonstrated by the Taylor Swift concerts, and a spillover effect from unmet demand, as demonstrated by the distant Lyon dates[3].
Globally, the Eras Tour (2023–2024) grossed approximately $2.2 billion (€1.9bn) in ticket revenue across 149 shows worldwide and generated an estimated $7 billion (€5.9bn) in total retail economic impact across North America, according to Chain Store Age. It is estimated that the total economic footprint — including indirect spending by non-ticket holders drawn to the cultural moment — likely exceeded $10 billion (€8.5bn).
The per-show economics are striking. In 2024, North American concertgoers spent an average of $1,572 (€1,335) per show for the full experience (tickets, travel, lodging, outfits, merchandise, food and beverage), up 21% from $1,303 (€1,107) in 2023. 64% of Eras Tour attendees made concert-related purchases in categories including apparel, footwear, accessories, cosmetics, and crafts.
At the city level, the pattern was consistent across virtually every stop. In the U.S., Pittsburgh saw $46 million in direct spending from two concerts (€39m), with 83% of attendees coming from outside the county and hotel occupancy reaching 95%. Chicago set an all-time hotel revenue record of $39 million (€33m) during one concert weekend. Denver’s two shows added $140 million (€119m) to Colorado’s GDP. Los Angeles saw $320 million (€261m) in total economic impact from six shows, with 3,300 temporary jobs created. In the UK, Swift’s shows were estimated to boost London’s economy by £300 million (€344m) and Edinburgh’s by £77 million (€89m). In Ireland, concert-related spending increased by 88%.
What K-pop also suggests
Asian department stores have developed the most sophisticated playbooks for converting concert traffic into retail revenue, driven by the economic power of K-pop fandoms.
BTS — Seoul, March 2026
BTSnomics 2.0, as the Korean press has cheerfully named it, is exactly the playbook European department stores now need to study.
According to Inside Retail Asia, following BTS’s comeback concert at Gwanghwamun Square (21 March 2026), department store sales surged by over 40% during the comeback week. Duty-free merchandise sales rose by up to 430%. Brands endorsed by individual BTS members saw improved sales, such as Calvin Klein (endorsed by Jungkook). Five-star hotels near Gwanghwamun sold out entirely, with rates reaching ₩1.5 million (€865) per night. The economic impact of the single Gwanghwamun concert is estimated at approximately $177 million.
Korean department stores prepared proactively and systematically. Lotte Department Store launched discount events for foreign passport holders at its Myeongdong and Jamsil branches from 19–29 March, coordinating with online travel platforms to issue 5% discount coupons. Hyundai Department Store transformed The Hyundai Seoul into a “K-pop sanctuary,” with monthly pop-ups for idol group merchandise starting with EXO and ENHYPEN, a K-culture experience zone for foreigners, and a foreigner-exclusive integrated membership programme (“H.Point Global”). Hyundai had also been developing packaged products that linked hotels, shopping, exhibitions, and experiential content for foreign tourists for a few years already.
BlackPink — Hong Kong, January 2026
The K-pop group’s three-night “Deadline” world tour finale at Kai Tak Stadium drew over 356,400 mainland Chinese visitors to Hong Kong over one weekend — a January record. Hotel occupancy near the venue exceeded 90%, with some properties charging over HK$7,000 per night (€760). Retailers in the Kai Tak area, including SOGO, reported an uptick in both concert-related merchandise and general tourism goods. Industry leaders called on authorities to develop more systematic celebrity tie-ups as a tourism lever.
The “ticketless economy” model
Analysts tracking BTS have noted that many fans travel internationally to concert cities without tickets, simply to participate in the cultural moment — spending on hotels, food, fashion, and experiences. This pattern of “ambient consumption” around a major event is exactly what Galeries Lafayette could also bank on. With 9 million registrations for Céline Dion’s 480,000 available seats, the ratio of unmet demand to supply virtually guarantees a significant pool of non-ticket-holding visitors in Paris during the five-week residency window.
What Paris 2024 Olympics actually did to sales
IADS benchmarked the retail impact of recent major sporting events, including the London 2012 and Paris 2024 Olympics. The Paris Games, in particular, provided a real-world case study for understanding how large-scale events affect department store performance.
During the Games (29 July – 11 August 2024)
In France, national FMCG sales rose 2.7% in value — a swing of 3.8 percentage points against the January–July trend of -1.1%. The effect was amplified in proximity to competition sites. Décathlon’s flagship in Paris Madeleine saw a 28% increase in footfall; its Villeneuve-d’Ascq campus near Lille registered 22% more visitors. Carrefour’s central Paris convenience stores recorded a 25% increase in sales, with mascot sales tripling initial estimates to over 560,000 units. The sports equipment category surged by 7.2% in supermarkets, against a year-to-date decline of 17.2%. Analysts found that weather accounted for only 18% of volume growth in Paris and 37% nationally; the remainder was attributable to the event itself and the influx of tourists.
However, for department stores, the story was more nuanced. Galeries Lafayette had initially budgeted for a 5–10% dip in summer sales due to traffic restrictions and disruption. In practice, the impact was less severe: July was down but above expectations, and August was “almost flat.”
September–December 2024 — the “post-Olympic glow”
The real benefit came after the closing ceremony. As Arthur Lemoine confirmed in a November 2024 interview with WWD, September saw “high growth” as tourists charmed by the television spectacle of the Games came to discover — or rediscover — Paris. October sales at Haussmann rose 15% year-on-year, powered by a mix of domestic and international customers. The store was on track for its 4% annual growth target, and Lemoine expressed confidence in Christmas trading. The Banque de France, in its September 2024 note, attributed an estimated 0.25 percentage points of GDP growth in Q3 2024 to the Olympic effect, with market services (hospitality, retail, dining) identified as the principal contributor to the rise.
The lesson is that the greatest retail benefit from a cultural event often comes not during the event itself but in the weeks and months that follow, as the city’s enhanced visibility translates into sustained tourism. The five-week Céline Dion residency (September–October) is ideally timed to generate precisely this kind of post-event tail into the critical Q4 trading period.
So what should department stores actually do?
Based on various IADS studies conducted for its members, we identified three phases of action.
Before the event
The preparatory phase is where most of the commercial upside is either locked in or lost, and its defining discipline is lead time.
Experience from previous large-scale event activations suggests that assortment development and influencer programming need to be underway several months before the event itself — the window in which pre-orders, demand signals, and inventory planning can still be meaningfully shaped:
- The product assortment is the first lever: co-branded capsules or exclusive products developed with brands already aligned with the artist’s aesthetic tend to outperform generic event-themed merchandise because they link the store to the cultural moment without encroaching on the artist’s own merchandising operation.
- The same logic applies to marketing. Campaigns routed through sports or music influencers tend to reach audiences already aware of the event, whereas fashion influencers pull style-conscious consumers into the conversation and meaningfully expand the addressable market. Co-branded activations with partner brands consistently outperform standalone retailer campaigns, which can confuse customers when run alongside brand partnerships. For effective activations, department stores are therefore better served by partnering with brands already in the event’s orbit than by constructing a standalone event-themed identity.
The second lever is cross-category thinking: a landmark event ripples well beyond the obvious merchandise. Electronics (as audiences upgrade their viewing and listening setups), spirits, fragrances, and watches tend to see a lift around cultural moments of this scale, and a department store’s structural advantage over specialist retailers lies precisely in its ability to capture that spend across categories within a single visit.
Foreign-visitor infrastructure is the third axis: multilingual signage, visible tax-free shopping, and passport-linked promotions, following the Korean playbook in which Lotte and Hyundai coordinated directly with online travel platforms. Hotel partnerships close the loop — in the Dion case, Marriott Bonvoy, the official hotel partner, is the natural conduit for embedding store visits into VIP concert packages before guests ever arrive in Paris.
During the event window
Once the residency is underway, the commercial question shifts from attracting the audience to capturing the share of its spend that would otherwise disperse across the city.
The most direct lever is repositioning the store itself as a pre-show destination, reinforced by extended opening hours on concert evenings and by targeted digital advertising to ticket-holders — geotargeted, social, and routed through hotel concierge partnerships, with the Marriott Bonvoy tie-up as the obvious anchor in the Dion case. In-store gathering spaces play the same role the Korean “K-pop sanctuary” format plays around BTS comebacks: livestream viewing areas, themed activations, and photo opportunities that convert ambient fans — many of them without tickets — into dwell time on the sales floor. Assortment should follow the same logic as the preparatory phase: concert-adjacent categories (fashion, beauty, accessories, fragrances) that capture the mood without trespassing on the artist’s official merchandising operation. Food and beverage is the underappreciated driver. Prior IADS work around major sporting events has repeatedly identified F&B as a critical traffic generator and dwell-time extender, and the logic transfers directly to concert nights: pre-show dining experiences, themed cocktails, and post-concert gathering spaces are the mechanisms through which consumer spend is retained within the store rather than surrendered to surrounding restaurants and bars.
After the event
The post-event phase is where the largest long-term opportunity sits, and it is also the phase most often under-exploited.
The Olympic precedent is instructive: Galeries Lafayette’s September–December 2024 performance — with October sales at Haussmann up 15% year-on-year and the store on track for its 4% annual growth target — demonstrated that the “glow” generated by a landmark event can be materially more valuable than the event window itself, because the city’s enhanced international visibility continues to convert into tourism long after the crowds have dispersed. Sustaining that momentum is a function of deliberate programming rather than passive benefit: cultural activations, seasonal campaigns, and continued international marketing that keep Paris in the global conversation are what turn a one-off spike into a multi-month tail. The timing of the Dion residency is, in this respect, unusually favourable. Its September–October window hands department stores a three-month runway into Christmas trading — arguably the most commercially sensitive quarter of the year — during which the residual international attention can be harvested against the sector’s highest-margin calendar.
The counterpoint: when events disappoint
Not all landmark events deliver for retail. When studying the London 2012 Olympic Games, we realised that central high-street footfall declined in the first week as regulated traffic lanes diverted consumers away from commercial areas — which, to be fair, no London retailer had budgeted for. According to Transport for London, about one-third of Londoners changed their travel habits, and road traffic was cut by approximately 15%. As people avoided hotspots, central London high streets were quieter than expected. Sunday trading hours were extended, but many retailers absorbed higher staff and energy costs with minimal return. The British Retail Consortium reported that retailers’ hopes of an Olympic spending boost “were dashed as shoppers stayed away from the high street and enjoyed the sporting spectacle from their armchairs.” British online sales fell by 11% in August 2012, as consumers watched sport instead of shopping. Even with some customers switching to physical retail, the revived enthusiasm failed to lift sales volumes.
Business travel also dries up. In a September 2025 interview, United Airlines CEO Scott Kirby called the Olympic Games a 'net negative' for airlines: business travel to host cities comes to a standstill because executives cannot find hotels and want to avoid crowds, while the additional leisure flights airlines add are not enough to offset the lost high-yield corporate revenue. He was speaking ahead of the 2026 Milan-Cortina Winter Olympics and the 2028 Los Angeles Summer Games.
The notable exception was John Lewis, which reported an 11.2% uplift in year-on-year sales in the week building up to the Olympic opening ceremony. Electricals and home technology grew 32.5% as consumers purchased screens and devices to watch live events. John Lewis also reported a 14.5% rise in total sales the week after the Games ended — an early example of the “post-event glow” that Galeries Lafayette would later experience at scale after Paris 2024.
The critical variable across all these cases is location and accessibility. The London 2012 experience was negative for retail in part because Games Lanes physically disrupted the consumer journey to stores. In Paris 2024, Galeries Lafayette’s Haussmann location sat outside the security perimeters and maintained normal pedestrian and cyclist access throughout — and benefited accordingly. For the Céline Dion residency, the risk profile is even more favourable: the La Défense Arena sits in the western suburbs of Paris, meaning central Paris retail will face no access disruption whatsoever, while capturing the overflow of visitors staying in the city, dining, shopping, and extending their stays beyond concert evenings.
Céline Dion in Paris, Taylor Swift across Europe, BTS in Seoul, BlackPink in Hong Kong, and the Paris Olympics are not discrete episodes but instances of a structural shift in how discretionary consumption is organised: increasingly around cultural moments rather than against a flat calendar. The implication for department stores is that the capacity to plug into that calendar — to identify the right events eighteen months out, to align assortment, marketing, and F&B around them, and to extend the commercial tail into the quarters that follow — is becoming a durable competitive capability in its own right, rather than a one-off marketing exercise. Those that build this capability systematically will convert each landmark moment into both an immediate uplift and a compounding reinforcement of their position as destinations; those that treat each event as a standalone campaign will continue to capture a fraction of what the data show is available. The Dion residency is, on that reading, less an opportunity than a test of whether the sector has absorbed the lessons of the past three years and is ready to operationalise them at the pace the cultural calendar now demands.
[1] Stiff-person syndrome (SPS) is a rare neurological disorder. Symptoms may include stiff muscles in the torso, arms, and legs, and greater sensitivity to noise, touch, and emotional distress, which can set off muscle spasms.
[2] Before Céline Dion, Las Vegas residencies were associated with artists on the downside of their careers; she redefined the format at the peak of hers, paving the way for the modern era of mega-residencies.
[3] With Céline Dion’s 16 dates representing four times Taylor Swift’s Paris engagement at the same venue, and with over 9 million pre-sale registrations versus approximately one million for Swift in France, the scale of both direct and spillover effects should be substantially larger.
Credits: IADS (Selvane Mohandas du Ménil)
IADS Exclusive - The transparency trade-off: pricing, loyalty and regulation
IADS Exclusive - The transparency trade-off: pricing, loyalty and regulation
Dynamic pricing deserves attention now because three developments have converged. Artificial intelligence has made individualised pricing accessible, allowing for the possibility of a different price for every consumer. The growth of e-commerce has supplied both the behavioural data and the repricing infrastructure to act on it. Meanwhile, regulation is beginning to take shape, and the rules that will govern individualised pricing are being written before most retailers have decided where they stand.
As individualised pricing spreads, the question for department stores is not whether to run a data operation — they already run one, through their loyalty programmes, apps and data partnerships — but what to do with it. Two answers follow, and only one is defensible. The first is to point that operation at customers the way big tech does, personalising prices to extract the most each will pay but its failure mode is defeat by big tech itself. IADS argues that the second is to run the same machinery under a public commitment that it will only ever move a customer's price downward, and to make that transparency the differentiator.
The taxonomical pricing debate
The fundamental source of confusion in the contemporary pricing debate stems from the conflation of four concepts by media, regulators, and retailers. That many retailers have never resolved the confusion inside their own organisations is why so few can take a clear position on it. Algorithmic pricing, often powered by AI and machine learning, recalibrates prices across any combination of factors including, but not limited to, demand, competitor data, seasonal patterns, supply costs, and customer behaviour. NRF contends that this is simply the digitised and accelerated version of what retailers have always done manually.
Algorithmic pricing spans a spectrum in terms of data input, transparency, and degree of personalisation. Dynamic pricing lies on one end, differential pricing somewhere in the middle, and personalised (or surveillance) pricing on the opposite end:
- Dynamic pricing is the real-time adjustment of prices based on immediate demand signals, inventory levels, or competitor pricing. It is market-facing, with prices fluctuating for everyone based on these conditions, not depending on the specific customer. Given its scale of digital and infrastructure capabilities, Amazon reportedly made over 2.5 million price changes per day as far back as 2013. The business models of airlines, hotels, ride-hailing apps, and fuel retailers are based on dynamic pricing.
- Differential pricing refers to charging different customer segments different prices such as seniors' discounts, student rates, and trade pricing. This is legally well-understood as it price discriminates based on market-facing customer characteristics.
- Personalised pricing (also called surveillance pricing or individualised pricing) is the most contested variant. It uses personally identifiable data such as browsing history, location, credit score, purchase history, and mouse-movement patterns to infer each individual customer's maximum willingness to pay and price accordingly. Fordham Law professor Zephyr Teachout, explains it as using "the same data infrastructure that social media uses to sequence feeds, only here the information doesn't determine what someone sees but what they pay" The aim is to charge each buyer the most they can be induced to pay rather than a single market price.
The mechanism of individualised pricing
While modern dynamic pricing is proliferating across online storefronts, it is increasingly operationalised in physical stores, with the same interlocking technologies – in-store and online price labels, AI systems, and consumer data pipelines - enabling both. In either channel, the shopper's inability to observe the mechanism is engineered in rather than incidental.
In-store, electronic shelf labels (ESLs) are the enabler. The digital displays remove the need to manually re-sticker shelves, allowing prices to change in real time across an entire store silently, and leaving no record a shopper can inspect of what an item cost an hour earlier. While NRF argues that ESLs exist primarily for price accuracy and consistency, and to reduce compliance risk, rather than as a vehicle for surge pricing, they are also vehicles of enabling dynamic pricing when combined with backend analytical modelling, enhanced by AI.
AI systems learn over time how to find ‘optimised prices’ by running elasticity models examining how price changes affect demand across different SKUs, customer segments, and time windows. Digitalisation has resulted in the reduction of ‘menu costs’, allowing platforms to change prices as a function of demand at negligible cost. This can look like Uber and Deliveroo’s algorithmic surge pricing and discount coupons based on demand.
Consumer data pipelines power the entire process and separate algorithmic pricing from individualised pricing. None of the inputs they draw on are visible to the shopper being priced and include credit scores, GPS location patterns, search duration and frequency, individual purchase histories, browser cache and cookie data, and keystroke dynamics that correlate with different emotional states. The US Federal Trade Commission’s surveillance pricing study on intermediary firms such as McKinsey, Mastercard and Accenture, found that behaviours including mouse movements and items left in shopping carts are tracked and fed into individualised pricing models and used by at least 250 retail clients from grocery to apparel.
Loyalty programmes have historically been the most socially accepted form of individualised pricing as a straightforward exchange of data for rewards. However, that social contract has been hollowed out: in many cases the programme is now less a reward mechanism than the primary data-collection infrastructure that makes surveillance pricing possible. The clearest result is the reverse loyalty programme. Once a retailer has accumulated enough behavioural data to recognise a frequent customer's demand as inelastic, it can offer that customer fewer discounts rather than more resulting in the most loyal ending up being charged the most because their loyalty looks like captive demand. Reporting on Starbucks, whose loyalty data was found to have been shared with 64 third parties without customers' awareness, showed how loyal customers ended up paying more than others. The former director of the FTC's Bureau of Consumer Protection found that companies mine loyalty data to gauge how much customers will tolerate, and that programme designs are structured to obscure whether consumers save anything at all.
Why department stores cannot win the data war
The data asymmetry between big tech and any other retailer is structural and uncloseable. Amazon sees the full browsing and purchase graph of hundreds of millions of shoppers across every category plus the sales data of the third-party sellers who compete on its own marketplace. Through initiatives reportedly grouped under Project Starfish, a unified internal data system, Amazon ingests the product listings, prices, and transaction data of thousands of third-party brands, surfacing their goods and completing checkout inside its own app, even as it sends cease-and-desist letters to those who scrape its marketplace in return. Because many of those brands depend on Amazon's own cloud, the cost of resisting falls entirely on them.
Every transaction adds to Amazon's data, that data sharpens its next price, and the sharper price wins the next transaction, compounding the lead it already holds. A department store entering the same contest starts with less data, learns more slowly from what it has, and so improves its pricing more slowly than Amazon improves its own; the gap does not hold steady but widens with every cycle. The contest is also frequently run on Amazon's own ground: a department store that lists on its marketplace or builds on its cloud feeds the same transaction and cost data into the engine it is trying to beat, so the effort to compete on data can end up subsidising the competitor. A gap of this kind is not closed by spending more; spending only buys a place on a faster treadmill.
The data feeding Amazon's pricing engine therefore includes competitor and brand data that a department store could neither lawfully nor practically acquire. It reprices millions of times a day and runs continuous live experiments at a volume that produces reliable elasticity estimates for each SKU at a given moment. A department store simply lacks the traffic to learn at that scale. And because Amazon spreads the fixed cost of pricing infrastructure and data-science talent across a sales base no single retailer can rival, each increment it invests buys a sharper model than a department store's can. A retailer that competes on the platform's own terms therefore builds a permanently inferior copy of Amazon's machine and loses the data war anyway while giving up the one advantage Amazon cannot buy - a customer's trust that they are not being milked.
How individualised pricing erodes trust
The sharpest critique of personalised pricing is that it targets vulnerability and circumstance rather than preference. It prices the moment a shopper's bargaining power is lowest — the borrower with a poor credit score, or the parent buying for a sick child at midnight — pricing the weakness of the position, not a preference for better service.
Opacity is a core feature that makes individualised pricing sustainable. Because its operation is almost impossible to verify from the outside, a shopper has no basis on which to challenge it. As Teachout writes, "When different prices show up for different people, companies tend to claim it is not the work of surveillance pricing." Amazon and Delta have attributed observed price variation to "market dynamics, third-party sellers or A/B testing."
Economist and CEO of aiRESULTS, Matt Hasan argues that an algorithm may estimate what a customer can pay but cannot measure how they feel about paying it. Once a shopper discovers, or even suspects, that a price reflects what the system knows about them, the relationship turns adversarial. Those tools are already mainstream: price-history trackers such as CamelCamelCamel and Klarna's PriceRunner have made comparison a reflex, and a 2025 Deloitte survey found that 56% of US consumers planned to use AI assistants to compare prices and hunt deals. As that capability spreads, a growing share of consumers will police prices and disengage until they fall. This is still a trajectory, not a settled state, but it runs one way. As opacity grows costlier to defend, the endpoint is agentic commerce: buyer and seller algorithms manoeuvring against each other until the human relationship with the brand thins to nothing. A customer who starts tracking prices is no longer loyal but transactional, and the extra margin taken from them now is lost when they disengage. Nearly 70% of consumers said they are very or extremely protective of their personal data and would trust a merchant less for covertly using it.
This is what makes transparency decisive, and it answers the obvious objection that a platform like Amazon is trusted despite its data practices. Consumers do not process prices as rational negotiators but as signals of fairness and intent. Once a shopper starts to feel like a target rather than a customer, concealment cannot undo it — and suspicion alone, not proof, is enough to trigger the shift. Personal income shapes both how unfair a price feels and how strongly consumers act on it, so for households with the least budgetary room a shifting price reads as exploitation rather than just annoyance. The only long-term control is to make the logic of prices legible. Amazon is tolerated on convenience and price, not on pricing candour. This is the uncomfortable point: its scale is proof that most shoppers reward convenience over candour, so transparency is a bet on the segment that values being dealt with straight.
How a department store earns trust
Making that bet credible begins with an honest admission: department stores too operate loyalty programmes, apps, and data partnerships built on the same infrastructure described here. The real position is therefore not that a department store holds less customer data, but that it commits to using it in only one direction, to lowering prices, but not to raise them. The same behavioural signals that could locate a customer's ceiling can instead fund discounts, protect the price of essentials, and reward frequency, while the retailer refuses on principle to convert a rewards relationship into a map of who can be charged more. But a promise to hold that data and not weaponise it is not self-enforcing. The capability to find each customer's ceiling stays in-house, the margin from using it is permanent, and its use is nearly impossible to detect from the outside, so restraint is precisely the claim a shopper cannot verify.
Disclosure narrows that gap without closing it: a department store that states openly which data it collects and to what end, and commits that pricing intelligence will only ever move a customer's price downward, turns a private intention into a public standard the retailer can be measured against and caught breaking. Norway's REMA has used dynamic pricing to make about 2,000 price changes a day exclusively to lower them. What disclosure cannot do is remove the temptation. The department store is asking to be trusted with an instrument it declines to fire, and that trust is earned by making a breach visible and costly, not by the pledge itself.
This does not mean abstaining from personalisation, but being transparent about what it entails. Personalised discounts, openly offered, lower a specific customer's price and are welcome; personalised price floors, which raise it because the algorithm judges the shopper will pay more, are what customers punish. But 'visibly' is the hard part: from the outside, a discount someone else received and a price floor aimed at a customer look the same. Refusing the second cannot be shown by saying so; it has to be anchored in something checkable — a single public posted price that no shopper is ever charged above, with personalisation allowed to move only downward from it. That makes the floor's absence verifiable, because charging above the posted price would be detectable where a bare pledge would not be. Success depends less on how sophisticated the system is than on whether people feel it works for them rather than against them.
Why principled pricing survives the regulatory crackdown
The regulatory crackdown looks like a threat to personalised pricing, but its logic favours the retailer that has already committed to transparency. Disclosure laws like New York's requirement to display "This price was set by an algorithm using your personal data" risk sweeping in routine loyalty discounts and targeted promotions alongside surveillance pricing; if retailers pull back personalised offers to avoid compliance risk, the price-sensitive households, bulk buyers, and frequent shoppers who gain most from those discounts lose out. The NRF’s strongest argument is the ‘white box’ model of explainable algorithms, a ban on protected data, and oversight for bias.
New York is, for the moment, among the most heavily regulated jurisdictions on this issue and spans a range of regulation: the Algorithmic Pricing Disclosure Act (in force since November 2025 and upheld against the NRF's First Amendment challenge) mandates disclosure, while the pending One Fair Price Act would ban surveillance pricing yet preserve bona fide loyalty programmes and uniform discounts, and further state and New York City bills target electronic shelf labels and intra-day price changes. Whether a jurisdiction chooses a label or a ban, the instruments converge on the principle that a retailer may not use personal data, unilaterally and invisibly, to decide what a consumer should pay, but they act with very different bluntness.
That bluntness tells against the disclosure label most of all: it tars a benign, downward-only discount with the same ominous warning as extractive surveillance pricing, so even a transparent retailer pays a cost under it, badging its good offers as if they were suspect. The exposure is lowest, not nil, and lower under a well-drafted ban than under a blunt disclosure rule. A department store that has made transparency its differentiator is not scrambling to comply as it already meets the standard these laws are converging on.
Transparency as differentiator
Loyalty, trust, and individualised pricing are in tension as currently practised. A programme that rewards frequency and states its logic openly, and one that mines behavioural data to find the maximum a customer will bear, are structurally the same product with opposite intent, that consumers cannot tell apart from the outside. Transparency is what lets a department store resolve that tension without trying to out-compete Amazon on data, a contest it would lose. But that advantage is neither free nor guaranteed.
On the deepest question — whether pricing should be allowed to redistribute surplus from consumers to retailers at all — IADS's position is that neither retailers nor technologists should settle it on consumers' behalf. It is a distributional choice for regulators and democratic institutions, and the one place where self-policing is least trustworthy. Transparency is not a universal winning move. Its upside is genuine — studies of demand-based pricing find that disclosing the reason for a price raises how fair consumers judge it, so candour can command a premium among shoppers who value being dealt with straight. But the cost is just as real: Amazon's scale is standing proof that most shoppers, most of the time, still choose the cheaper, more opaque option. For the department stores that can hold that line, treating transparency as a differentiator rather than a compliance cost, opposing the Amazon model, is how they remain the retailers consumers still trust when every price is set by an algorithm.
Credits: IADS (Anchita Ranka)
IADS Exclusive - The great Marks & Spencer reset: A retail transformation case study
IADS Exclusive - The great Marks & Spencer reset: A retail transformation case study
With its 142 years of history, Marks & Spencer (M&S) is a British retail institution, originally a penny bazaar in Leeds with the radical proposition: “don't ask the price, it's a penny”. M&S built its first competitive advantage not on price alone but on simplicity and trust, principles that remain the foundation of the brand. From the 1930s, the company began bypassing wholesalers entirely, working directly with British manufacturers with quality specifications, and selling exclusively under its own St Michael label. By 1997, M&S had become the first UK retailer to record a pre-tax profit of £1bn, a milestone followed by a continuous decline triggered by stiff competition and overreliance on UK sourcing (until the 1990s, M&S’s policy was to sell 99% UK-made products). FY2000/01 ended with a £145m pre-tax profit. In 2000, the St Michael brand was retired. In 2008, M&S started selling external brands, which confused consumers. The following fifteen years saw clothing sales falling while food sales increased.
The current recovery, under chairman Archie Norman (the architect of Asda's 1990s turnaround) and CEO Stuart Machin from 2022,has restored M&S to its strongest competitive position in over two decades by returning to fewer, better products, quality and value for money. In FY2025/26, group sales grew just 1.9%, from £13.9bn to £14.2bn. The food division accounted for £9.7bn, growing by 7% YoY.When it comes to general merchandise, in FY2024/25, M&S held 10.5% of total UK clothing sales despite losing a fifth of its UK clothing market share between 2014 and 2024. Group profit before tax hit £881.1m in FY2024/25, the highest in over 15 years. FY2025/26 fell to £671.4m, down 23.8%, due to a severe April 2025 cyberattack that paused e-commerce operations for approximately eight weeks.
The turnaround plan is on at the legacy retailer, but what is driving the change? Rationalising the product offering, transforming the brand's style credentials, developing a new consumer and marketing strategy, and an operational rethink could represent a basic plan, but its execution seems to be what matters for M&S.
How M&S redesigned its product offer
M&S Food: feeding growth
When Machin took the helm, M&S Food was a business with a strong identity but increasingly perceived as an expensive treat destination rather than a credible everyday choice. As stated in their 2024 annual report, Machin doubled down on product quality, upgrading over 1,000 existing products and launching more than 1,300 new lines, while simultaneously addressing the value perception gap through a Trusted Value Promise that delivered price cuts across more than 200 products. This dual approach, protecting M&S's elevated DNA while making the brand more accessible, proved effective. Food delivered LFL sales growth of 8.6% in FY2024/25, followed by a further 7% growth in FY2025/26. Critically, these figures were not inflation-driven as M&S outperformed the market over the three years leading to FY2024/25.
However, structural limitations remain. M&S Food still operates primarily through convenience-sized stores and food halls rather than full-line supermarkets, which limits its ability to capture the full weekly food shopping. M&S Food is seen as a complementary premium destination for most households rather than their primary grocer. However, Machin does a lot to reduce the gap with mainstream grocery by increasing store surfaces to offer a larger daily product range and more conventional meal planning.
Fewer, better: fashion brand portfolio simplification
Not only is food on the menu, but M&S is also undergoing a fashion makeover. Long derided by some as a destination for the over-55s, the retailer enforced a strategy to become a more style-conscious, trend-aware brand. The brand portfolio was simplified. M&S eliminated range clutter, reduced product options by 9% season-on-season until Spring/Summer 2026, and focused its tiered architecture on five clearly defined brand identities built around private labels: M&S Collection for everyday essentials, Per Una for a feminine occasion-wear customer, Goodmove for activewear (launched in 2020, it became M&S's biggest in-house own-brand by 2022, selling over 1.6 million items annually), Autograph for accessible premium, and a curated third-party brand platform.
The Autograph case demonstrates private-label relevance. Total Autograph sales grew 47% year-on-year in 2025. Men's Autograph alone reached approximately £200m, up from £50m just three years earlier, a four-fold increase driven by buying more deeply into core lines, elevating quality (cashmere, merino, Supima cotton, silk), increasing style and fostering innovation. For example, in October 2025, M&S launched Autograph Performance, a men’s technical workwear featuring four-way stretch, crease-recovery, water-resistance and machine-washable tailoring, which grew by 100% in under two years. Best-selling styles within Autograph include a £20 Supima cotton t-shirt that generates approximately £20 million annually on its own.
In parallel, the focus was on full-price discipline. By the end of 2025, about 80% of clothing was sold at full price, up from 63% pre-Covid, demonstrating that disciplined full-price selling offset any volume reduction. Furthermore, the time spent holding stock in inventory has fallen from 18 to 11 weeks. The Fashion, Home & Beauty (FH&B) division revenues grew from £3.72 billion in FY2022/23 to £4.24 billion in FY2024/25, while operating margins expanded from 8.7% to 11.2%. However, in FY2025/26 and mostly due to the April 2025 cyberattack, FH&B revenues were down 7.7% to £3.92 billion, and margins compressed to 5.5%. But the second half of that same year returned to +4.3% LFL growth. Online FH&B sales dropped 41% in H1 and recovered to +5% in H2.
Finally, a Brands at M&S platform was built as a parallel strategy, primarily conducted online and in-store, where relevant. M&S onboarded 60 external brands by FY2022/23, growing that revenue by 67% to £158m. In 2025, partner-brand fashion sales online increased by 42%, and the overall third-party brand sales exceeded £200m. Labels include Hugo Boss, Nobody's Child, Whistles, Hush, Calvin Klein, Tommy Hilfiger, Adidas, Sweaty Betty and Speedo. Those brands strengthen categories where M&S is weaker, while reinforcing its quality and fashion positioning by association. The external brand strategy was tried in 2008 without any success, as it was introduced as a substitute because M&S's own brand had lost credibility. There was no clear strategic rationale or curation principle. Rather, it looked like a contingency plan. Finally, it confused customers about what M&S stood for. What seems to be different this time is that M&S’s own brands have been fixed first and foremost. External brands are complementary, only filling gaps where needed. Brands at M&S also expand into beauty with the addition of brands like Clinique. In 2022, the strategy proved efficient in driving cross-selling: 96% of third-party brand purchases included another product.
M&S had done a good job re-establishing its value, quality and style credentials, with apparel market share rising to 10.5% in 2024/25, from 9.1% in 2021/22. In early 2025, John Lyttle, Managing Director of Clothing & Home, was tasked with transforming the end-to-end supply chain, consolidating suppliers to reduce risks and doubling online FH&B revenues from £1.4 billion to approximately £3 billion.
Home categories: less is more
In Spring 2024, the company formally exited its own-brand bulky furniture business. The logistics cost relief accrued in FY2025/26 contributed to overall supply chain cost reduction even in a year severely disrupted by the cyberattack. Bulky furniture required a dedicated distribution network with structurally low returns. Exiting it allowed M&S to concentrate its home investment on categories where its quality credentials are strongest: bedding, bath, soft furnishings, tableware and home fragrance. In addition, the Kelly Hoppen collaboration, launched in September 2024, gave M&S a design identity in the home that matches what Autograph does for fashion: authority through private labels.
From perception to purchase: M&S's consumer strategy
Demographics and brand perception
The critical data point regarding consumer perception of M&S is that style perception improved, reaching #1 for style in YouGov rankings, overtaking all competitors despite the trading disruption caused by the cyberattack. Quality and value perception both maintained #1 positions. In more detail, M&S clothing's brand perception and market position strengthened from 2020 to the 2025 cyberattack, rising from 40 to 50.1 in 2025. It now significantly outperforms the average high street fashion retailer in quality, value, reputation, satisfaction, and recommendation scores. M&S ranks first among all high street fashion brands for consumer consideration, with a score of 46.8%, well ahead of Next (34.8%) and Primark (30.1%). With 54% conversion from consideration to purchase intent, M&S also leads in converting interest into actual purchase intent (Next is at 40%, and Primark at 45%). Private labels also help the retailer’s consumer perception. The demographics of Autograph's new customers proved particularly relevant for attracting a younger crowd: 52% of Autograph menswear buyers in FY2024/25 were new, and 55% of all Autograph customers were under 45.
With consumer data stolen, the question of customer loyalty rapidly emerged in the wake of the cyberattack. A survey of 500 UK consumers on the public perception of M&S, conducted by consumer research company Maru, found that the number of consumers who would recommend M&S to others dropped from 87% before the cyberattack to 73% after it was made public. Despite the devastating event, YouGov's Best Brand Rankings 2026, measuring full-year 2025 data, show M&S as the #1 brand in the UK for the second consecutive year, with a score of 52.7, leaving the second-ranked brand (IKEA at 42.6) more than 10 points behind. In 2019, the retailer’s reputation score was 38.9. It was 45.6 at the end of 2025.
Influence, celebrity and community: M&S's marketing playbook
A commercially efficient example of the retailer’s marketing strategy is the M&S Insiders Programme, 22 colleagues in 2025 who post on Instagram and TikTok about M&S fashion and home products. Early on, they had a combined following of over 300,000. They found that with an M&S Insider post, customer sentiment is, on average, 10% higher, and 30% more customers choose to shop through M&S.com compared to a conventional influencer post. In FY2023/24, the programme generated 21 million impressions.
The celebrity layer has been developed over the years. Sienna Miller's September 2023 Anything But Ordinary collection and campaign exemplify M&S's A-list positioning. The campaign generated a Google search spike and a viral TikTok creator moment. A second party-oriented Sienna Miller collection followed in October 2024, driving younger customers in-store, 10 years younger than the store average of 35- to 50-year-olds. It also sold through quickly, with more than 42,000 customers clicking “contact me when available” for the sold-out styles. According to M&S, 92% of customers who bought from the Sienna Miller collection also bought from the store’s core womenswear lines. Their Bella Freud collection sold 9,000 jumpers in two hours. Machin regretted that it was a small buy.
In March 2026, Gillian Anderson joined M&S as "Chief Compliments Officer" in a new role focused on affirmation and customer connection, including expansion into platforms like TikTok Shop. This quirky initiative builds on the retailer’s Love That! campaign, which originated as a social media series and quickly gained viral traction, generating 20 million views. Through this approach, M&S is tackling emotional branding to increase its bond with customers.
Loyalty scheme: Sparks reignited
In April 2026, M&S overhauled its Sparks loyalty scheme, replacing traditional point-earning and burning with spendable cash rewards. The new digital Sparks wallet allows shoppers to earn cash rewards across all categories, with additional bonuses for cross-category purchases and partner activities, such as booking holidays with Virgin Atlantic. This overhaul is possible thanks to advanced AI and data analytics, enabling the delivery of offers tailored to individual shopping habits. The programme also encourages customers to explore new areas of the store, rewarding discovery and engagement beyond their usual purchases.
The M&S's comeback: culture, international expansion, crisis and infrastructure transformation
A new management style and mindset
Chairman Archie Norman created the conditions for Machin to succeed by enabling candid conversations about the state of the business. With more than 60,000 employees and around 1,500 stores, Machin’s leadership style is hands-on and detail-obsessed. For example, Machin is the number one M&S menswear customer, buying everything from shoes to jackets, regularly visiting stores unannounced to shop and observe. Also, he keeps a black book in which he writes down every product, its price, his views on it, and comparisons with competitors. Store managers have his phone number in case they need to text him with questions or feedback. The Straight to Stuart programme allows any staff member to contact him with ideas and to get a reply. More than 25,000 people have written to him in his first two and a half years as CEO.
One of Machin's earliest moves was to break a culture of defensiveness and silence. Key actions included standing on a box every Monday to share real trading numbers with the team, including bad news, creating psychological safety for staff to speak up, and tackling resistance to change from within, which Machin compares to the instinct to reject a transplanted organ.
Machin articulated a simple, memorable strategy: protect the magic, modernise the rest. That transformation includes closing shops, reducing the space M&S dedicates to clothing, and improving its online capabilities to reach 50% of the clothing business achieved online. Despite strong results, Machin resists complacency, describing himself as positively dissatisfied. He warns against "rose-tinted spectacles" and maintains that the journey is ongoing, especially considering the April 2025 cyberattack.
A renewed international expansion
M&S started its international expansion in the 1970s by buying local chains. By the mid-1990s, they were rapidly opening franchised and owned stores, with the ambition to reach 25% of revenues from overseas by 1997. The overexpansion unravelled quickly, leading to a complete withdrawal from all international markets. Starting from 2006, CEO Stuart Rose relaunched international growth, this time through a lighter franchise model, including the first store in China in 2008. His successor, Marc Bolland, declared the ambition to become a truly international retailer, with India and China as priorities. After Bolland opened a flagship on Paris’ Champs-Élysées in 2011 and announced plans for 250 new stores worldwide, his successor, Steve Rowe, reversed course entirely, closing 53 overseas stores in 10 countries in 2016, including Paris.
Under Machin, and learning from past experiences, M&S pursues its international development differently. This time, they partner with other established e-tailers and retailers: online with Zalando from 2022 and with Amazon from 2026 in European markets, and also with department stores in the US and Australia. M&S has partnered with 24 David Jones stores in Australia since 2025 and, more recently, with Nordstrom in 30 stores and online. With these partnerships, M&S acts as a brand rather than a retailer, capitalising on established customer bases to build brand awareness and test its appeal in new markets, while avoiding risky standalone stores. This move demonstrates the relevance of department store partnerships. Finally, to enhance global brand visibility, initiate additional partnerships and confirm its fashion ambition, M&S’s latest initiative is to present a see-now-buy-now collection at London Fashion Week in September 2026.
The attack that accelerated everything
The assault on M&S began quietly, months before it became public. Threat actors infiltrated the company's systems, stealing the database containing passwords for all domain users. The entry point was a social engineering attack in which hackers impersonated an M&S employee, convincing staff at a third-party IT contractor (reported to be Tata Consultancy Services, which has provided IT helpdesk services for over a decade) to reset an internal user's password.From there, the group linked to Scattered Spider deployed ransomware that encrypted M&S's virtual machine infrastructure. Customers first noticed something was wrong when contactless payments and click-and-collect terminals began failing across the chain. By April 25, M&S had shut down all online purchases. The online store remained closed for 46 days. In May, M&S confirmed that personal customer data had been stolen, prompting a mass password reset and official notification to affected customers.
The operational fallout was total in the weeks that followed. With automated stock ordering, inventory management, supply chain logistics, and internal systems all offline, M&S reverted to pen and paper. The financial consequences were severe and cascaded across the full year. M&S recorded £131.3 million in direct incident-related costs. Against this, it got £100 million in insurance proceeds, bringing the net direct cost to approximately £31 million. But the real damage was operational: online sales fell 41% in the first half of the year, resulting in a gross operating profit impact of approximately £300 million.
What the attack changed inside M&S is to be found in acceleration and transparency. Machin announced at the May 2025 results that M&S would use the disruption to compress a planned two-year technology transformation programme into six months, rebuilding on an accelerated timeline rather than recovering to the original plan. Digital and technology expenditure is planned at £140 million in FY2026/27 alone. Chairman Archie Norman called for mandatory reporting of cyberattacks to the National Cyber Security Centre, revealing that he believed two other major UK companies had been hacked in the preceding four months without public disclosure. The M&S general counsel, Nick Folland, told Members of Parliament that M&S would advise other businesses to ensure they can run their operations on pen and paper when a serious attack hits.
M&S's operational overhaul
As product appeal increased in FH&B, the business was still constrained by its legacy supply chain and outdated processes. Besides, the cyberattack prompted a new strategy that explicitly shifted toward better operational execution. M&S is spending £600m to £650m in FY2025/26, of which between £200m and £250m is being invested in technology infrastructure, store maintenance and upgrades to its logistics fleet. Automating what was previously largely a manual task, a new fashion planning platform that connects budgeting, buying, and replenishment is being fast-tracked following the cyberattack. A £120m three-year automation investment for the FH&B supply chain was announced to increase capacity, reduce complexity, and deliver cost savings estimated at multi-millions. A new 437,000 sq ft automated fashion distribution centre at Lichfield, acquired in FY2025/26, is expected to increase capacity and speed up deliveries.
When he took over, Stuart Machin inherited a brand with true equity but structural drift. He chose to act on both at once by leveraging retail fundamentals: fixing the product, sharpening the portfolio, investing in the infrastructure required to compete in a digital-first market, and bringing a new management style and a refreshed mindset. Demonstrating greater impact than pure innovation, the retail back-to-basics results are clear: share price has tripled from 130p in 2022 to 350p in 2026, profit is soaring, and the brand ranks #1 in the UK. Also, the space M&S occupies, more expensive than high street brands but cheaper than luxury, with a good value-for-money ratio, has been successfully reclaimed. This positioning is difficult and requires discipline. Few retailers succeed here: Zara may be the best example (see our Exclusive here), and M&S is now another to follow. The only thing Machin’s turnaround plan couldn’t avoid was the April 2025 cyberattack. Despite being highly disruptive and costly, this event is seen as an accelerant for continued transformation, or at least advertised as such.
Credits: IADS (Christine Montard)
IADS Exclusive: Art and department stores
IADS Exclusive: Art and department stores
Last March, the IADS was interviewed by a French newspaper that wondered about the "recent incursion" of art into department stores. The journalist wanted to know whether this was a new way to lure customers or to offer them a novel type of luxury experience.
The question revealed a common misconception : the relationship between art and the department store did not begin with experiential retail, with Instagram, or with the contemporary art market's global expansion. It began at the inception of the format itself, in the 1870s, for reasons that were at once commercial, cultural, and societal: the need to offer an extraordinary experience to customers in the nineteenth century, the ambition to position the department store at the forefront of the avant-garde, and, in some countries, the imperative to replace cultural institutions that did not yet exist. Department stores did not wait for art to become a global market before making it part of their business model. They were there from the start.
What follows is a detailed examination of this history — from the founding gestures of the 1870s to the art foundations and museum partnerships of today — drawing on documented sources across five continents. It is addressed to the leaders of the department store sector, in the conviction that understanding this heritage is not a matter of nostalgia but of strategic clarity.
Born Together: Why Art Is in the Department Store's DNA
A shared origin with the museum
The modern department store and the modern public museum emerged in the same historical moment and share deep structural affinities. Both organise the display of objects within architecturally spectacular spaces; both choreograph a visitor's movement through carefully sequenced environments; and both rely on the power of visual staging to create desire, whether for knowledge or for acquisition. As historians argue, the "model rooms" of early department stores borrowed directly from museum display techniques, and the influence flowed in both directions.
Émile Zola captured this convergence when he described Le Bon Marché as a "cathedral of modern commerce" in Au Bonheur des Dames (1883). Zola's metaphor was not merely literary: it reflected the ambition of founders such as Aristide Boucicaut to create spaces that would elevate the act of shopping into a broader cultural experience, one that entertained, educated, and inspired.
Architecture as the first artistic statement
Before any painting was hung or any concert staged, the department store building itself constituted an artistic proposition. Le Bon Marché, designed by Louis-Charles Boileau, with Gustave Eiffel serving as consulting engineer, introduced an iron-and-glass structure of extraordinary ambition. Galeries Lafayette commissioned a neo-Byzantine dome executed in 1912 by the master glassmaker Jacques Gruber, whose stained-glass work also adorned El Palacio de Hierro in Mexico City. Across Europe and beyond, department stores deployed cupolas, monumental staircases, ornamental ironwork, and elaborate façades that placed them squarely within the vocabulary of civic and artistic architecture.
This was no accident. From the 1880s onward, the École des Beaux-Arts in Paris included the department store as a formal architectural programme in its competitions, confirming that the building type had earned a place in the artistic imagination.
The mechanisms of art integration
Beyond the building envelope, department stores developed a distinctive set of mechanisms through which art was woven into the retail experience. Four channels stand out.
The first was the store window as a space of artistic creation. The Viennese architect Frederick Kiesler theorised this practice as early as 1929 in Contemporary Art Applied to the Store and Its Display, while the American industrial designer Norman Bel Geddes conceived the windows of Franklin Simon in New York as a form of "street theatre." This tradition has recently been the subject of scholarly re-examination, notably through the exhibition Fresh Window at the Museum Tinguely in Basel (2024–2025).
The second was the integrated art gallery. Wanamaker's in Philadelphia opened a dedicated art gallery as early as 1881; Le Bon Marché, founded in 1852, established its own picture gallery in 1875; and Mitsukoshi in Tokyo created a formal art section in 1907. These were not marginal amenities: they occupied prominent floor space and were actively programmed.
The third was the cultural event as a service to clients. The Boucicaut introduced the concerts of the Harmonie du Bon Marché in 1873, alongside a reading room and a picture gallery, explicitly integrating culture into the customer proposition. In Japan, the Mitsukoshi Hall hosted kabuki performances, dance recitals, and public lectures, fulfilling a role that extended well beyond commerce.
The fourth, and perhaps the most significant in societal terms, was the democratisation of access to art. At a time when public museums were scarce — particularly outside major capitals — and commercial galleries catered exclusively to collectors, the department store opened art to a far broader audience. This function was especially pronounced in Japan, where the museum network remained embryonic until the post-war period, and in the United States, where department stores played a role in introducing modernist art and design to the middle-classes.
Strategic functions: prestige, differentiation, and flow
The integration of art into the department store has never been purely altruistic. From the beginning, it has served identifiable strategic functions that remain relevant today:
- Art confers prestige and social distinction. For the rising bourgeoisie of the 19 century, the department store's cultural programming — exhibitions, concerts, encounters with contemporary artists — offered a form of social legitimation. For today's high-net-worth clients, the presence of significant artworks continues to signal that a store operates at a level above purely transactional retail.
th
- Art is also a powerful instrument of commercial differentiation. It separates the department store from more functional formats — the supermarket, the category specialist, the online marketplace — by embedding the shopping journey within a broader sensory and intellectual experience.
- Finally, researchers have identified two specific spatial effects that art generates within the store environment. The "fountain effect" describes the contemplative pause that an artwork or installation creates in the customer's path, slowing the pace and deepening engagement with the surrounding offer. The "shower effect" refers to the downward flow of visitor traffic from an upper-floor exhibition back through the selling floors, generating incremental exposure to merchandise.
A Consistent Commitment to the Avant-Garde: Department Stores and the Contemporary Art of Every Era
A common assumption is that department stores' embrace of contemporary art is recent, a response to the rise of experiential retail, social media, or the blurring of luxury and culture. The historical record tells a very different story. From the 1870s onward, in every decade and across every major market, department stores have consistently supported, exhibited, and commissioned the art that was most advanced in its time. This is not opportunism but a structural pattern.
1870–1910: embracing the avant-garde before the term existed
The earliest gestures were already bold. As described in the previous section, the Boucicaut gallery at Le Bon Marché (1875) did not confine itself to safe academic painting — it exhibited artists refused by the official Salon, aligning the store with the avant-garde before the term existed. By 1912, a gallery of decorative arts had been added, and in 1923, the store launched the Atelier Pomone, a dedicated furniture workshop aligned with the emerging modernist design movement.
La Samaritaine offered another demonstration that department stores sought out the most advanced architectural language of their time. When Ernest Cognacq commissioned the architect Frantz Jourdain to design the store's new building in 1905, the result was a manifesto of Art Nouveau applied to commercial architecture — polychrome ceramic façades, exposed iron structure, and decorative programmes that placed the store at the cutting edge of contemporary design. A second phase, completed in the 1930s by Henri Sauvage, added an Art Deco riverside façade of equal ambition. The Cognacq-Jay were also art collectors; their holdings eventually formed the Musée Cognacq-Jay, a public museum in the Marais.
In the United States, John Wanamaker's Philadelphia gallery (opened in 1881) imported French painting directly from the Paris Salons — a sustained acquisition programme documented in the Smithsonian Archives over more than three decades.
In Japan, the trajectory was different in origin but equally forward-looking. Mitsukoshi organised its first art exhibition in 1904, featuring works by the painter Ogata Kōrin. A formal art department was established in 1907, and in 1908, the Osaka branch hosted what is recognised as the first modern art exhibition held in a Japanese department store. This was not an imitation of the West but an expression of the Meiji-era ideology of Bunmei Kaika — "Civilisation and Enlightenment" — which positioned department stores as institutions capable of bridging progress and cultural preservation.
1920–1940: modernism enters the selling floor
The interwar decades represent perhaps the most striking chapter in this history. Department stores did not merely exhibit modern art — they became active vectors for its dissemination to audiences that no museum or gallery could reach. In New York, the Wanamaker's Belmaison Gallery (1921–1925) exhibited Picasso, Matisse, Léger, and Braque alongside American artists. At Lord & Taylor in 1928, Dorothy Shaver drew more than 300,000 visitors to a full-floor Art Deco exhibition, including works by Picasso. At Kaufmann's in Pittsburgh (1929), ten monumental frescoes celebrated "Art in Industry." These programmes are examined in detail in the following section: what matters here is the pattern — in every case, the department store was engaging with the most advanced art of its moment.
The store window itself became a site of artistic confrontation. Salvador Dalí's surrealist windows for Bonwit Teller in New York (1936, 1939) — the latter ending in scandal, censorship, a shattered plate-glass window, and the artist's arrest — demonstrated that department stores were not exhibiting tame, decorative art. They were taking real risks with the avant-garde.
In Paris, the 1925 Exposition Internationale des Arts Décoratifs — the event that gave Art Deco its name — featured dedicated pavilions from Le Bon Marché, Galeries Lafayette, and Le Printemps. Their presence alongside national delegations confirmed that department stores were recognised participants in defining contemporary design, not mere retailers of it.
In Canada, a lesser-known but well-documented chapter unfolded in Montréal, where department stores played an essential role in the city's artistic life between 1900 and 1945. Henry Morgan & Co. organised exhibitions of etchings by Whistler, Zorn, and Millet as early as 1909. Ogilvy's, T. Eaton Co., and Dupuis Frères followed with their own programmes, functioning as cultural relays in a city still building its institutional infrastructure.
1950–1999: the institutional turn
In the post-war decades, the relationship between department stores and contemporary art deepened into something approaching institutional permanence — most dramatically in Japan, but with significant parallels in Europe and the United States.
Japanese department stores entered what can only be described as a golden age of cultural programming. Takashimaya exhibited Picasso as early as 1950. Mitsukoshi, Isetan, Hankyu, Odakyu, Keio, and Tobu all maintained integrated art galleries and mounted frequent exhibitions of both Western and Japanese masters, functioning in practice as the country's primary network of accessible art venues at a time when the public museum system remained limited. The most ambitious expression of this model was the Seibu Museum of Art (1975–1999), which operated at a genuine museum standard for a quarter of a century — a case examined in full in the following section and in the portrait of its founder, Seiji Tsutsumi.
In France, Galeries Lafayette inaugurated the Salon de Mai within the store as early as 1946, where the public could discover Nicolas de Staël and Giacometti — establishing a commitment to contemporary art exhibition that would deepen over the following decades.
In the United States, the tradition continued through new forms. At Bonwit Teller, Gene Moore's practice of hiring struggling young artists as window designers gave early public visibility to Jasper Johns, Robert Rauschenberg, and Andy Warhol. At Barneys New York, Simon Doonan's arrival as creative director in 1986 made the store's windows one of New York's most visible platforms for contemporary art. These episodes, which deserve detailed examination, are presented in the following section.
2000 to the present: the avant-garde as declared identity
The twenty-first century has seen an intensification, not an invention, of this relationship. What has changed is not the impulse but the scale, the institutional form, and the visibility.
Le Bon Marché launched its annual cartes blanches programme in 2016 — full-store artistic takeovers by leading international artists from Ai Weiwei to Daniel Buren. Galeries Lafayette opened Lafayette Anticipations in 2018, a production-oriented foundation for contemporary creation. Selfridges established The Art Block, a permanent sculpture destination curated by the Yorkshire Sculpture Park. Each of these programmes is examined in detail in the following section.
In New York, Bergdorf Goodman has sustained one of the most visible ongoing commitments to art in American retail. Under the creative direction of David Hoey since 2004, the store's holiday window programme has become an annual cultural event in its own right, while rotating exhibitions on the seventh floor have provided a dedicated gallery platform within the store. In 2025, Bergdorf Goodman formalised a partnership with Salon Art + Design, further anchoring its position at the intersection of retail and the contemporary art market.
New formats have emerged that dissolve the boundary between store and gallery entirely: Dover Street Market (founded 2004 by Rei Kawakubo), Colette in Paris (1997–2017, more than 200 gallery exhibitions), 10 Corso Como in Milan, K11 Musea in Hong Kong and PARCO in Japan all represent variations on a model in which the department store is, by design, a cultural institution. These are documented in the following section.
A global phenomenon, not a Western exception
One of the most compelling aspects of this history is its geographic breadth. The integration of contemporary art into the department store is not confined to Paris, New York, or London. It has manifested with equal conviction — and often greater institutional depth — in Tokyo, Osaka, Kyoto, Hong Kong, Montréal, Mexico City, and Milan. Each market has inflected the model according to its own cultural logic: in France, through architectural monumentality and bourgeois cultural performance; in the United States, through the store window as democratic public art and the opening of cultural space to women; in Japan, through the most deeply integrated model of all, in which the department store functioned for decades as a genuine substitute for the public museum; in Canada, through the department store as cultural relay in a city forging its artistic identity; and in the United Kingdom, through the synthesis of American retail spectacle with established British cultural institutions.
Landmark Exhibitions and Artistic Programmes Across the Twentieth and Twenty-First Centuries
Our thesis is that department stores have consistently championed the contemporary art of their time, from the 1870s to the present day. What follows is the detailed record — a survey of the most significant exhibitions, commissions, and artistic programmes that department stores have mounted across the major retail markets over more than a century.
The United States: the department store as incubator of modern art
In the U.S., department stores did not merely exhibit established artists — they provided critical early platforms for artists who would go on to reshape twentieth-century art.
The case of Bonwit Teller in New York deserves detailed examination because it encapsulates the phenomenon in its purest form. Gene Moore, the store's art director from the late 1930s onward, made a practice of hiring struggling young artists to design store windows — offering them both income and public visibility at a moment when neither was available through conventional art-world channels. In the mid-1950s, two young artists, Jasper Johns and Robert Rauschenberg, worked as Bonwit Teller's window designers under the shared pseudonym "Matson Jones." In 1957, Johns exhibited his painting White Flag on Orange Field in a Bonwit Teller window — its first public showing. That same year, Rauschenberg displayed a modified version of his Untitled (Red Combine Painting) in the same context. In 1951, Moore had hired Andy Warhol to create works for the store's windows. A decade later, in 1961, Warhol hung five paintings based on comic strips and advertisements behind Bonwit Teller's mannequins — an event widely regarded as his first act of public recognition as a fine artist, and a foundational moment in the emergence of Pop Art. James Rosenquist, who would become another leading figure of the movement, also designed Bonwit Teller windows before his gallery career began. The store's earlier engagement with the avant-garde was no less bold: Salvador Dalí's surrealist windows in 1936 and 1939, the latter of which ended in his arrest after he smashed the plate glass in protest against the store's censorship, remain among the most famous episodes in the history of art and commerce.
This pattern — the department store as a place where future art-historical significance was first made visible to the public — was not limited to Bonwit Teller. At Lord & Taylor in 1928, Dorothy Shaver transformed an entire floor into an Art Deco exhibition featuring works by Picasso. At Kaufmann's in Pittsburgh in 1930, ten monumental frescoes by Boardman Robinson, depicting "Art in Industry," encircled the first floor. At Marshall Field's in Chicago, the store maintained art exhibitions for several decades in the early twentieth century; its Walnut Room, completed in 1907, featured a Tiffany glass ceiling composed of more than 1.6 million individual pieces — a work of decorative art on a scale that few museums could match.
In the twenty-first century, American department stores have continued to engage with contemporary art through evolving formats. At Barneys New York, the tradition initiated by Simon Doonan culminated in projects such as the 2014 collaboration with Alex Katz and the Art Production Fund, which produced a fifty-six-foot frieze of eighteen black-and-white female figures displayed across the store's windows. At Bergdorf Goodman, the 2014 programme "Art Matters! Ten Artists for Ten Spaces," co-curated by Linda Fargo and Kyle DeWoody, commissioned site-specific installations throughout the store, including Peter D. Gerakaris's Rappaccini's Origami Terrarium. In 2025, Bergdorf Goodman formalised a partnership with salon Art + Design, anchoring its position at the intersection of luxury retail and the art market. At Saks Fifth Avenue, a "Fine Art Collection" was launched in 2024, offering more than 100 limited-edition contemporary prints — by artists including Sol LeWitt, Alex Katz, Christo and Jeanne-Claude, and Donald Sultan — through pop-up gallery spaces in stores from New York to San Francisco. At Bloomingdale's, the 2025 "Just Imagine" campaign with the British-Nigerian artist Yinka Ilori brought his distinctive colourful visual language into the store's windows and interiors.
France: from in-store gallery to dedicated foundation
The French trajectory is distinctive in its progression from early in-store galleries to full-scale institutional commitments — a movement that has accelerated dramatically in the twenty-first century.
Le Bon Marché has pursued the most sustained and visible programme of any European department store. Since 2016, the store has hosted an annual carte blanche each January — a full-store artistic takeover by a leading international artist, timed to coincide with the historic "mois du blanc" (home linen sale month) that Aristide Boucicaut himself invented in 1873. The roster to date constitutes a survey of major contemporary art: Ai Weiwei (2016), whose installation "Er Xi" (Child's Play) included a sixty-five-foot dragon and twenty illuminated silk-and-bamboo creatures suspended above the cosmetics department, fabricated by twelve kite-makers from Shandong province; Chiharu Shiota (2017); Leandro Erlich (2018); Joana Vasconcelos (2019); Oki Sato of studio Nendo (2020); Prune Nourry (2021); Mehmet Ali Uysal (2022); Subodh Gupta (2023); Daniel Buren (2024), whose "Aux Beaux Carrés" deployed more than 1,500 polycarbonate squares beneath the glass ceiling, with his signature 8.7-centimetre black-and-white stripes extending across escalators and columns; Ernesto Neto (2025), who suspended a twenty-eight-metre crocheted serpent from bamboo arches under the glass roof; and Song Dong (January 2026, the programme's eleventh edition), who transformed the main store windows into individual installations and created two immense chandeliers flanking the central escalator. This programme operates at a scale and with a curatorial seriousness that is comparable to that of many contemporary art institutions. The store also maintains a permanent collection of contemporary art assembled since 1989 and a design collection, both displayed throughout its selling floors, and offers monthly guided cultural tours.
Galeries Lafayette have followed a parallel but institutionally distinct path. The "Galerie des Galeries," a dedicated 300-square-metre exhibition space within the boulevard Haussmann store, has operated since 2001, presenting three to four exhibitions per year of French and international contemporary art, fashion, and design. In 2023, the artist Kimsooja installed "To Breathe" beneath the store's historic dome: a diffraction film that transformed the 1912 Jacques Gruber glass cupola into an infinite spectrum of projected colour, accompanied by an audio component composed of the artist's own breathing rhythm — the first immersive light installation of its kind in Paris. In 2026, the group launched "Pour Toujours," a carte blanche to four artists — the sculptor Gloria Friedmann, the photographer Birgit Jürgenssen, the Cypriot artist Christodoulos Panayiotou (on the main dome), and the American conceptual artist Lawrence Weiner (on the terrace) — confirming the ambition of its cultural programming.
The most significant institutional step, however, has been the creation of Lafayette Anticipations (the company’s foundation), which opened in 2018 at the Marais area of Paris, in a building rehabilitated by Rem Koolhaas's OMA. Unlike an in-store gallery, Lafayette Anticipations is a production-oriented foundation with a dedicated budget, commissioning and exhibiting new work by international artists including Lutz Bacher, Katinka Bock, Martin Margiela, Cyprien Gaillard, and Mark Leckey. This represents an evolution from exhibition to production — from showing art to making it possible.
The broader cultural recognition of this history was confirmed in 2024, when the Musée des Arts Décoratifs in Paris mounted "La Naissance des grands magasins" (April–October 2024), followed by a presentation at the Cité de l'Architecture (October 2024–March 2025), of which the IADS was a partner. The decision by France's leading design museum to devote a major exhibition to the department store as a cultural and artistic phenomenon — and to seek the sector's own international association as a collaborator — affirmed what this article has argued throughout: the relationship between art and the department store is not peripheral but constitutive.
The United Kingdom: Selfridges and the art of spectacle
Selfridges in London has built a sustained programme of art commissions and installations, starting when the store opened in 1909, with its first window displays paying homage to the French painters Fragonard and Watteau.
The contemporary programme is remarkable for both its scale and the calibre of artists involved. In 2003, the photographer Spencer Tunick staged "Be Consumed," in which 600 nude volunteers posed inside the Beauty Hall. In the same year, Barbara Kruger created a graphic campaign for a promotional campaign, deploying her iconic declarative typography across the retail environment. In 2012, Selfridges hosted a Yayoi Kusama × Louis Vuitton concept store, with the entire façade and interior overtaken by Kusama's signature polka dots and pumpkins, including a colossal figure of the artist on the façade. In 2022, 55 works by Victor Vasarely were exhibited in partnership with the Fondation Vasarely and Paco Rabanne. Other artists who have exhibited or created commissions for Selfridges include Tracey Emin, Marc Quinn, Banksy, Brian Eno, Fernando Botero, David LaChapelle, Joana Vasconcelos, and Sam Taylor-Wood.
The 2019 "State of the Arts" campaign further elevated the model. Nine artists — Darren Almond, Spencer Finch, Douglas Gordon, Chantal Joffe, Yayoi Kusama, Simon Periton, Michal Rovner, Conrad Shawcross, and Richard Wright — were given the Oxford Street windows as exhibition spaces, while "The Art Store" at the Corner Shop was developed in partnership with galleries including Gagosian, Pace, Perrotin, Victoria Miro, and White Cube.The department store and the commercial gallery system operated not in parallel but in direct collaboration.
The most structurally significant development, however, is The Art Block, a permanent sculpture destination at the centre of the Accessories Hall, designed by David Chipperfield Architects and curated by the Yorkshire Sculpture Park. Since its opening in 2018, The Art Block has hosted rotating six-month residencies, including Holly Hendry's "Phyllis" (2018), a nearly four-metre sculpture incorporating excavation material from the Crossrail project; Matthew Darbyshire's three-metre reinterpretations of classical deities (2018–2019); and Gray Wielebinski's "Exhibition" (2023), a monument inspired by Victorian public architecture.
Beyond Selfridges, Fortnum & Mason has hosted exhibitions from the Frank Cohen Collection of modern and contemporary British art, and Harrods maintains the Halcyon Gallery, a dedicated contemporary art space on its third floor.
Japan: the deepest integration
Japan's department stores represent the most profoundly integrated model of art and commerce in the global retail landscape.
The Seibu Museum of Art, which operated within the Seibu department store in Ikebukuro, Tokyo, from 1975 to 1999, stands as the apogee of this model. Founded by Seiji Tsutsumi, the museum opened with "The View of Japanese Contemporary Art," featuring twenty-seven artists, including Shusaku Arakawa and Tadanori Yokoo. Its programme over the following quarter-century was of genuine museum calibre: "30 Years of American Art" including Jasper Johns (1976); a Jasper Johns retrospective in collaboration with the Whitney Museum (1978); "Calder's Universe," also originating from the Whitney (1979); a major Man Ray solo exhibition (1990); and "Abstract Expressionism: The Golden Age of American Contemporary Painting" (1996). The museum assembled a permanent collection of approximately 800 works, now housed at the Sezon Museum of Modern Art in Karuizawa.
Seibu's influence extended well beyond its own walls. The broader "Culture Sezon" movement, shared with PARCO — founded in 1969 and developed as a platform for visual culture, theatre, and film — transformed an entire segment of Japanese retail into a cultural ecosystem. PARCO's visual identity was shaped by the graphic designer Eiko Ishioka, whose 1975 campaign featuring Faye Dunaway remains iconic. Today, PARCO continues to operate PARCO Museum Tokyo, Gallery X, and PARCO Theatre, while events such as "Shibuya PARCO Art Week 2025" demonstrate the model's ongoing vitality.
Takashimaya's contribution deserves particular attention for its engagement with the Japanese avant-garde. In 1956, the store hosted early exhibitions of the Gutai group — the radical post-war movement that anticipated Happenings and Fluxus. In 1958, Takashimaya Osaka mounted "International Art of a New Era: Informel and Gutai," a landmark exhibition curated in collaboration with the French critic Michel Tapié that placed the Japanese avant-garde in direct dialogue with European abstraction. In 1960, the "International Sky Festival" on the rooftop of Takashimaya Osaka suspended reproductions of works by American Abstract Expressionists and European Informel artists from balloons — a gesture of extraordinary audacity for a department store, or indeed for any institution.
Mitsukoshi, the pioneer, has continued its mission without interruption. The Mitsukoshi Nihombashi Art Gallery and the Mitsukoshi Contemporary Gallery host four to five exhibitions per week, spanning Japanese painting, international contemporary art, sculpture, and craft. Over the decades, the galleries have exhibited masters including Yokoyama Taikan, Tsuguji Fujita (Léonard Foujita), and Shoji Hamada.[xxvi] At Isetan in Shinjuku, the art gallery programme includes ongoing exhibitions of contemporary art in partnership with CADAN (Contemporary Art Dealers Association Nihon), while a 2021 retrospective, "80 Years of Design at Isetan," was produced in collaboration with the Eames Office.
New frontiers: Korea, Hong Kong, the Netherlands, Germany, Italy
The model has expanded well beyond the historical centres. In Seoul, the LOTTE Museum of Art, established within the Lotte Department Store in 2017, mounted "Daniel Arsham: Seoul 3024" in 2024 — the artist's first solo exhibition in Asia — while Shinsegae has opened the House of Shinsegae Heritage, a new exhibition space inaugurated with "Embracing and Delivering," devoted to the art of bojagi, traditional Korean wrapping cloth.
In Hong Kong, K11 Musea, opened in 2019 by Adrian Cheng of New World Development, represents perhaps the most radical contemporary expression of the department-store-as-cultural-institution concept. Conceived as a "museum-retail complex," K11 Musea integrates a permanent collection of more than 100 works by international contemporary artists — including Paola Pivi, Sterling Ruby, Joan Cornellà, and Adrian Wong — into its architecture and public circulation spaces. It is not a store with art in it; it is a space in which art and commerce are architecturally inseparable. Lane Crawford, also in Hong Kong, has adopted a lighter but consistent approach, with its 2025 Art Month In-Store Guide featuring collaborations with artists and designers including Ruan Hoffmann, Jaime Hayon, and Kristjana Williams.
In Amsterdam, De Bijenkorf launched "Room On The Roof" in 2015 — an artist-in-residence programme housed in the tower of its historic Dam Square building, initially in partnership with the Rijksmuseum. Residents have included the designer Maarten Baas (2015) and the artist Rutger de Vries, who exhibited works across seven De Bijenkorf branches.
In Berlin, KaDeWe has progressively inserted itself into the city's gallery ecosystem. In 2007, the artists Osko + Deichmann installed a 150-square-metre wheat field in the store's entrance hall. In 2025, "SCHAU, FENSTER im KaDeWe" was admitted to the official programme of Gallery Weekend Berlin — a signal that the art world now recognises the department store as a legitimate exhibition venue.
In Milan, La Rinascente has used its windows facing the Piazza Duomo as a platform for contemporary art commissions, notably Paola Pivi's "I am tired of eating fish" (2017), which placed feathered polar bears in eight vitrines during the Miart art fair.
The evolution of practice: from window to foundation
Taken as a whole, this record reveals not a static tradition but a clear evolution in how department stores engage with contemporary art. Four distinct phases can be identified.
First, the store window was an artistic medium — from Bonwit Teller's collaborations with Dalí, Johns, Rauschenberg, and Warhol to Selfridges' "State of the Arts" windows and Barneys' annual holiday commissions. The window was art's first point of entry into the department store, and it remains a vital format.
Then, department stores developed the integrated gallery — a dedicated exhibition space within the store itself. Le Bon Marché's picture gallery (1875), Wanamaker's art gallery (1881), Mitsukoshi's art department (1907), the Galerie des Galeries (2001), and Selfridges' Art Block (2018) all represent variations on this model.
The third moment was the museum within the store — an ambition realised most fully by the Seibu Museum of Art (1975–1999), which operated for a quarter of a century at genuine museum standard, and echoed today by the LOTTE Museum of Art in Seoul and Harrods' Halcyon Gallery.
The fourth, and most recent phase, is the independent foundation — a legally and physically separate institution created by a department store group to produce and exhibit contemporary art. Lafayette Anticipations (2018) is the leading example, but the pattern is visible in the K11 Art Foundation in Hong Kong and in the institutional partnerships that Selfridges has built with Yorkshire Sculpture Park, Frieze, and the ICA.
This progression — from window to gallery to museum to foundation — does not represent a replacement of one model by the next. All four coexist today. What it does represent is a deepening of commitment: from display to curation, from curation to production, and from production to institutional permanence. The department store's engagement with contemporary art has not merely persisted; it has matured.
The Great Dynasties: Department Store Founders and Families as Art Patrons
The preceding sections have documented a structural relationship between department stores and the visual arts — one that spans geographies, decades, and artistic movements. But structures do not create themselves. Behind the galleries, the foundations, and the exhibitions stand individuals: founders, heirs, and executives whose personal passion for art shaped the cultural identity of their stores and, in several remarkable cases, left a permanent mark on the museum landscape of their countries.
The founding generation: commerce as cultural ambition
The earliest department store founders did not merely tolerate art within their commercial enterprises. They actively sought it, collected it, and made it part of their personal and institutional identity.
Aristide and Marguerite Boucicaut, the founders of Le Bon Marché in Paris, were passionate collectors who understood that culture could elevate the department store beyond the transactional. Their establishment of a picture gallery for Salon rejects (1875) and of the Harmonie concerts (1873), described in Part I, was not a business decision in the modern sense — it was a personal conviction that commerce and culture were inseparable. After Aristide's death in 1877, Marguerite continued the cultural programme with equal commitment.
Ernest Cognacq and Marie-Louise Jaÿ, the founders of La Samaritaine, pursued a different but equally significant path. Over several decades, the couple assembled an important collection of eighteenth-century art — paintings, drawings, sculpture, furniture, and objets d'art — which they bequeathed to the City of Paris in 1928. That collection forms the Musée Cognacq-Jay, housed today in the Marais area. It is one of the clearest examples in retail history of a department store founder's personal collecting activity producing a permanent public cultural institution.
In the United States, John Wanamaker brought the same conviction to his Philadelphia store. The art gallery he opened in 1881 was an active programme of acquisition, not a decorative afterthought. His son Rodman Wanamaker deepened the commitment, financing the construction of the store's monumental organ — with 29,000 pipes, the largest playable instrument in the world — installed in 1911 and still operational today. Rodman was a recognised philanthropist whose ambition was to make the store a genuine centre of artistic and musical life.
Harry Gordon Selfridge, who opened his London store in 1909, conceived of spectacle and culture as foundational to the retail experience. He published The Romance of Commerce in 1918, articulating a philosophy in which commerce and aesthetics were inseparable. The cultural ambition he established — from the Fragonard-and-Watteau-inspired opening windows to the institutional partnerships of today — has been sustained and amplified by successive managements over more than a century.
Potter Palmer, who founded the Chicago store that would become Marshall Field's, married Bertha Honoré Palmer, who became one of the most significant art collectors in American history. Bertha Palmer assembled an Impressionist collection of extraordinary depth: twenty-nine paintings by Monet (including nine from the Haystacks series), eleven by Renoir, and works by Degas, Pissarro, and Cassatt. In 1893, she commissioned a major mural from Mary Cassatt for the Woman's Pavilion at the World's Columbian Exposition in Chicago. The Palmer collection, donated to the Art Institute of Chicago, forms the core of the museum's celebrated Impressionist wing — one of the finest in the world.
Collectors whose legacies became museums
Several department store figures produced collections of such scale and quality that they entered the permanent fabric of their countries' museum systems. The phenomenon is striking for its geographic breadth and for the calibre of the institutions that were shaped by these gifts.
Samuel Henry Kress, who built the S.H. Kress & Co. chain to 264 stores across the United States by the 1930s, devoted his fortune to assembling more than 3,000 works of European art, with a concentration in the Italian Renaissance. The collection included masterpieces by Giotto, Botticelli, Fra Angelico, Raphael, and Titian. In 1939, Kress donated nearly 400 works to the National Gallery of Art in Washington. After the war, the Samuel H. Kress Foundation distributed a further 700 Old Master paintings to eighteen regional museums. In total, the collection was dispersed across ninety institutions in thirty-three states — an act of cultural philanthropy without equivalent in the retail sector, which ensured that communities far from the major coastal cities could access works of the highest quality.
Percy and Edith Straus, whose family became sole owners of Macy's in 1896, assembled a distinguished collection of Italian Renaissance painting and sculpture, including works by Fra Angelico, Rogier van der Weyden, Albrecht Dürer, Lucas Cranach, and Hans Memling. In 1941, they donated the entire collection to the Museum of Fine Arts, Houston.
Stanley Marcus, president and chairman of Neiman Marcus, was a noted collector of art and rare books. He founded the Neiman Marcus Art Collection in 1951 and, with his wife Linda, built a significant collection of Southwestern art. The Dallas Museum of Art honoured his legacy with the exhibition "The Eye of Stanley Marcus" in 1994.
Multi-generational dynasties: the Moulin-Houzé family
Among all the families associated with department stores and art, the Moulin-Houzé dynasty of Galeries Lafayette stands apart — not only for the depth of its commitment but for its continuity across five generations.
Théophile Bader, who founded Galeries Lafayette, was himself a collector of Impressionist painting, establishing from the outset a link between the family's commercial enterprise and the art of its time. His descendant Ginette Moulin (1927–2025) sustained the tradition through the second half of the twentieth century, supporting artists of the second École de Paris — Serge Poliakoff, Jean Fautrier, André Lanskoy — at a time when their recognition was far from assured.
The most transformative figure is Guillaume Houzé, Théophile Bader's great-great-grandson. Houzé created the group's patronage directorate in 2010, established the “Fondation d'entreprise” Galeries Lafayette in 2013, and launched the Fonds de dotation Famille Moulin — a family endowment fund that now holds more than 400 works of contemporary art. He presides over Lafayette Anticipations, the production-oriented foundation whose programme and building are described in Part III. Under his leadership, the group has become a partner of the Centre Pompidou, the Musée d'Art Moderne de la Ville de Paris, Paris+ par Art Basel, ANDAM, and the Villa Noailles. Houzé is himself a recognised collector, and his activity has been described in the French press as embodying an "authentic cultural identity" inseparable from the commercial enterprise.
What distinguishes the Moulin-Houzé dynasty is not merely longevity but escalation: each generation has deepened and institutionalised the family's engagement with art, progressing from personal collecting to in-store exhibitions, to a corporate foundation, to an independent production institution. It is a five-generation arc from Impressionism to the commissioning of new work by living artists — a trajectory that mirrors, in microcosm, the broader evolution traced in this article.
The Tsutsumi dynasty: two generations, one cultural revolution
In Japan, the Tsutsumi family produced what is arguably the single most consequential act of art patronage in the history of department store retailing.
Yasujiro Tsutsumi (1889–1964), the founder of the Seibu group, established the Takanawa Art Museum Foundation in 1962, housing a collection of paintings, Buddhist statuary, lacquerware, and Oriental ceramics. The museum operated in Tokyo until 1981, when it was relocated to Karuizawa.
His son Seiji Tsutsumi (1927–2013) transformed this inheritance into something far more ambitious. A published writer and poet under the pen name Takashi Tsujii, Seiji Tsutsumi was unique among department store executives in combining literary and artistic sensibility with commercial leadership on a national scale. He founded the Seibu Museum of Art in 1975, the Sezon Museum of Modern Art in Karuizawa in 1981, and the Saison Foundation in 1987, funded from his personal resources, to support the performing arts. The scale of these achievements — approximately 260 exhibitions, a permanent collection of some 800 works, collaborations with the Whitney Museum of American Art — is documented in Part III. What matters here is the man: a poet who ran a department store empire, and who believed that art was not an amenity for customers but a responsibility of commerce toward society.
In 2012, the Japanese government recognised Seiji Tsutsumi as a Person of Cultural Merit — an honour that acknowledged what the art world had long understood: that his contribution to the cultural life of Japan, delivered through the medium of a department store group, was of national significance.
Contemporary figures: the tradition continues
The pattern established by these founders and dynasties continues in the present generation — adapted to contemporary institutional forms but driven by the same fusion of personal conviction and commercial leadership.
Guillaume Houzé, discussed above, is the most prominent European example. At Le Bon Marché, Patrice Wagner, as CEO, has overseen the implementation of the annual carte blanche programme and the continued development of the store's permanent collection — ensuring that the cultural ambition initiated by the Boucicaut family in the 1870s, and sustained by LVMH since its acquisition of the store in 1984, remains a defining feature of the brand.
In Asia, Adrian Cheng, the founder of K11 and an executive of New World Development in Hong Kong, represents a new model: the entrepreneur-collector who conceives an entire retail-and-cultural complex as an integrated act of patronage. K11 Musea, described in Part III, is not a store that happens to contain art; it is a vision of what the department store might become when its founder's identity as a collector is made architecturally inseparable from its identity as a retailer.
In Japan, the tradition takes a more institutional form. At Mitsukoshi, the art department, established in 1907, continues to operate as both a gallery and a commercial intermediary in the art market. At Takashimaya, the company's historical museum documents the store's role in art and culture, while the Takashimaya Foundation maintains an explicit mission to support emerging contemporary artists and to compensate for the limitations of the commercial gallery system — a philosophy that positions the department store as a patron in the fullest sense.
Conclusion: A Strategic Asset, Not a Cost Centre
The relationship between department stores and the visual arts is not a marketing tactic, not a recent discovery, and not a luxury that can be dispensed with when trading conditions deteriorate. It is a constitutive dimension of the format — present at its origins, sustained across every major market, and carried forward by founders, families, and institutions over more than 150 years.
The department store and the public museum were born in the same historical moment and share the same structural logic: the staging of objects in architecturally ambitious spaces, designed to provoke desire, curiosity, and aspiration. From the Boucicaut gallery of Salon rejects in 1875 to Lafayette Anticipations in 2018, from Dalí's shattered window at Bonwit Teller to Ai Weiwei's takeover of Le Bon Marché, from Mitsukoshi's first exhibition in 1904 to K11 Musea's permanent collection today, department stores have not followed the art world — they have, at critical moments, led it, bringing the avant-garde of every era to audiences that established cultural institutions could not or would not reach.
The twenty-first century has seen this relationship cross a new threshold. What was once an in-store gallery or a patron's personal collection has become, in the most advanced cases, an independent foundation with a dedicated building and a production budget (Lafayette Anticipations), a permanent sculpture programme curated by a national arts institution (Selfridges and Yorkshire Sculpture Park), or an entire architectural complex conceived from the outset as a fusion of museum and retail (K11 Musea). At the same time, department stores have entered the commercial art market directly (Saks Fifth Avenue's fine art collection) and have been admitted into the institutional calendar of the art world itself (KaDeWe at Gallery Weekend Berlin). The boundary between the department store and the cultural institution is no longer blurred — in several significant cases, it has been deliberately dissolved.
For the leaders of the sector, the implication is clear. Art is not a cost centre to be optimised. It is part of the founding DNA of the department store — an inheritance carried forward, in the most successful cases, across generations by families whose personal passion became institutional identity. The Moulin-Houzé dynasty at Galeries Lafayette, Seiji Tsutsumi at Seibu, Bertha Palmer at Marshall Field's, Ernest Cognacq at La Samaritaine: these are not peripheral figures. They are central to what made their stores culturally significant — and, not coincidentally, commercially enduring. In an era when the department store must justify its existence against every other retail format, this history is not a sentimental indulgence. It is a strategic asset.
Appendix : A Practical Guide — Which Department Stores to Visit for Art
Paris
Le Bon Marché Rive Gauche remains the essential destination. Each January, a monumental carte blanche transforms the store. The permanent collection of contemporary art and design is visible year-round, and guided cultural tours are offered on the last Sunday of each month. Admission is free. Lafayette Anticipations (9 rue du Plâtre, Marais), the Galeries Lafayette foundation housed in a building by Rem Koolhaas, offers a production-oriented programme of contemporary art exhibitions. At the Galeries Lafayette Haussmann, the 1912 Gruber dome is itself a masterwork; temporary installations beneath it and the Galerie des Galeries on the first floor complement the architectural experience.
London
Selfridges offers The Art Block (contemporary sculpture, Duke Street entrance), Oxford Street windows regularly entrusted to leading artists, and institutional partnerships with major galleries. Fortnum & Mason hosts occasional exhibitions of modern and contemporary British art from the Frank Cohen Collection. Harrods maintains the Halcyon Gallery on its third floor.
Tokyo
Mitsukoshi Nihombashi operates an art gallery with four to five exhibitions per week spanning Japanese painting, international contemporary art, sculpture, and craft, alongside the Mitsukoshi Contemporary Gallery. Isetan Shinjuku features weekly contemporary art exhibitions in partnership with CADAN. PARCO Shibuya houses PARCO Museum Tokyo and Gallery X, dedicated to art and visual culture.
Elsewhere
De Bijenkorf in Amsterdam runs the "Room On The Roof" artist-in-residence programme. K11 Musea in Hong Kong, with more than 100 permanent works, offers a visit that is in itself a museum experience. La Rinascente in Milan presents regular artistic window commissions facing the Piazza Duomo. KaDeWe in Berlin participates in Gallery Weekend Berlin. The LOTTE Museum of Art in Seoul mounts international-calibre exhibitions within the Lotte Department Store.
Credits: IADS (Selvane Mohandas du Ménil)
IADS Exclusive: American Apparel after the myth
IADS Exclusive: American Apparel after the myth
American Apparel anticipated many of today’s retail priorities, from sweatshop-free manufacturing and domestic production to real workers in low-fi, unretouched campaigns — before any of these had become standard commercial expectations. At its peak, the brand sold a worldview in which a T-shirt carried values, politics and aspiration. And yet, within a decade of becoming one of the most recognisable fashion brands of the 2000s, it had entered a prolonged crisis, embroiled in scandals and business challenges: founder Dov Charney was suspended in 2014, the company filed for Chapter 11 bankruptcy protection in 2015 and again in 2016, and Gildan acquired the brand and selected assets in 2017.
That trajectory is, above all, a governance story: the reputational damage followed from the governance failure, not from a separate cause. American Apparel was early to many ideas that now dominate retail strategy: local manufacturing, ethical production, real people in campaigns, cultural immediacy and a rejection of over-polished fashion imagery. But the organisation behind the brand did not mature at the same pace as its cultural relevance.
That is precisely the argument the 2025 IADS White Paper, DEI at a crossroads in retail, developed at sector level: that DEI cannot function as a communications layer applied to a weak culture, and that it requires embedding in leadership, operations, governance and everyday behaviour. American Apparel demonstrates what the White Paper describes: DEI claims that lived in the brand's external positioning, not in the governance structures behind it, and a decade of conditions that could not protect what the brand was promising.
Its collapse is a warning about what happens when cultural relevance outpaces institutional accountability. For department stores, that argument has a direct operational implication: brand evaluation needs to reach behind the brand story and into the governance, complaint-handling and founder dependency of every significant partner.
What American Apparel built
A basics business with cultural charge
American Apparel built desire around everyday items: T-shirts, sweatshirts, leggings, bodysuits, crop tops, disco pants, hoodies, and underwear. It built a business around an idea that would not have a category name for years: that the most functional items in a wardrobe were also the ones most open to carrying cultural meaning.
Its clothes existed inside a larger story: Los Angeles, youth, sexuality, anti-corporate energy, domestic production and a rejection of glossy fashion perfection. Its 2014 annual report described the company as a vertically integrated manufacturer, distributor and retailer of fashion basics based in downtown Los Angeles.1 As of March 2015, it had approximately 10,000 employees, 239 retail stores in 20 countries, and a global e-commerce site serving more than 50 countries.
American Apparel’s “sweatshop-free” positioning gave its basics a moral dimension. At a time when much of the apparel industry had moved production offshore, the company promoted its Los Angeles manufacturing model as proof that fashion could be produced differently. The commitment to domestic labour had measurable substance. According to contemporary reporting, the average American Apparel factory worker earned between $80 and $120 per day, compared with $30 to $40 at most other Los Angeles-based garment factories during the same period.2 Employees also received subsidised lunches, health care, English-language classes and transit passes. The commercial logic behind local, ethical manufacturing was sound. That the same company simultaneously normalised conduct in its creative and management operations that contradicted those factory standards is not a simple contradiction. It reflects the case's most precise structural finding: the same concentrated authority that produced genuine worker welfare in the factory produced unaccountable conduct in the parts of the organisation that authority reached most directly. American Apparel's production model anticipated what would become a mainstream retail expectation. The failure came because the company did not build the governance and culture needed to sustain it once it had grown to 239 stores, 10,000 employees and operations across 20 countries.
When authenticity became exposure
American Apparel's advertising was equally distinctive: internally developed, visually direct and deliberately provocative. Its annual report described its campaigns as “edgy, high-impact, and visual.” The brand’s imagery often used real people, including employees and street-cast models, in low-fi, unretouched images.3
But the same strategy also created risk. The campaigns were frequently criticised for sexualising women and young-looking models. The company’s aesthetic became inseparable from questions about power, consent, and exploitation.4 What looked like authenticity to some audiences looked like predation to others. The deeper issue was that American Apparel’s identity became inseparable from Dov Charney, who was also the company’s chief executive. His taste, politics, instincts and behaviour shaped the product, advertising, workplace culture and public story. The company’s strongest differentiators (provocative campaigns, local manufacturing, and anti-corporate voice) lived too heavily on one person. For a young founder-led company, that can look like creative energy, but for a global retailer, it becomes a governance exposure.
How the business unravelled
Financial pressure exposed operational weakness
American Apparel did not collapse overnight. By the time its leadership crisis reached public view, the company was already under financial pressure. Its 2014 annual report shows total net sales falling to $608.9 million from $633.9 million in the previous year, and a net loss of $68.8 million.5 Several weaknesses converged, but two were structural: governance dysfunction as Charney's conduct became unmanageable, and the reputational damage that followed. These accelerated the financial pressure that overexpansion and declining traffic had already created.
In June 2014, American Apparel’s board suspended Charney as president, CEO, and chairman, and stated its intention to terminate him for cause after a cure period.6 The company’s SEC-filed announcement said the decision stemmed from an ongoing investigation into alleged misconduct. The same announcement warned that the management changes may have triggered an event of default under the company’s credit agreements.7 Founder risk had become a capital-structure issue: lender confidence, debt agreements and business continuity were now bound up in a single individual's conduct.
American Apparel’s workplace culture was often described as creative, intense, and start-up-like. Former employees have spoken about being given responsibility quickly, moving between retail, creative and operational roles, and feeling part of something larger than a clothing company.8 Yet the same informality also created serious exposure. The workplace appeared to operate with weak boundaries between professional life, personal loyalty, sexuality, creative production and founder access. Former employees interviewed in recent documentaries and reporting have described a workplace where sexually explicit behaviour was normalised, employees were expected to be constantly available, and Charney’s private home became part of the company’s informal power structure.
The founder’s behaviour became a governance problem
Allegations of sexual harassment and inappropriate workplace behaviour had accumulated around Charney for years before they reached the boardroom as formal governance issues. Several claims were dismissed, settled or moved into confidential arbitration, partly because employees had signed agreements channelling complaints away from public litigation.9 Charney has denied all allegations against him.10 Still, the pattern shows a company spending significant organisational energy managing conduct risk around the person most closely identified with its brand, while it was trying to address serious financial and operational pressures.
The ethical problem was structural: power was concentrated in a single individual who controlled the brand, creative direction, hiring culture, employee access and public narrative. In that environment, professional opportunity could become difficult to separate from personal loyalty or implicit pressure. American Apparel's advertising often used employees and street-cast models, while former employee accounts describe a workplace where sexualised behaviour, late-night access to Charney and blurred boundaries between work and his private home were normalised11. When creative visibility, career advancement and proximity to the founder are all controlled by the same person, employees may not feel they are operating on equal terms. American Apparel's ethical contradictions were embedded in its operating model. The brand built commercial credibility through claims of fairness (sweatshop-free production, real workers, transparent supply chains) while reportedly tolerating internal conditions that contradicted those claims.
The conduct pattern and the governance conditions that sustained it came from the same structure: authority and creative control concentrated in one person, with no mechanism to challenge the culture that concentration allowed. By the time Charney was suspended in 2014, those conditions had been building for a decade.
What remains of American Apparel now
Gildan bought the name, not the old machine
American Apparel still exists, but not in the form consumers knew in the 2000s. In January 2017, Gildan won the court-supervised auction to acquire the American Apparel brand and certain assets. Its final cash bid was approximately $88 million and included worldwide intellectual property rights and certain manufacturing equipment. Gildan also stated that it would separately purchase inventory but would not purchase any retail store assets.12
Gildan acquired the name, but the Los Angeles factory, the physical store network, the founder-led creative machine and the original subculture context did not transfer in the same form. American Apparel became a brand asset within a portfolio, rather than a stand-alone cultural retailer.
A narrower, safer, more conventional brand
Today’s American Apparel is much narrower than the original. Its FAQ states that it does not currently have store locations and that Amazon is now its first-party retailer, with plans to expand to other retail channels in the future. The production story has also changed. The brand’s FAQ states that its products are made in sweatshop-free facilities around the world, including the US. The result is a safer, more conventional American Apparel.
For department stores, the Gildan acquisition illustrates the gap between brand recognition and brand substance. What Gildan acquired was the name; what it could not acquire was the business model that had originally made the name matter. That the brand continues to trade on Amazon without the factory or the values story does not disprove that those things created commercial premium at the time. It shows that name recognition, once built, outlasts the conditions that built it. The department store question is not whether the name still sells; it is whether it sells at the same premium without the substance behind it.
What happened to Dov Charney
Dov Charney did not disappear after American Apparel. In 2016, he founded Los Angeles Apparel, a new company built around many of the same ideas that defined American Apparel before its retail expansion: domestic manufacturing, vertical integration, wholesale basics and sweatshop-free production.13 Nearly a decade after its founding, the company continues to operate on the same model. Its own materials describe a vertically integrated structure, a starting wage of $20 an hour, and garment workers earning up to $35 an hour with productivity bonuses. In 2025, it opened a flagship of more than 20,000 square feet in SoHo, New York, its first retail expansion beyond its Los Angeles base.14
That continuity does not establish Los Angeles Apparel as a comparable commercial success; revenue and profitability are not public. What it does establish is that the operating model has continued demand at a contained scale: a single Los Angeles facility, wholesale distribution and no investor pressure to expand to 239 stores across 20 countries. What American Apparel never built was the specific set of structures the model required as it grew: a complaints process that ran outside the founder's authority, a board empowered to intervene before conduct became a capital-structure event, and hiring practices that did not make career opportunity contingent on personal access to one person.
At the same time, Los Angeles Apparel has faced its own scrutiny. During the COVID-19 pandemic, Cal/OSHA15 cited Los Angeles Apparel after an inspection that began in July 2020.16 The citation document refers to COVID-19-related illnesses and fatalities among employees and failures to record fatalities on OSHA forms. The citation points to the same structural gap as American Apparel, and it complicates the case's lesson in a useful way. The governance failure at American Apparel was partly about growth: a model that might have been sustained at a smaller scale, with the accountability structures it never built. Los Angeles Apparel tests that reading. Operating at a fraction of American Apparel's scale, without the pressure of 239 stores or public investors, it shows the same founder-accountability gap. For department stores, both lessons apply: ask whether a founder-led brand is building governance as it grows, and ask whether the model, at any scale, is capable of being held accountable by someone other than its founder.
What department stores should learn
When curation stops at the brand story
Department stores are in the business of curation — of products, yes, but also of the organisations, supply chains, and workplace cultures those products represent. Every brand carried, every concession hosted, and every exclusive collaboration signals something about the department store's taste, values, and judgment. American Apparel shows why a brand can have strong product relevance, cultural visibility and customer loyalty and still carry serious governance and culture risks that commercial review alone will not surface.
American Apparel shows what those questions are. How does a brand treat workers, and is there evidence beyond the marketing? American Apparel's factory wages were documented; its internal harassment was not. How are complaints handled when they involve the founder? American Apparel routed them to confidential arbitration. Can the business survive without a single dominant individual? American Apparel's lenders found out only when Charney's suspension triggered a potential event of default. These are the questions that belong in brand evaluation before a partnership is signed, not after the brand makes news.
Values-led branding needs proof
American Apparel's story also shows where ethical claims hold and where they break: the claims that could be independently audited held; the ones that depended on the founder's personal accountability did not. "Made locally", "sweatshop-free", "sustainable", "inclusive" and "community-driven" can all create consumer trust, but only when supported by wage transparency, independent grievance channels and clear accountability for leadership behaviour.
American Apparel illustrates the documentation gap directly: its wage claims were widely cited in contemporaneous reporting; its governance, harassment reporting structures and board-level accountability remained insufficient to contain the risks around its founder. The failure takes different forms across values-led brands. Everlane built its following on "radical transparency" but disclosed only what supported the brand. When the company faced a union drive and internal culture allegations, the transparency did not extend there. Reformation built a sustainability-led identity while its internal culture contradicted it; in 2020, allegations from former employees prompted its founder to step down and the company to commit to new diversity governance structures.17 The failure modes were distinct; the structural condition was the same: a founder whose authority defined both the ethical positioning and the limits of accountability around it.
In March 2024, the UK Competition and Markets Authority secured formal undertakings from ASOS, Boohoo and George at Asda requiring environmental claims to be accurate, clear and specific.18 Wage data and factory conditions are verifiable through reporting and third-party audits. Governance accountability and campaign ethics require a different set of questions: how complaints are handled, whether accountability mechanisms exist independently of the founder, and how people in campaigns are protected before and after they appear.
The relevant test for any authenticity-led campaign, as the ASA's 2009 and 2012 rulings against American Apparel established in practice, is whether the people in it held meaningful power over how they were represented: the ability to refuse, to set conditions on their appearance, and to exit without professional consequence. American Apparel's advertising record shows how "real people" branding can function as a legitimising strategy rather than a protective one. In 2009, the UK Advertising Standards Authority banned a campaign that the brand defended on the grounds that its models were "real girls," often employees or friends of the company, unretouched, doing their own hair and makeup. The ASA found the images could be seen to sexualise a model who appeared to be a child.19 In 2012, a second campaign was banned for what the ASA described as a "voyeuristic quality" and the inappropriate sexualisation of a model who appeared to be a child.20 In both cases, the authenticity frame was the brand's defence of content that a regulator found harmful. Appearing in a campaign is not the same as having power within it.
Why this is a DEI and company culture case
Visibility is not inclusion
American Apparel looked, on the surface, more inclusive than many of its peers. It used real people in advertising, employed a diverse workforce, promoted sweatshop-free manufacturing and took public stances on social issues. That distance between brand and practice was, at American Apparel, structural rather than incidental. The gap between the two was not abstract. American Apparel ran the “Legalize LA” campaign, took out political ads calling immigration enforcement an “apartheid system,” and gave thousands of employees paid time off to march in the annual May Day immigration rallies.21 In 2009, after an ICE audit found documentation discrepancies for approximately 1,800 workers, the company terminated their employment.22 The brand that most publicly championed immigrant workers was the same organisation that, under legal pressure, dismissed them. The advocacy was not cynical: the campaign spending, the political ads and the paid time off for immigration rallies were substantive commitments. What the organisation lacked was any institutional structure that could protect those commitments when an external legal event made them costly to maintain.
A company can put real workers in every campaign and still have unequal power inside the organisation. It can champion immigrant workers in public and still dismiss them when a regulator calls. It can celebrate women in advertising while tolerating a workplace where career advancement depended on access to the founder. None of that is prevented by progressive language: at American Apparel, employee complaints had nowhere to go outside the culture being challenged. The gap between brand and practice, between what an organisation claims about fairness and what its people experience, is what American Apparel failed to close.
Culture is what the organisation permits
American Apparel shows that inclusion fails when governance fails: not through a deficit of intention, but through the absence of the mechanisms to enforce it. When misconduct is not addressed, when power is concentrated, when employees lack safe reporting channels, and when leadership is insulated from consequences, inclusion is structurally impossible. This connects directly to the broader argument of the IADS’ 2025 White Paper, which holds that DEI becomes meaningful when it is tied to strategy, accountability and measurable outcomes. American Apparel's case shows what those connections look like when they are absent: no accountability structure existed independently of the founder, and none survived his removal.
Stated values are aspirations. What an organisation permits, rewards and fails to challenge is the evidence. At American Apparel, the institutional failure was not the existence of misconduct allegations but the absence of mechanisms to surface and address them before they became structural liabilities. “Tone at the top” is necessary but not sufficient. For department stores specifically, the missing mechanism is at the point of brand selection: a governance and culture assessment applied alongside the commercial review, as a standard condition of partnership rather than a response to crisis.
American Apparel's story is often reduced to the rise and fall of a provocative founder. That reduction obscures what is most useful about the case: the company was culturally brilliant and institutionally weak, and understanding how those two conditions coexisted is what makes it diagnostic for retail leaders rather than merely cautionary. American Apparel had genuine cultural foresight: it recognised that consumers would pay for a product tied to traceable values (domestic production, ethical labour, cultural identity) before social media made authenticity commercially mandatory. However, it did not build the governance structures to protect what it had created: the independent complaints process, the board oversight that did not wait for lenders to force the issue, the hiring practices that did not make career opportunity contingent on proximity to one person. For department stores, a brand partner's cultural credibility and its institutional resilience are different properties, evaluated through different questions. The American Apparel case demonstrates the cost of asking only one: whether the brand has a compelling story, without asking whether the organisation behind it can sustain that story. Values, culture and inclusion are not self-sustaining: at American Apparel, each depended on one person's authority rather than on structures that existed independently of him.
Credits: IADS (Maya Sankoh)
IADS Exclusive - How department stores are playing the 2026 FIFA World Cup
IADS Exclusive - How department stores are playing the 2026 FIFA World Cup
The 2026 FIFA World Cup is the largest in the tournament's history: 104 matches across 16 cities in the United States, Mexico and Canada (40 matches more than the last edition), running from 11 June to 19 July, with an estimated six billion people — roughly three-quarters of the planet — expected to engage with it. For scale, the Paris 2024 Olympics drew around five billion viewers. The magnitude of the audience makes headlines, but the actual impact comes elsewhere: audiences have only a modest national effect, with the main beneficiaries being host cities through tourism, services, and consumption. As a result, the most interesting story may not happen on the pitch but in retail, especially in department stores that are seizing the moment as both a business opportunity and a chance to become cultural destinations. Here's how the biggest names in retail are playing the game.
The economics: large in aggregate, modest in practice
A vast audience, a small footprint
The macroeconomic case for the World Cup is surprisingly thin. The U.S. is projected to gain approximately $17 billion in incremental GDP — less than 0.1% of annual output. Canada's impact is similarly marginal at around 0.1% of GDP. Mexico is the relative winner: with 13 matches generating an estimated $3 billion in economic benefit, the impact represents between 0.2% and 0.5% of GDP, a meaningful uplift by comparison. Mexico is also expected to benefit from tourism, as tightened U.S. immigration controls may dampen international arrivals to the largest host nation. Around 5 million visitors are anticipated in Mexico, generating tourism revenues exceeding $1 billion.
The real commercial action, however, is not at the national level. It is highly localised and concentrated in host cities and in the strategies of brands and retailers willing to invest in the moment.
The sportswear equation
Adidas, Nike and Puma collectively kit out more than 75% of the 48 participating nations. Adidas leads with 14 national teams, followed by Nike with 12 and Puma with 11. With North America accounting for over 40% of Nike's annual revenues, the brand enters this tournament with a structural home advantage and estimates the tournament could generate $1.3 billion in incremental revenue. Adidas projects a comparable $1.2 billion uplift. Retailers stocking Nike products have committed to offering 40% more football merchandise by volume than during Qatar 2022, when an estimated 14.4 million shirts were sold. Projections for 2026 range from 18 to 23 million units, with the three major brands expected to capture 80% of that market.
With the demand for football products largely pre-allocated to mono-brand stores and sportswear retailers, the strategic question for a department store is elsewhere: what to do with a sport they don't necessarily own? Also, what does the World Cup mean for footfall, dwell time, brand perception, and customer acquisition?
El Palacio de Hierro: the full playbook
The tension every premium retailer has to resolve
Football is mass, emotional and culturally democratic. A premium or luxury department store like El Palacio de Hierro is none of those things by default. The instinct to drape the building in tournament colours would lack credibility with customers accustomed to more elevated store communications.
El Palacio de Hierro articulated this tension clearly. With Mexico having hosted in 1970 and 1986 — both woven into national memory — the 2026 edition carries emotional weight. But the company understood it could not wrap itself in soccer colours and claim authenticity it does not have. Instead, El Palacio de Hierro positioned itself as the stage on which the World Cup experience is elevated. The campaign's central premise, "if the World Cup brings the world to Mexico, El Palacio de Hierro sets the stage", aims at reconciling premium and mass through emotion.
Three phases for an unprecedented campaign
The warm-up phase activates Noches Palacio, the store's flagship loyalty promotion. The mechanic (purchases earn coins, coins are redeemed for tiered prizes at the end of each promotional weekend) creates urgency and repeat visits. Crucially, as observed by El Palacio de Hierro in the first days, the promotion has proven to attract both loyal, affluent customers and new entrants, serving as a retention and acquisition tool simultaneously. Live music, performers, F&B programming and World Cup theming transform participating stores into destination experiences.
The pre-tournament phase shifts to experiential and pop-up activation. The standout is a branded pop-up that deliberately juxtaposes brands that do not typically coexist in luxury retail: Adidas, Hisense, Don Julio and Buchanan's. The logic is curation beyond product selling: assembling a premium watch-party environment in which the purchase of merchandise, the consumption of premium spirits, and the viewing of a World Cup match become a single, continuous experience.
The match phase is the most commercially intensive: special gastronomy programming aligned to which national teams are playing on a given day, watch parties in the store's restaurants, and interactive installations, including the Palacio Arcade, a soccer-themed entertainment zone designed to extend visit duration across entire families.
Beyond the in-store programme, two additional initiatives deserve particular attention.
The Yellow Pitch, a publicly accessible soccer pitch built directly in front of the Durango flagship in Mexico City, is the campaign's most provocative element. It requires no purchase and is open to everyone. It is designed to generate organic social content and street-level energy. For a luxury retailer, it is an act of deliberate democratisation: the tension between free public access and luxury equity should result in a new form of brand authority for El Palacio de Hierro.
The luxury city guide, distributed to premium hotels and airport arrival lounges in Mexico City, Monterrey and Guadalajara, functions simultaneously as a tourist service, a brand ambassador and a commercial acquisition tool. It reinforces El Palacio de Hierro’s position as a cultural authority, helping visitors to make the most of their visit.
From New York to Stuttgart: same tournament, different perspectives
Bloomingdale's: the lifestyle and menswear lever
Bloomingdale's approach to the World Cup is to connect several commercial objectives at once: menswear growth, Father's Day gifting, host-city relevance and fashion discovery.
The flagship activation, Game Day with Boss, occupies the 59th Street Carousel pop-up space from June 4 through August 24, a timeline that deliberately extends well beyond the tournament. The assortment of approximately 200 products spans fashion, accessories, beauty, wellness and lifestyle, anchored by around 70 Boss exclusives, including a performance collection developed for the U.S. Men's National Soccer Team. The addition of curated vintage jerseys connects World Cup culture to fashion nostalgia, elevating merchandise into collectable territory.
The format is being replicated across six additional locations near host-city markets (SoHo in NYC, Aventura in Florida, Century City in Los Angeles, Lenox Square in Atlanta and Bergen County in New Jersey), with the SoHo store receiving an expanded version featuring FIFA 1904, a heritage-focused football collection. Father's Day activations on June 13 add a commercial layer, blending food, beverages and wellness experiences with the World Cup framing.
Bloomingdale's experiment suggests that a World Cup activation does not require deep soccer credentials or sportswear-only activations, but rather the definition of its own version of the World Cup. For Bloomingdale's, the answer is a focus on male customers embedded in a lifestyle approach.
Macy's: the inclusive community play
Where Bloomingdale's focuses on lifestyle aspiration, Macy's has built its activation around inclusion and community access. World Soccer HQ is a multi-brand activation spanning Nike, Adidas and Puma, avoiding any single-sponsor dependency. The more distinctive element is the partnership with the U.S. Soccer Foundation, directing investment toward grassroots soccer access in underserved communities. This is not cause marketing in the traditional sense, but an attempt to build emotional legitimacy with a soccer audience that the brand does not yet own.
The activation extends nationwide with live entertainment, athlete appearances, and product customisation events. Macy's is using the World Cup to make a claim about its role in American cultural life, not simply to sell merchandise.
Nordstrom: the sponsor-led merchandiser
Nordstrom's partnership with Adidas takes a different stance, built around product discovery, localisation and a structured cadence of weekly activations across 35 stores. Every Thursday brings new gift-with-purchase offerings and sweepstakes; every other week, an Archive Zone spotlights a historically significant Adidas piece linked to that week's featured country. Weekend programming is aligned to whichever national teams are in focus, a country-by-country journey through the tournament that gives customers a reason to return week after week. The $75 qualifying purchase threshold for customisation events is worth noting.
What about Europe? Breuninger and Manor
Mexico and the United States are not the only countries to reclaim their share of the event. Breuninger's approach is more localised. The Stuttgart flagship has transformed its signature Eduard's Bar into a dedicated sports bar with Adidas for the duration of the tournament. This conversion builds on the store's identity as a destination for gastronomy and community, not just retail, as demonstrated by Breuninger’s annual Fashion x Food events, which bring gastronomy and fashion together. The Adidas partnership, which in 2024 already produced the redesign of the flagship facade for the soccer European Championship, is being extended with World Cup-themed activations across multiple locations: jersey customisation pop-ups, exclusive product drops, and competitions for signed merchandise.
Manor’s One Game, One Love campaign for the FIFA World Cup 2026 features official national team jerseys from Puma, Nike and Adidas, as well as exclusive fan merchandise, lifestyle apparel, and collectable items, to attract sports enthusiasts without losing fashion customers. Creative collaborations, such as the limited-edition Football Bags by Geneva-based designer Joana Bender, anchor the store locally while mixing exclusive products with street style. The campaign’s themed activations and limited-time collections are designed to drive footfall, customer engagement, and cross-category sales during the tournament.
For department stores, the FIFA World Cup 2026 is not about soccer or promotions but about their strategic self-knowledge. The retailers that will emerge strongest are not those with the deepest soccer credentials, but those who answer the question of who they are and what this moment means for them. From that perspective, the World Cup is not a retail strategy or a must-have, but an additional opportunity to show more than just a house of brands and to become a host and experience curator, while increasing repeat visits and dwell time. As such, the initiatives will amplify whatever a retailer already does well, and whatever remains unconvincing.
Credits: IADS (Christine Montard)
IADS Exclusive: Everlane, Shein and the price of convenient transparency
IADS Exclusive: Everlane, Shein and the price of convenient transparency
Everlane made transparency its commercial proposition. Shein has now bought the remains of that proposition at a price shaped less by brand heat than by financial distress.
In May 2026, Everlane said it had reached an agreement to be acquired by Shein, the ultrafast-fashion platform IADS examined in its January 2026 Exclusive, ‘The Shein paradox: when digital ultra-fast fashion meets physical reality’. That article documented what happened when Shein tested that ambition at BHV Marais in Paris: 300,000 initial visitors gave way to near-empty floors within weeks, as in-store prices far above the online average undermined the very proposition that drove the brand. The Everlane acquisition extends the same question: can Shein acquire the trust it cannot earn, through a brand once built on radical transparency?
The reported price was about $100 million, although the companies did not publicly disclose financial terms. Six years earlier, Everlane had been valued at $550-600 million. By the time the sale was being discussed, the company had accumulated around $90 million in debt, and common shareholders were expected to receive no payout.
How Everlane weakened before the sale
Everlane, the San Francisco direct-to-consumer label founded in 2010, built its following on minimalist basics and a ‘radical transparency’ proposition: publishing product cost breakdowns, naming its factories, and showing customers how their clothes were made. In March 2020, as the pandemic shut down retail, Everlane laid off 42 of its 57 customer experience workers. Those workers had been organising a union since 2019 and had formally requested recognition weeks earlier. US Senator Bernie Sanders accused the company of using the crisis to union-bust. Three months later, a group of former employees released a document titled “Everlane’s Convenient Transparency,” alleging anti-Black behaviour, unequal advancement, bullying and a toxic internal culture. Everlane’s founder and then-CEO Michael Preysman acknowledged that the company had “urgent work to do to rewrite its code of ethics.”
Everlane was transparent, where transparency supported the brand. Where transparency would have exposed how the company itself operated, it went quiet. That mattered because transparency was not a communications theme for Everlane; it was the reason customers accepted the price. Once that trust broke in 2020, Everlane lost the distinction that had separated it from a crowded field of brands selling clean aesthetics, minimalist basics and ethical language.
Later, the repositioning backed by L Catterton turned that credibility problem into a pricing problem. L Catterton, the consumer-focused private equity firm created through a 2016 partnership between Catterton, LVMH and Groupe Arnault, invested in Everlane in 2020, the same year the culture document broke, and was reported as its majority owner by the time of the Shein sale. Under that ownership, Everlane was pushed upmarket, toward the territory occupied by Theory and Frankie Shop — a poor fit for a brand that had trained customers to accept its prices by explaining what went into them. Moving closer to premium fashion asked those same customers to pay more for a brand whose ethics promise had already been broken.
In 2022, Everlane announced a $25 million term loan from Gordon Brothers. The wording of the announcement presented the facility as support for growth and sustainability. The lender profile told a different story. Gordon Brothers describes itself as a global advisory, restructuring and investment firm. Its retail work has included distressed and restructuring-linked situations, such as Laura Ashley, Brooks Brothers, and Toys “R” Us.
That was a form of convenient transparency in its own right. Everlane disclosed the loan and described it as growth capital. It did not dwell on what it meant for a brand built on trust to depend on a restructuring specialist — a brand that had built its following by showing customers exactly what their clothes cost to make, and was now calling a restructuring facility growth capital.
Everlane had also taken on a $65 million revolving credit facility from CIT Northbridge in September 2022. Together, the two facilities brought its debt load to around $90 million. Revenue had reportedly slipped from $198 million in 2024 toward $170 million by early 2026, while the business was close to breaking even rather than turning a profit on the capital behind it.
By March 2026, L Catterton was reportedly seeking investors to address the debt problem. There were also reports of overdue rents at Everlane’s San Francisco offices. When no investors emerged, the board approved the Shein deal. Preysman had stepped down as CEO in 2021, formally moving into the executive chair role in January 2022, and had left Everlane’s board earlier in 2026. He reportedly found out about the sale from the news.
What Shein bought
Of the arguments behind the deal, the logistics case is the least discussed and the most consequential. Shein’s US model had benefited from shipping low-value parcels directly to consumers. The end of the de minimis threshold (the US duty exemption on packages under $800) for China and Hong Kong changed the equation. Everlane gives Shein something it cannot acquire under its own name in the US market: domestic brand credibility. On the reported numbers, the math is hard to ignore: a $100 million valuation against approximately $90 million in debt leaves almost nothing once the debt is set against the sale price. Shein was not paying a rich price for the romance of 'radical transparency.' It was buying a US brand footprint, domestic operating knowledge, a higher-income customer file and a cleaner story to tell investors.
Maxine Bédat, founder of the New Standard Institute, a nonprofit developing transparency and accountability standards for the fashion industry said Shein was looking for “access to a higher price point, a marketplace that is more higher-end.” Everlane gives Shein a customer it could not easily reach under its own name: older and more affluent.
The IPO logic is also visible. Shein’s listing ambitions have been delayed by scrutiny over labour practices, supply chains, and data privacy. Neil Saunders, managing director of GlobalData’s retail division, described Everlane’s function directly: “Everlane is not revolutionary for Shein, but it does support a narrative of having a more balanced portfolio that can be sold to potential investors during any future IPO.”
Alfred Chang, who became CEO in 2021 following Preysman’s transition to executive chair, has defended the sale by saying Everlane will remain independent, keep its standards and use the partnership to expand its mission. That defence answers the wrong question. A subsidiary can maintain its own sourcing rules while its parent company’s total greenhouse gas emissions rise 81% in a single year. Whether Everlane preserves its ethics policy does not change what Shein ships globally. Sustainability, for Everlane’s customers, will now be judged against the parent company’s aggregate footprint, and that footprint keeps growing.
The supply chain argument… and its limits
Shein’s make-to-sell model produces small batches in response to real-time demand signals, then scales only when data confirm interest. Compared with traditional fashion forecasting, where brands order months ahead, warehouse excess inventory, and mark down what fails to move, Shein’s model can reduce waste per item. Chainge Capital, a supply chain advisory firm, has noted that Shein “makes five and sells five” in an industry that typically “makes ten to sell three,” achieving sell-through rates close to 100% against an industry average where 40-50% of goods end up discounted or unsold.
Analysts argue that the distinction goes deeper: Shein is not simply a faster fashion retailer, but a data-led supply chain business that happens to sell clothing.The efficiency is real, but it is measured per item. At Shein’s scale, the harder question is whether near-100% sell-through reflects responsive demand, or demand continuously stimulated by the pace of assortment refresh.
In 2025, Greenpeace Germany reported that 18 of 56 Shein products tested contained hazardous chemicals above EU legal limits. For Everlane's customers — whose decisions were shaped partly by sourcing claims, material safety, and factory standards — the Greenpeace result is a direct product-safety finding, not a general sustainability concern. It is a direct challenge to the type of product trust Everlane sold. Shein’s absolute greenhouse gas emissions rose by 81% in 2023, growing faster than revenue. Its demand-responsive production may reduce some per-item inventory waste, but it does not offset the footprint of an enormous assortment, high volume, and frequent deliveries: its reported transport emissions rose 13.7% to 8.52 million metric tons of CO2 equivalent in 2024, more than three times the transport emissions reported by Inditex.
This is where Chang’s defence runs into the numbers. A brand can keep its own sustainability language and still sit inside a corporate model whose aggregate impact keeps climbing. Shein may reduce waste on a per-item basis, but Everlane's customers will now judge the brand inside a parent company defined by scale, speed, chemical-risk scrutiny and transport emissions.
The EU’s Ecodesign for Sustainable Products Regulation (ESPR) is about to turn that direction into law. Everlane may be a US brand, but Shein’s European footprint means the combined entity faces these obligations directly. The destruction ban for unsold apparel, clothing accessories and footwear applies to large companies from 19 July 2026, while disclosure rules already apply to large companies, requiring them to report the number and weight of unsold products discarded and the reason for their disposal[19]. Broad sustainability language will not be enough.
Three exits, three numbers - Everlane is now part of a comparison set
Allbirds, the New Zealand-founded direct-to-consumer footwear brand known for sustainable materials such as merino wool and sugarcane-based foam, went public in 2021 and reached a market value of more than $4 billion. In early 2026, it agreed to sell its brand and footwear assets to American Exchange Group for about $39 million. Everlane, once valued at $550-600 million, exited at a reported $100 million, with common shareholders expected to receive nothing. Quince, which sells minimalist clothing essentials, accessories, and home goods with ethical sourcing claims at materially lower prices, raised $500 million in March 2026 at a $10.1 billion valuation.
Swap Commerce, a commerce infrastructure platform working across returns, cross-border commerce and recommerce, captured the failure pattern across several mission-driven brands: “Allbirds, Outdoor Voices, now Everlane – mission-driven brands with genuine cultural cachet, undone not by a lack of purpose, but by a lack of operational foundation. Everlane had the audience, just not the engine.” Quince is the contrast case from the same period: same minimalist positioning, same ethical sourcing claims, but a price point built to compete rather than justify. The Kearney Consumer Institute named the pricing problem: “The biggest challenge with any value-based product is the price has to be right for the right consumer. And Everlane, I think, just was exposed to a category that got crowded.”
The timing of the two deals is worth holding together. Quince raised $500 million in March 2026 at a $10.1 billion valuation. Weeks later, Everlane was being sold to Shein at a reported $100 million, with around $90 million in debt. Quince and Everlane sat at different stages, so this is not proof that cost structure alone sank Everlane. But it does show that capital was still available for minimalist basics with ethical sourcing claims, backing the version that priced more aggressively. Everlane charged a premium for transparency. Quince made transparency part of the baseline and competed on price, though Quince's sourcing claims have yet to face the same scrutiny that broke Everlane's.
What this means for department stores
Inditex can be taken as a point of reference as it did what Everlane could not: it moved parts of the offer upward without losing control of price, speed or inventory risk. Zara's premiumisation has been backed by larger stores, stronger presentation, designer collaborations and a supply chain that can still react within the season. At the same time, Inditex has used Lefties to answer lower-price demand without forcing Zara itself into a direct race with Shein. IADS documented the outcome of a direct test: when Shein opened at BHV Marais in Paris in November 2025, 300,000 initial visitors gave way to near-empty floors within weeks — higher in-store prices and a limited selection could not transfer the endless-assortment, low-price proposition that drives the brand online. That case study is set out in full in IADS Exclusive, ‘The Shein paradox: when digital ultra-fast fashion meets physical reality.’
In 2025, Inditex reported €39.9 billion in sales and €6.2 billion in net income. It has continued to optimise its store base, reducing store count while increasing the weight of larger, better-integrated flagships. Zara has moved parts of its offering upmarket through higher-quality fabrication, designer collaborations, and more premium store environments. At the lower end, Lefties gives Inditex a separate vehicle for price-sensitive demand. Lefties grew 17.44% to €644.81 million in the year to January 2025, moving from a small loss to a profit of €21 million. Inditex is not asking a single brand to cover every price tier at once.
As IADS set out in a previous Exclusive on Zara’s strategic evolution, Zara’s speed is not a merchandising habit; it is built into sourcing geography. Roughly half of its production is near-shored in Spain, Portugal, Morocco, and Turkey for fast-turning items, with Asia reserved for basics – a dual-speed supply chain that lets the brand react to trends mid-season while competitors are locked into collections planned six months ahead. That architecture is not transferable for department stores if they place wholesale orders up to six months before delivery.
The buying problem and the compliance problem are the same problem: the data ESPR requires retailers to disclose is the same data buying teams need to catch over-ordering before the season closes .A retailer that cannot report its discarded unsold products does not just have a reporting gap — it lacks the inventory visibility that would have caught the excess before it built.
What Everlane’s former CEO and founder concluded
Preysman’s response to the sale was immediate: “appalled.” Within days, he launched Still Radical, a new venture presented as having no venture capital and no private equity.
His diagnosis is clear: private equity killed Everlane. Once L Catterton held majority control, the final decision belonged to investors whose obligations were financial, not philosophical. But this diagnosis leaves too much out.
Preysman ran Everlane for eleven years. He was CEO during the 2020 union controversy. He was the executive chair when former employees documented allegations of racism and toxic culture. He sold his shares to L Catterton in 2020, beginning the ownership transition he now criticises.
Industry observers put part of the problem in founder terms: “When Michael Preysman stepped back after L Catterton took majority control, Everlane lost its centre and never recovered it. The brand’s identity lived inside one person and left with him.”
Everlane’s identity depended too heavily on its founder, and its internal practices did not consistently support its external promise. Both weaknesses were present before L Catterton became the controlling investor. Avoiding venture capital answers the financing lesson. It does not answer the trust lesson. Preysman has not said what happened to the 42 customer experience workers let go in 2020, or what Still Radical would do differently in the same situation.
Here, the timing turns from coincidence to choice: Preysman sold his stake to L Catterton in 2020, the same year the union controversy and the culture document broke. He sold while the brand still carried much of its market credibility. Revenue had not yet collapsed. That makes the timing harder, not easier, to explain away: Preysman exited before the trust damage had fully shown up in the numbers, leaving later owners to manage the financial consequences of a credibility problem that began under his leadership.
Revenue held near $200 million through 2024, including $198 million in that year, so the trust break did not kill the company at once. It capped what the brand could credibly ask from customers. Everlane could still sell accessible basics to people who liked the product. What it could no longer do easily was ask those customers to follow it upmarket on the strength of an ethics-led promise. The damage became terminal when L Catterton pushed prices above that ceiling. Debt that was manageable at $200 million in revenue became harder to carry as revenue fell toward $170 million, and the premium strategy produced no growth. The Shein sale followed from that.
Everlane could publish the cost of a product. It could not show that its ethics held when they were costly.
Credits: IADS (Maya Sankoh)
IADS Exclusive: The end of the nudge - reclaiming influence in the era of overstimulation
IADS Exclusive: The end of the nudge - reclaiming influence in the era of overstimulation
Retailers have long drawn on behavioural techniques, nudges, to persuade consumers to purchase. Some have given rise to eponymous concepts like the ‘IKEA effect’ where consumers attribute higher value to products assembled themselves, fostering brand resonance. In digital advertising, nudges include complete-the-look carousels, star ratings, and one-click shoppable ads on social media. However, the implicit assumption is that consumers pay attention to these. But does this remain true in 2026?
Economists now treat human attention as a scarce resource comparable to land, labour, and capital reflecting that attention is finite, rivalrous, and exhaustible. Social media platforms have industrialised the harvesting and monetisation of attention, creating a paradox: the more content floods the environment, the less effective each individual message becomes. In this context of structural overstimulation, brands including Gentle Monster and New Balance are moving from persuading through exposure to cultivating cultural belonging, offering a new angle to a job department store historically used to excel at: shaping their communities’ culture.
The commodification of attention
Nobel Laureate Herbert Simon theorised the “attention economy” in 1971, stating that ‘a wealth of information creates a poverty of attention.’ He identified attention as the finite resource that limits action in information-saturated environments. Attention has emerged as the currency of the digital era where platforms compete for user engagement by deploying algorithms designed to retain monetisable eyeballs. An unending stream of short-form videos ensures that stimulating material keeps individuals scrolling, transforming focus into a coveted commodity. On average, TikTok users spend 58 minutes daily on the platform, but only 1.7 seconds viewing each piece of content, with teenagers toggling between apps every 44 seconds.
Social media platforms have built trillion-dollar enterprises by monetising the extraction of human attention. Platforms offer free services while harvesting personal data (browsing patterns, micro-interactions, location, emotional states) to build behavioural profiles enabling micro-targeted advertising, sold in real-time programmatic auctions. These platforms use variable reinforcement schedules (the same mechanism that makes gambling addictive) through notifications, likes, and algorithmic content serving as unpredictable rewards triggering compulsive engagement
. Shoshana Zuboff’s framework of “surveillance capitalism” calls this converting raw behavioural data into ‘prediction products’ sold to advertisers seeking to influence future purchases. Social media ad revenue grew +36.7% in 2024, with Meta, Google, and Amazon together representing 62% of total worldwide digital ad spending in 2026. Deloitte found that social platforms capture over 50% of US ad spending, with 63% of Gen Z and 49% of Millennials saying that social media ads are most influential on purchasing decisions.
Retail media has emerged as a force in the advertising ecosystem by capitalising on first-party data but does not inherently address the broader issue of attention attrition. Retail media is becoming a priority for department stores, with David Jones investing $250 million in its Amplify retail media arm, Falabella hosting Fmedia Day for brands and sellers, and Breuninger strengthening its retail media infrastructure to address customers and brands. Despite using proprietary data such as purchase histories, search behaviour, and loyalty programme insights, to enable hyper personalised advertising, it is increasingly insufficient to engage already overwhelmed consumers.
AI is simultaneously accelerating attention extraction and disrupting the ecosystem through which it is monetised. Fitch Ratings estimated a 15% decline in global search traffic as of June 2025 due to AI-generated summaries. Bain & Company estimated 80% of internet users receiving answers on search pages without clicking external links, reducing traffic for advertisers by up to 25%. This contributes to the advertising saturation that overloads consumers.
The paradox of saturation is that the more advertising floods the environment, the less each individual advertisement works, desensitising consumers. 74% of users cite intrusive ads as their main reason for using ad blockers, costing the advertising industry $54 billion globally in 2024. Procter & Gamble's 2017 decision to cut $200 million from digital ad spending had no measurable impact on sales. The causes identified included significant spend reaching bots and hyper-targeting creating frequency waste. Algorithmic glut and the relentless extraction of attention, evidenced by the online shopping overwhelm of 78% of Gen Z, is forcing an analysis of the nature of advertising itself.
The post-broadcast era: rebuilding shared meaning
The transition from twentieth-century mass broadcasting to hyper-personalised targeting has fractured the cultural infrastructure that sustained a cohesive monoculture. Historically, universally experienced media and advertising served as shared touchstones that fostered collective discourse; for instance, IKEA's 2017 Game of Thrones mock assembly manual generated a unifying buzz experienced simultaneously by millions. Today, this connective tissue has been eroded by on-demand consumption, algorithmic precision, and platforms incentivised to cater to niche audiences. As traditional cultural gatekeepers have been ousted by engagement-driven algorithms, collective narratives have been replaced with individualised content, dismantling the mechanisms that enabled mass culture.
This dissolution of monoculture was stark by the summer of 2025, which lacked the overarching narratives of 2024’s Brat or 2023’s Barbie that saw retail activations surrounding these cultural moments. While disconnected trends like Pucci dresses and capri pants surfaced without mutual reinforcement in 2025, the era of algorithmic micro-trends like "cottagecore" and "mob wife" collapsed as consumers reject manufactured movements in favour of offline authenticity. As economic pressure and information overload dissolve shared context into individualised fragments, consumers and especially lonely younger generations, are turning to brands that offering the connection created by shared culture.
Culture is the pillar of economic infrastructure that generates trust and social cohesion required to legitimise institutions and ensure commercial transactions. In times of disruption, shared cultural foundation fosters the collective adaptability necessary for economic resilience. Like a power grid provides physical infrastructure, a cultural infrastructure provides the shared meaning for any overarching economic system to function.
Brands and retailers increasingly fill this vacuum as cultural gatekeepers with consumer purchasing decisions no longer driven solely by product features and price; rather, they are tethered to a brand’s cultural legitimacy. Failing to navigate this landscape can result in the social backlash and declining sales following Target's DEI rollback or the criticism surrounding American Eagle's culturally disconnected campaigns. As the metrics of short-term attention become less reliable, department stores must build long-term cultural capital, centring the social cohesion of their consumer base.
The business of belonging
The shift from broadcast persuasion to cultural belonging draws on theoretical frameworks, some that retailers have already been using, operating in concert. “Collective effervescence”, sociologist Émile Durkheim’s concept of unity and shared emotional energy generated by communal gatherings, is being used as a commercial mechanism. When individuals participate in shared rites, they transcend their individuality and produce a sense of collective identity. Brand-engineered analogues of this experience — limited-release queuing events, pop-up activations, community-only drops — trigger emotionally charged group experiences reinforcing brand association.
Pierre Bourdieu's cultural capital theory explains the feeling of knowing a brand's quirks and references which confers status on those who possess subcultural capital. Those who "get it" are elevated; those who don't, aspire to. Social identity theory explains that people partly build their sense of self based on groups they belong to, and this feeling is stronger when they are visibly differentiated from outsiders.
For brands, this produces consumers who feel elevated because others do not understand the reference. Gentle Monster commodified this exclusivity as a private joke with their Bratz collaboration. Absurdist references, including the egg packaging, created meaning understandable only to someone fluent in Y2K nostalgia, Korean fashion culture, and internet irony. Especially for Gen Z, this credentialing creates a strong sense of in-group belonging addressing their need for community.
New Balance: a case study in cultural repositioning
Cultural strategy around brand-driven community-building addresses a genuine need rather than manufacturing belonging. 54% of Gen Z favours brands that make them feel part of a community and 84% of this demographic are more likely to purchase from brands perceived as cool.
New Balance's trajectory from ‘dad shoe’ to Gen Z darling is one of the most studied cultural repositioning cases of the 2020s. Starting from $3.3 billion in revenue in 2020, the brand reached $9.2 billion in 2025, while Nike's revenue fell from $51.4 billion to $46.4 billion over a comparable period.
New Balance did not distance itself from the dad shoe aesthetic to appeal to Gen Z, it reframed its 1990s running heritage when nostalgic styles returned to fashion post-COVID. Curating partnerships with Aimé Leon Dore and Kith, whose community-embedded credibility introduced New Balance to younger and more diverse audiences, it also signed younger sports stars like Coco Gauff and Cooper Flagg to reposition the brand. New Balance maintained its authenticity and used cultural intermediaries to reposition it as ‘cool’ for Gen Z.
Department stores as the infrastructure of cultural belonging
We believe department stores have an underutilised asset in today's fragmented market: institutional continuity. While micro-trends evaporate rapidly and pop culture remains volatile, retailers with decades of brand history can provide stability. Rather than participating in fleeting cultural moments, department stores possess the capacity to function as platforms for multiple communities. Despite being commercially driven, department stores can partly fill the vacuum left by the demise of cultural gatekeepers that allowed the formation of a mass culture. They can strategically define and build on what authenticity looks like for their consumer base, knowing that its impact may not be fully quantifiable especially in the short term. This potential was exemplified by Le Bon Marché’s rock and roll exposition, which fostered intergenerational cultural engagement and shared experiences unintentionally.
The transition from a transactional environment to a cultural hub is quantified in the value of a department store’s retail media network. Culturally resonant networks offer brands an avenue to connect with increasingly rare attentive audiences, elevating a secondary revenue stream for department stores into an asset built upon cultural capital. Behavioural nudges and individualised AI recommendation systems only succeed if consumers are engaged in noticing them. As trust in conventional advertising wanes and AI systems intercept direct searches, capturing consumer focus requires broader relevance than personalisation.
Retailers like Gentle Monster and New Balance built rituals that resonated with communities aligned with what these brands strive to represent, letting influence flow from a sense of belonging. Department stores can leverage their unique institutional continuity to provide a focal point for communities to organise naturally in an increasingly individualised environment.
Credits: IADS (Anchita Ranka)
IADS Exclusive: The $10 trillion management problem
IADS Exclusive: The $10 trillion management problem
Every year, Gallup surveys more than 150,000 employed adults across 160 countries and territories to produce the State of the Global Workplace report, the most comprehensive ongoing study of employee engagement, wellbeing, and job market perceptions. The survey uses Gallup's Q12 employee engagement instrument, a twelve-item assessment developed from decades of workplace research, which classifies employees into three groups: engaged (psychologically committed and contributing at full capacity), not engaged (present but psychologically absent), and actively disengaged (working, in Gallup's framing, against the aims of the organisation). The 2025 edition draws on data collected throughout 2024 and marks the seventeenth consecutive year of this global tracking. The 2026 edition, released this April, extends the dataset to 2025 and introduces a new analytical focus: the intersection of engagement with enterprise AI adoption. Both reports are referenced throughout, with data attributed to the year of publication rather than the year of collection.
Global employee engagement has fallen for two consecutive years. Enterprise AI investment has reached $40 billion with negligible returns on productivity. The Gallup 2025 and 2026 State of the Global Workplace reports trace back to the same cause: organisations have consistently underinvested in supporting and developing their managers.
For retail and department store organisations, these reports carry a direct operational message. 70% of team engagement is attributable to the manager, a finding from Gallup's own longitudinal research confirmed across both reports. In a department store, that figure describes whether floor teams build customer relationships or merely complete transactions, whether a new technology reaches the team or stalls at the briefing room door, whether new colleagues develop or leave quietly within 90 days.
A two-year structural decline
The 2025 edition documented the first year of the fall: in 2024, global engagement declined from its 2022 peak of 23% to 21%. The 2026 edition extends the record to 2025, where engagement fell again to 20%, a pattern without precedent in Gallup's data, and with no region of the world moving in the opposite direction.
Low engagement cost the global economy $438 billion in lost productivity in 2024, per the 2025 report. The 2026 report estimates that figure grew to approximately $10 trillion in 2025, or 9% of global GDP, measured as the potential output gap against a fully engaged global workforce.
The 2025 report framed its findings as equal in magnitude to the COVID-19 lockdown drop. The 2026 report updates that picture with a second consecutive decline, this time in an environment where AI investment has made the quality and support of management the central variable in whether organisations see productivity returns
The manager crisis
The 2025 report identified manager engagement as the primary driver of the global decline, documenting a fall in 2024, from 30% to 27%, against individual contributor engagement that held flat at 18%. The burden was unevenly distributed: managers under 35 dropped five points; female managers dropped seven. Individual contributor engagement declined in no comparable sub-cohort. The 2026 report extends this picture to 2025, and what it shows is acceleration rather than correction. Since 2022, manager engagement has fallen from 31% to 22%; the largest single-year drop occurred between 2024 and 2025, going from 27% to 22%. Managers, at 22%, now sit within reach of individual contributors at 19%. In 2022, that gap was close to double digits. It has narrowed to the point where engaged management behaviours are present in fewer than one in four managers globally.
The motivation that historically accompanied management responsibility, the connection to authority, the development opportunity, and the sense of organisational purpose have narrowed to near parity, and their consequences extend beyond managers themselves. Gallup's longitudinal research establishes that countries with less engaged managers are measurably more likely to have less engaged individual contributors; each disengaged manager carries a team's worth of individual contributor engagement down with them, and the trajectory across both reports confirms the mechanism is active and accelerating. The 2026 report's CEO letter is direct on the cause: the data has pointed to the answer for years, and the corporate world has largely chosen to ignore it. Manager disengagement at this scale is the direct output of organisational decisions about training, development, autonomy, and investment in the people who lead frontline teams.
The European baseline
For IADS members operating across European markets, these reports place this dynamic against a structurally unfavourable baseline. The 2025 report recorded European engagement at 13% in 2024, with 73% of the region's workforce in the not-engaged category and 30% intending to leave their employer within the next 12 months. Not engaged, in a customer-facing retail context, carries a specific operational meaning: these employees are present, follow procedure, and complete transactions, but withhold the discretionary effort that distinguishes a service relationship from a service transaction. The 2026 report records a further decline to 12% in 2025, the lowest regional figure globally. For a sector whose competitive differentiation depends on the quality of human interaction, every investment the sector is currently making in AI or customer experience depends on that workforce to deliver it.
The best practice gap
The 2026 report documents best-practice organisations, those that have embedded engagement as a long-term strategic priority and applied science-based management practices, at 79% manager engagement in 2025, nearly quadruple the global average, reproduced across every region and industry in the Gallup dataset. The 57-point gap between the global average and this benchmark is a measure of the decisions that have been made or deferred. In retail, the IADS White Paper Middle Managers: remnants from the past or tomorrow's unicorns? traced exactly which decisions those were: decades of centralisation that progressively stripped in-store managers of meaningful decision-making authority, restructuring programmes that repeatedly targeted the management layer as a cost reduction lever, and development budgets systematically applied elsewhere.
The management layer and AI returns
AI and the manager bottleneck
Between the two reports, the framing of AI changes: where the 2025 report discussed it as an approaching disruption, the 2026 report treats it as a current operational reality with measurable consequences. Despite approximately $40 billion in enterprise AI investment, 95% of organisations have seen no measurable impact on profits, according to MIT Project NANDA data cited in the 2026 report. A National Bureau of Economic Research survey of nearly 6,000 executives across the US, UK, Germany, and Australia, also cited in the 2026 report, finds that 89% report no impact of AI on their company's labour productivity in the past three years. In Gallup's own 2025 workforce data, only 12% of employees in AI-implementing organisations strongly agree that AI has transformed how work gets done.
Where the technology has delivered, Gallup's Q1 2026 data consistently identifies the manager as the determining factor: employees who strongly agree their manager actively supports their team's AI use are 98.7 times as likely to agree that AI has transformed how work gets done, and 97.4 times as likely to say AI gives them more opportunities to do their best work. Yet fewer than one-third of US employees in AI-implementing organisations strongly agree their manager actively supports the technology (21% in Germany, per Gallup’s 2026 dataset).
The IADS White Paper documents the mechanism. Our research noted that 49% of managerial work, including drafting job postings, integrating performance feedback, and routine reporting, can be automated by generative AI, freeing managers for the relationship-intensive leadership work that determines whether their teams adopt and use new tools effectively. The White Paper also details five specific roles middle managers play in this process: applying human judgment and empathy, managing risk, reimagining roles and work processes, leveraging real-time team performance insights, and freeing leadership capacity through task automation. At 22% global manager engagement, those functions are active in fewer than one in four managers globally. Organisations investing in AI without simultaneously investing in manager capability are funding a multiplier they have not yet built the conditions to use.
The $10 trillion productivity gap documented in the 2026 Gallup report and the AI investment failure are the same problem viewed from different vantage points. Both trace to a management layer that, at 22% engaged globally, is operating below the level at which either productivity or technology returns are reliably produced.
Training and the 79% benchmark
Both reports point to the same course of action, and the 2026 CEO letter frames the employer's choice plainly: equip managers with the resources to excel, offer development opportunities, and reconnect teams to a shared mission. The 2025 report establishes what committing to that produces: engagement gains of up to 22% among participants, up to 18% in their teams, and manager performance improvements of 20 to 28% within nine to eighteen months, with effects confirmed as durable. Training alone increases manager thriving from 28% to 34%; adding active organisational development encouragement raises it to 50%, according to that report. That the findings hold across pharmaceutical manufacturing, luxury hotels, and technology firms as consistently as they do in department stores matters specifically for retail leaders: the gap between 22% and 79% closes regardless of sector, and its determinant is investment decisions.
In retail, the IADS White Paper established why the deficit runs deeper than the global average suggests. The sector has operated for decades on an inversion that most organisations have never named: middle management is 80% leadership and only 20% management, while line management runs the opposite ratio. Yet promotion decisions across retail have historically rewarded management performance, producing a management layer selected for the 20% and left to discover the 80% on the job, without training, without frameworks, and frequently without support. A McKinsey survey of 700 middle managers across industries found that 42% were unsure, or actively disagreed, that their organisation had set them up to succeed as people managers. Those same managers reported spending more time on individual contributor work than on any other activity, a pattern the White Paper describes as particularly acute in retail, given the sector's promotion culture. The pandemic made the cost of this visible directly: when organisations needed managers to lead through unique conditions, many could not, because no one had developed that capacity in them.
The productivity stakes
McKinsey's 2024 research on frontline workforce retention in retail found that having an inspiring leader was cited as the seventh reason employees left their jobs in 2022; by 2023, it had risen to third. That two-year movement tracks the time during which manager engagement fell fastest across these Gallup reports. Most of the managers who struggle to inspire their teams were promoted into roles whose leadership demands were never part of the job description they were evaluated against, and were given no tools to develop them once there.
Bloom, Sadun, and Van Reenen’s Management as a Technology? research book, established that differences in management practices account for approximately 30% of the variation in total factor productivity, the standard measure of technology's impact on output. In the AI era, that relationship has grown more consequential: the same management practices that determine whether teams perform also determine whether technology investments deliver returns. Organisations operating with undertrained managers are forfeiting a quantifiable share of the productivity gains their technology investments are designed to produce.
Middle-out in practice
Carrefour France's restructuring under CEO Rami Baitieh, documented in the IADS White Paper as the defining retail case study of the 'middle-out' approach, inverted the traditional management hierarchy, placing customers at the top and the CEO at the bottom, and flattening the structure from five layers to three. Middle managers were placed at the centre of a real-time customer feedback loop: cashiers recorded comments daily, sorted by middle management teams via WhatsApp and reported directly to the CEO and HQ. Within six months, Carrefour France reached its highest Net Promoter Score on record. What produced those results was managers given purpose, equipped with the right tools, and trusted with meaningful commercial responsibility, with no new technology platform and no restructuring programme beyond the decision to place management at the centre of the operation.
Engagement as a human investment
Half of employees who are engaged at work are thriving in life overall, compared with only a third of those who are not, per Gallup's 2025 data. The engagement-wellbeing relationship runs in both directions, with managers at the hinge. The 2026 report adds a further dimension: when managers are engaged, they report all negative daily emotions at lower rates than individual contributors and are 14 points more likely to be thriving overall than the average leader. Improving manager engagement is simultaneously a business intervention and a human one; across both reports, these two goals converge rather than compete.
For retail, the argument does not stop at the data. These reports provide a documented path forward: the training and development investments that reverse manager disengagement are established and reproducible across every sector and region in the Gallup dataset. Manager development has long been treated as a cost incurred after the real investments are made; these reports establish that the investment determines whether the others deliver at all.
Two consecutive years of declining engagement across every region of the world is a structural pattern Gallup has not previously recorded. Structural patterns call for structural responses, not wait-and-see quarters or survey cycles filed as HR metrics. That response means investing in the leadership capacity the sector has historically failed to develop and restoring the autonomy and purpose that made the role meaningful. The organisations that realise AI's returns are those whose managers are equipped, supported, and genuinely committed to the teams they lead.
Credits: Maya Sankoh
IADS Exclusive: The next chapter of Omnichannel, from integration to reinvention
IADS Exclusive: The next chapter of Omnichannel, from integration to reinvention
For at least fifteen years, department stores have been navigating a structural decline. Footfall in city centres has fallen in every measured year since 2009. Spending on fashion, department stores’ core category, has contracted. And the pandemic accelerated a migration to online shopping, compressing a decade of change into two years.
The industry’s initial response was to bolt e-commerce onto the existing model. What started as a modest add-on — often an experiment operated on the same principles as the traditional stores — soon grew into a parallel business with fundamentally different cost structures. Against in-store conversion ratios of 25% or more, online hovered at 1–2%. Against sales per square metre, online invoked profit per transaction. Against expectations of bottom-line profit, online demanded years of loss-funded growth. Department store companies found themselves running two business models simultaneously: one built on real estate and people, the other requiring heavy investment in systems, fulfilment, and digital marketing. Integration proved expensive, profitability remained elusive — even for the pure players — and the admittedly complex model of the traditional department store proved inadequate for a truly omnichannel operation.
The IADS Academy 2021 cohort framed this situation in scientific terms: the existing paradigm can no longer solve the problems. The question is no longer whether to become omnichannel, but how to move beyond integration into something more deliberate, precise, and profitable. The answer lies in four interconnected shifts:
- From channel ubiquity to journey optimisation,
- From channel-based P&Ls to customer-centric financial architecture,
- From uniform store networks to precision-engineered physical assets,
- From inherited commercial models to purpose-built omnichannel ecosystems.
The article below reviews five years of IADS research, the current state of academic knowledge and the latest business articles on the topic, including research by Dr Christopher Knee, Honorary Advisor of the Association, and Professor Robert Rooderkerk, Academic Advisor of the Association.
From ubiquity to optimisation: steering journeys, not channels
The maturity gap
The term “omnichannel” is often misunderstood. As Robert Rooderkerk, Associate Professor at Erasmus University Rotterdam and academic advisor to the IADS, emphasises, omnichannel is not about being present in every possible place at once, but about being present where it matters, delivering value to both the customer and the business simultaneously.
In contrast to multichannel retail where channels coexist without coordination, omnichannel combines expansion into different channels with integration to facilitate seamless customer journeys. Yet as research argues, the usual tension between the market’s desire to offer a seamless experience and operations’ desire to maximise efficiency is particularly pronounced in omnichannel retail. Balancing the advantages of seamless integration with the cost of seamlessness is a standard operations management trade-off — but one that most department stores have yet to master.
To illustrate this, Rooderkerk has outlined a maturity model that most companies are currently moving through. The journey typically begins in a fragmented, multichannel phase, where online and offline channels are siloed. This setup fell short during the pandemic, when retailers rushed to stand up click-and-collect using manual workarounds and disconnected systems — the “experimentation” stage. As retailers progressed, they moved into a “ramping up” phase — scaling services like same-day click-and-collect, expanding geographic reach, and increasing speed. Most companies today remain stuck here, or in the next stage: “channel integration,” focused on order orchestration through centralised systems that choose the best fulfilment nodes based on stock availability, distance, and efficiency.
Yet many organisations are still held back by internal silos between digital and physical teams, leading to “tribal” conflicts over budgets, authority, and strategy. The move from a channel-led to a customer-led organisation requires what Rooderkerk terms customer-journey segmentation: identifying and investing in the most valuable or frequent journeys based on transaction volume or customer value. Instead of trying to optimise every possible journey, it’s all about focusing on those with the greatest return potential.
From supporting journeys to shaping them
The most advanced retailers do not just support these journeys — they shape them. Such maturity, which Rooderkerk calls “omnichannel optimisation,” is about steering customers toward the channels and touchpoints that improve profitability or customer equity, rather than fixating on perfectly seamless customer journeys that do not generate revenue.
The levers available to retailers are more varied than commonly assumed. Holland & Barrett, for instance, uses market-specific nudges to influence channel selection: in the UK, customers are prompted to choose click-and-collect with a prominent “free” message; in the Netherlands, the highlighted benefit is sustainability. Swatch demonstrates how simple, inventory-aware rules can avoid waste: when the stock of a particular watch is low, the reservation option disappears from the site, preventing high no-show rates that tie up valuable inventory. At Coolblue, a Dutch consumer electronics retailer, the physical placement of click-and-collect points meaningfully affects cross-sell potential. In LATAM, 50% of Falabella’s online orders are collected in-store, and these visits drive a 16% increase in gross sales from cross-sales at pick-up. However, before achieving such results, they went through a learning curve, observing that click-and-collect services located at the store entrance consumed premium square metres without NPS payback and created congestion, also preventing cross-selling opportunities.
Fulfilment as a strategic lever, not an operational afterthought
The taxonomy of omnichannel fulfilment models is richer than most department stores realise. These models span the forward supply chain (buy online, pickup in-store, reserve online, pickup in-store, buy in-store, ship to home), the reverse supply chain (buy online, return in-store, buy in-store, return online), and supporting models (ship-to-store, ship-from-store). Each carries distinct trade-offs between customer benefits and operational complexity, and each represents a potential lever for journey optimisation — not merely a service to be offered.
What makes these decisions strategic rather than merely operational is the downstream impact on customer behaviour. Failing to deliver an online order not only causes direct revenue loss but also reduces future customer spending. A study shows that when missing products were reimbursed, customers delayed their next order by almost 24 hours and spent approximately one euro less. When products were substituted — a strategy most retailers assume softens the blow — the delay nearly doubled. These effects compound over the year: the total revenue loss from fulfilment failures exceeded 12% of annual revenue, nearly double the 7% direct cost of reimbursing for missing items. The strategic implication is clear: fulfilment failures may be operational in nature, but their consequences are deeply strategic.
The incentive gap
Among the levers of optimisation, incentives are key. Rooderkerk identifies a worrying 7% to 10% order-cancellation rate for ship-from-store orders, driven by insufficient inventory data or a lack of store compliance. Without financial incentives, stores may deprioritise e-commerce orders or even cancel them to conserve inventory for walk-in customers. Companies like Adidas have responded with reward-based routing, sending orders to stores with strong compliance and fulfilment performance. Walmart and Target rely on real-time inventory accuracy as a key routing factor — Target, after a $3 billion investment, now fulfils 95% of online orders through nearly 2,000 stores. Optimisation requires aligning technology with human incentives.
For department stores specifically, this represents both a challenge and an opportunity. The department store’s distinctive asset — its large, centrally located, multi-category physical space — becomes a powerful fulfilment and experience node only if its organisation can operate as a unified entity rather than a collection of competing channels.
Measuring differently: the omnichannel P&L and the omni-cluster
Why existing instruments fail
In 2021, the IADS Academy was tasked with addressing this precise problem: what would a truly omnichannel P&L look like, and which KPIs would support it? Their diagnosis was blunt: as long as the business consisted of stores, and even stores with a small separate online channel, the traditional model held up. Since cross-channel and multi-channel started impacting the core business, attractiveness and profitability have plummeted.
A key reason for this failure is the persistence of separate P&Ls for stores and for online. Various efforts have been made in the past to credit online sales to stores, but these have been artificial. The fundamental problem is that employees are assessed on KPIs which discourage an omnichannel approach, while data is unavailable to track customers, inventory, and fulfilment in sufficiently granular form to allow appropriate attribution.
Traditional KPIs are backwards-looking and channel-specific. Traffic, conversion rate, sales per square metre — these tell what happened in a single channel yesterday. They cannot evaluate the complex drivers of customer decisions that span multiple touchpoints over time. The shift from a product-based model to a customer-based model means that customer KPIs must become financial KPIs.
The omni-cluster: a customer-centric financial architecture
The IADS Academy’s central proposal was the concept of the “omni-cluster”: clusters of stores and online based on customers, whatever their channel. An omni-cluster is, at its core, a group of customers. All revenues, returns, and costs associated with a customer belong to that omni-cluster. The only rule is that any customer can belong to only one omni-cluster, even if they occasionally shop, return, or collect in several physical stores.
Dr Christopher Knee from IADS subsequently developed this concept further. In its simplest configuration, an omni-cluster consists of one or more stores and the online customers who reside around those stores — a model favoured by Magasin du Nord, for example. Where customer behaviour is more complex — say, when online customers prefer a distant flagship store — a mixed omni-cluster might include a store, its geographically close online customers, and online customers who are geographically closer to another store. This may occur when stores are clustered by size, as at Manor. For businesses with a large tourist clientèle and franchised operations, still more complex configurations may apply — as might be the case at Galeries Lafayette.
The criteria for omni-cluster membership are flexible and vary according to the company’s history, organisation, and market. The aim is to group revenues and costs into a number of omnichannel P&Ls which cover total operations of a cluster, which can serve to manage operations through related KPIs, and which can be consolidated into a total business P&L. Three key consolidated measures were proposed: Customer Lifetime Value (CLV), which is by definition forward-looking and allows the identification of profitable customers; sales per employee across all employees in a given cluster irrespective of channel; and cost of returns as a proportion of total sales, covering costs incurred by all channels.
An irreversible strategic choice
Once established, an omni-cluster ecosystem can no longer be dismantled and split up into its original component parts. It competes as a whole, not as a multi-channel entity. The data architecture is not a separate workstream — it is the foundation on which the entire omni-cluster edifice rests, which makes it quasi-impossible to spin off the e-commerce part of the business, as HBC has done with Saks Fifth Avenue and Saks.com, with the results we now know. The integrated omnichannel route is a different bet: a smaller omnichannel department store following it will be capitalising on its unique status as what Bain & Company has called a “regional gem.” The commitment is no less risky than the spin-off route — but it is a fundamentally different vision of what a department store is.
Note: The question that remains largely unanswered however is what a transition phase towards omni-cluster P&L would look like. Who should guide the transition?
The store as a precision instrument: format, network, and category logic
Deconstructing the halo effect
The much-discussed “halo effect” — the idea that opening a store lifts nearby online sales — is often exaggerated: researchers found that store openings reduced online sales. Online net revenue declined by approximately 8–10% across both large- and small-format openings. However, the large, experience-centric stores more than compensated for this cannibalisation, generating a net revenue uplift of 27.5% in the longer term. The small, convenience-centric store, by contrast, cannibalised online sales without producing compensating gains.
These results held even when the analysis was restricted to categories, suggesting that it is the store experience — not assortment breadth — that accounts for most of the performance differences. Large experience-centric stores create value through how they sell, not just what they sell. Their immersive environments and expert service effectively activate both new and existing customers — benefits not replicable in the smaller format.
The physical department store, with its large footprint, broad breadth of categories, and tradition of service, is structurally well-suited to the experience-centric model. But this advantage is not automatic — it requires deliberate investment in the quality of in-store experiences, expert staffing, and sensory engagement. A department store that merely occupies a large space without delivering distinctive in-store utility risks the same outcome as the small convenience format: cannibalisation without compensation.
Not all categories are created equal
Perhaps the most consequential finding for department store executives lies at the category level. Research reveals substantial variation in revenue uplift across 22 product categories following a store opening. Some categories more than doubled their sales, while over 40% showed no significant uplift.
The answer lies in what the researchers call “perceived in-store utility“ — the value customers expect from experiencing a product in a physical store rather than online. This utility was measured across three stages of the customer journey: information search (sensory experience and expert advice), fulfilment (instant gratification), and returns (ease of processing). The results are striking: a one-standard-deviation increase in perceived information-search utility is associated with a 23.6-percentage-point increase in net revenue uplift for destination categories. A similar increase in fulfilment utility yields a 14.6-percentage-point rise. Return utility, by contrast, showed no significant effect — suggesting that experience-centric stores create value primarily by providing information and fulfilment benefits, not by serving as efficient return sites.
Crucially, these effects apply only to destination categories — high-involvement products that independently drive store visits. Accessory categories showed no utility-driven uplift, but several experienced substantial revenue gains, likely driven by cross-buying and bundling with their destination anchors.
Asymmetric assortment integration: a framework for cross-channel allocation
The question of which categories to put where is not merely intuitive — it requires “asymmetric integration“18. In the most common configuration, the online assortment contains the offline assortment plus more — reflecting the long-tail effect and the lower marginal cost of carrying additional products online. But other configurations may be strategically preferable: certain products may belong exclusively in the physical store, while others may be online-only (when physical space constraints or low in-store utility make floor presence uneconomic).
For department stores, this framework is particularly powerful because of the breadth and heterogeneity of their assortment. Fashion, beauty, homeware, and technology do not all create the same in-store value, and within these broad domains, subcategories will vary enormously. A haute couture dress and a basic white t-shirt, a perfume counter and a shampoo display, a curated furniture showroom and a commodity storage solution — each carries a different utility profile across information, fulfilment, and returns. Retailers can survey customers on perceived in-store utilities and use the results to guide assortment planning, space allocation, staffing decisions, and the design of experiential elements. Categories with high information utility warrant deeper assortments, immersive sensory experiences, and more expert staffing. Categories that score primarily on fulfilment may not need floor presence at all — they can be stocked in inventory and surfaced through efficient click-and-collect or virtual aisles. Accessories should be strategically positioned near their destination anchors or bundled into cohesive solutions.
The role of each channel in the customer journey must be explicitly acknowledged when planning assortments. A product with low in-store conversion but high showrooming value may be essential to the store even if it scores poorly on sales per square metre. Conversely, a product with many online views but low conversion — and where webrooming can be ruled out — might benefit from more prominent physical presence, where salespeople can address the uncertainty that holds customers back. This kind of cross-channel intelligence requires integrating data across all channels and touchpoints and rethinking metrics designed for a single-channel world.
Rethinking the network: densification and role-based formats
Beyond format and assortment, Rooderkerk proposes a wider framework for store network strategy that includes expansion, downsizing, relocation, and densification. Densification — adding smaller stores closer to high-density customer segments — is becoming a strategic frontier. Smaller formats can serve two distinct models. The first focuses on specific touchpoints in the journey, offering services such as advice, pickup, or returns without maintaining full inventory (e.g., Nordstrom Local, IKEA’s “Plan & Order“ stores). The second model supports the full journey within a smaller footprint (Galeries Lafayette’s store in Nimes), which, although much smaller than the flagship, offers a curated yet comprehensive assortment tailored to local customers.
For department stores, this suggests that the traditional model of a single large flagship, supplemented by near-replicas, may give way to a differentiated network in which each node plays a distinct role in the ecosystem. The flagship remains the experience-centric anchor; smaller formats serve as gateways to the broader offer, equipped with endless-aisle capabilities to access online inventory. But each store should be judged not only on its own sales per square metre, but also on how it supports customer experience, delivery efficiency, and brand visibility across all channels. In this respect, the Bloomie’s experiment in the U.S. conducted by Bloomingdale’s is highly interesting.
Rethinking the commercial architecture: who owns what in an omnichannel ecosystem?
The inherited model under pressure
The shifts described above — journey optimisation, customer-centric P&L, precision-engineered stores — all presuppose a commercial architecture capable of supporting them. Yet the dominant commercial models of the department store were designed for a different era.
Department stores have traditionally operated across a spectrum of commercial relationships. Each model carries different implications for the levers of omnichannel optimisation. In a conventional model, the retailer controls the stock and can therefore orchestrate fulfilment — routing orders from store or warehouse, offering ship-from-store, managing returns centrally. In a concession model, the brand controls its own supply chain all the way into the store, which creates friction when the retailer wants to use that inventory for e-commerce fulfilment or cross-channel services. The question of “who owns the stock” becomes operationally critical when a store is expected to function simultaneously as a selling floor, a fulfilment node, and a data collection point.
The digital extension: marketplace and e-concession
These tensions are amplified in the digital domain. The online equivalent of concession is the marketplace or e-concession model, where brands use the retailer’s platform to sell directly, with fulfilment handled either by the brand (drop-shipping) or by the retailer. The marketplace model allows department stores to dramatically expand their online assortment without taking on inventory risk, but it also dilutes control over the customer experience and, critically, over customer data.
For an omnichannel department store pursuing the omni-cluster model, this raises questions. If a customer’s journey involves a concession-operated in-store experience, a marketplace-fulfilled online purchase, and a return handled by the retailer’s own staff, to which omni-cluster do the revenues and costs belong? Who holds the unified customer data? How are the KPIs — CLV, sales per employee, cost of returns — calculated when the employees, inventory, and fulfilment processes belong to different entities?
Unbundling and rebundling
The IADS has suggested that a degree of “unbundling” will be necessary to evaluate the costs attributable to an omni-cluster. When that exercise is pursued, it becomes possible to find potentially more appropriate, more efficient, or more effective solutions before rebundling these into an omni-cluster ecosystem. This is the essence of the challenge: the department store of the future must decompose its inherited commercial functions — buying, stocking, selling, fulfilling, servicing, and relating to the customer — and reassemble them into configurations that serve omnichannel logic.
This may mean, for example, that conventional buying is retained for destination categories where the retailer’s curation and expertise add value and where control over inventory enables fulfilment optimisation; that marketplace is used for long-tail categories where breadth matters more than in-store experience; and that concession is reserved for brands whose in-store presence and expertise genuinely enhance the customer experience in ways the retailer cannot replicate. Each model would need to be evaluated not only on its margin contribution but on its compatibility with the broader omnichannel ecosystem — its impact on data availability, fulfilment flexibility, and customer journey coherence.
No single commercial model will suit every category, brand, or market. But the current patchwork — where the choice between conventional, consignment, and concession is often the product of historical negotiation rather than strategic design — is poorly suited to the precision required by omnichannel optimisation. Department stores that undertake this unbundling exercise deliberately will have a structural advantage over those that allow their commercial architecture to evolve by inertia.
Conclusion: from omnichannel to ecosystem — and beyond
The trajectory outlined, from channel integration to journey optimisation, from channel-based P&Ls to customer-centric omni-clusters, from uniform store networks to precision-engineered physical assets, from inherited commercial models to purpose-built architectures, points toward a destination that transcends the notion of “omnichannel” altogether. What emerges is the concept of an ecosystem: a retail business in which every component — the store, the digital platform, the data infrastructure, the commercial model, the category strategy — is orchestrated in function of its contribution to customer value and profitability.
The IADS Academy 2021 anticipated this evolution, mapping the industry’s trajectory from the single store, through e-commerce, cross-channel, and omnichannel, toward what it called the “ecosystem” stage. Five years on, the contours of that ecosystem are becoming clearer.
But there is an additional dimension that most omnichannel strategies have yet to address: the upstream impact on product development itself. Research argues that companies thriving in an omnichannel world are rethinking how they identify opportunities, design, test, and launch new products. The omnichannel environment creates both unprecedented access to consumer data — through clickstream analysis, DTC channels, online communities, and co-creation platforms — and new operational constraints that must be embedded early in the NPD process. Procter & Gamble’s Tide Eco-Box, designed from the outset for e-commerce fulfilment (less packaging, less plastic, optimised for delivery trucks and letter boxes), exemplifies a product conceived for the operational realities of a specific channel. Alibaba’s Tmall Innovation Centre partnered with Mars to develop Spicy Snickers based on platform data revealing that chocolate buyers also liked spicy snacks — compressing a 36-month development window into less than a year.
As Rooderkerk has noted, leveraging retailer data and sharing it with manufacturers could lead to much better innovations. This represents a shift from the traditional push model of innovation — where manufacturers develop products and retailers stock them — toward what might be called collaborative product innovation, where the retailer’s data on customer behaviour, channel preferences, and operational constraints feeds directly into the development process. For department stores, which sit at the intersection of thousands of brands and millions of customer interactions, this is a largely untapped strategic asset. The department store of the future may not only sell and fulfil — it may co-create the products it sells, using its omnichannel data as the currency of partnership with brands and manufacturers.
This is what the ecosystem stage ultimately means. It is one where optimising customer journey and reinventing the store network are not parallel projects but interdependent levers of transformation. Where the measurement system reflects the reality of how customers actually behave rather than how channels are organisationally structured. Where each store is judged on its contribution to the whole, each commercial relationship is assessed on its compatibility with an integrated logic, and each product is developed with the full omnichannel journey in mind.
Credits: IADS (Selvane Mohandas)
IADS Exclusive – One door: how single-location department stores defy retail expansion logic
IADS Exclusive – One door: how single-location department stores defy retail expansion logic
In an industry defined by scale, the single-location department store is an anomaly, as conventional retail logic relentlessly pushes toward expansion: more doors, more markets, more revenue. Yet some of the world's most iconic department stores have only a single store and have not only survived but grown precisely because of it. This article explores Liberty and Harrods in London, Bergdorf Goodman on NYC’s Fifth Avenue and Le Bon Marché on Paris' left bank, but TSUM Kyiv would also have been interesting examples.
These department stores are not waiting to grow. They are institutions. And their singularity is not a limitation they have worked around, but rather the foundation of their competitive advantage. Single-location department store assets cannot be standardised across a chain or reproduced in a new market. They are deeply specific, historically grounded and impossible to copy at scale. But singularity carries its own risks. The same uniqueness that creates a destination can become a trap
Architecture: the destination factor
Liberty’s unmatched architectural identity
Some of the most enduring single department stores share a defining trait: their architecture is the brand. Liberty is perhaps the clearest example. Its iconic Tudor Revival façade, designed in 1924, was constructed from the timbers of two ancient Royal Navy three-decker battle ships. More than 680 cubic metres of ship timbers were used, including their decks, which now form the shop's hardwood floors. The result is a store that feels both ancient and theatrical, unlike anything else in the retail world. Designed to feel like a home rather than a commercial space, its 7,400 sqm are arranged around three atriums, each surrounded by smaller rooms originally complete with fireplaces and furnishings. The building is now a heritage-listed London icon, carefully preserved and among the city's most recognisable architectural icons.
In 2025, Liberty reported 6% year-on-year sales growth and 61% increase over pre-COVID levels, validating a retail strategy that prioritises unique curation and local market focus over global standardisation.
Harrods: when scale becomes a landmark
Liberty and Harrods both function as cultural landmarks and tourist destinations, though at different scales. Where Liberty is intimate, Harrods is palatial. At approximately 100,000 sqm, the size of the Knightsbridge building has always been a spectacle in its own right. For example, its façade has been illuminated by 12,000 electric light bulbs since 1959, attracting visitors early on for that specific reason. Today, around 100,000 people reportedly visit the store every day, rising to 300,000 in the run-up to Christmas, and approximately 15 million a year in total (2023 estimates). The store continues to increase dwell time and sales through spatial reinvention, such as its most ambitious renovation and architectural project to date, creating a two-story watches and jewellery department featuring innovative vertical boutiques and Europe's first curved escalators. This type of elevated design is not just qualitative, but measurable. Reports show that the best retail destinations across architecture, interiors, and experience achieve $15,000-$17,000 per sqm, around 70% above average. By contrast, the good stores generate less than half that performance.
Becoming inseparable from the city's identity, both Liberty and Harrods create a "pilgrimage" effect, driving people to visit them beyond their retail essence. They are cultural and architectural monuments, functioning as much as national institutions as they do as shops. The architecture of Liberty and Harrods carries the brand, the history and the commercial proposition simultaneously. It is an asset that cannot be franchised or reproduced.
Art experiences: when retail becomes a museum
Le Bon Marché: art programming as a commercial engine
One of the competitive advantages a single-location department store enjoys is the ability to take creative risks that chains could not standardise. From its earliest days, the department store has been a spectacle. Le Bon Marché has taken that idea further than any other global competitor, building an ambitious cultural programme that it would be impossible to replicate elsewhere. That, precisely, is the point.
Le Bon Marché's engagement with art is rooted in its own history. Its founder, Aristide Boucicault, organised painting exhibitions in the store in the nineteenth century. Today, the store holds a permanent collection of over 80 works of contemporary art and design and operates as a museum would: visitors can take guided visits of the store as a cultural destination in its own right for €20 during the day or €45 after closing hours.
More importantly, since 2016, the store has commissioned annual museum-grade installations by internationally acclaimed artists, transforming it into an immersive art gallery with monumental works suspended from the ceiling and pop-up spaces turned into art venues. Each January, when the store's calendar is dominated by sales and the traditional Le Blanc linen promotions, these exhibitions draw a significant additional, distinct audience. Since the praised Ai Weiwei's inaugural exhibition in 2016, they have become genuine cultural events in Paris. Chiharu Shiota, Leandro Erlich, Joana Vasconcelos, Subodh Gupta and Daniel Buren are among the artists featured. Over the years, this art programming has established Le Bon Marché as a legitimate cultural venue where art, commerce and daily life meet.
Finally, in 2022, Le Bon Marché went further still, launching its first after-hours theatre production and reinventing the store as a live performance space. The inaugural show was an immersive adaptation of Émile Zola's Au Bonheur des Dames, itself inspired by the birth of the department store. Audiences moved through the floors while actors performed around them. A second production, co-created with Cirque Le Roux, converted the ground floor into a circus venue, complete with a stage including a gigantic wall construction. Combining acrobatics and drama, the most recent production, Babel by Compagnie Käfig, required the building of an eight-metre-tall structure. All shows ran every Thursday, Friday and Saturday evening from September 2025 through December 2026, with tickets priced between €50 and €75.
This programming is not cultural philanthropy but a commercial engine. Evening performances attract during hours when the store would otherwise be closed, introduce audiences who may not yet be shoppers, and generate specific editorial coverage that no media budget could replicate. More fundamentally, none of it could be reproduced across a portfolio of stores. The scale of investment makes sense only because there is one Le Bon Marché. The singularity of the location is what makes the ambition viable.
Bergdorf Goodman windows: a New York institution
Few things in retail have achieved the cultural permanence of Bergdorf Goodman's windows. In the 1930s, they carried a surrealist sensibility. By the 1950s, they reflected the postwar appetite for glamour. The 1970s brought street theatre. Each decade left a distinct mark, and today the windows synthesise all of these periods, blending high and low culture, art, science and nature into a deliberately maximalist vision. Overloaded with detail, they are designed to allow multiple readings: from across the street, from a passing car, and up close, where hidden details and in-jokes reward the attentive viewer. Over the decades, the store has collaborated with independent artists and major cultural institutions, including the New-York Historical Society. The subject of several books, Bergdorf Goodman windows are a form of public art that has shaped New York's visual identity.
The commercial logic is equally clear. The windows function as advertising, a cultural statement, and a brand anchor simultaneously. They generate earned media, drive foot traffic and reaffirm the store’s position as the definitive luxury fashion address in New York. As with Le Bon Marché's art programme, the commitment these windows require is justified and made possible by the fact that there is only one Bergdorf Goodman.
The art of being a merchant: the luxury magnitude
Harrods’ total luxury ecosystem
What sets Harrods apart is the sheer concentration and depth of its luxury-brand offering. Home to over 3,000 brands, the store is more than a question of square footage; it is defined by the model through which those brands are presented. Harrods has developed a Superbrands format, dedicating entire rooms and floor sections to the world's foremost luxury houses, including Chanel, Dior, Hermès, Prada, Loro Piana, Harry Winston and more, giving each the spatial presence and editorial control of a standalone boutique, within a single building. For many of these houses, their Harrods space is the most significant concession they operate outside their own flagships. Exclusive products, designed or sourced specifically for Harrods and unavailable anywhere else, reinforce the store's position as a destination that cannot be replicated elsewhere. The result is a store that functions simultaneously as a multi-brand retailer and as a curated collection of the world's most prestigious brand environments, an experience that no other department store, anywhere, replicates in full.
The services ecosystem is equally without parallel. Harrods operates more than 26 eat-in options. Research by Harrods in 2023 shows that when customers engage with restaurants and bars, they spend twice as long in the building and twice as much money. Compared with the pre-pandemic period, this represents a turnover up +49% vs. 2019. Also, a tiered personal shopping programme ranges from an accessible in-store consultation to an invitation-only private shopping suite at The Penthouse, reserved exclusively for the highest-tier Harrods Rewards clients.
Harrods made a bold move in 2017 by opening a closed-door, appointment-only Wellness Clinic, a significant shift in how luxury department stores were beginning to think about beauty and exclusive services for their wealthy customer base. Spanning almost 1,000 sqm, the space was never intended to be a traditional spa or beauty salon. Instead, the Wellness Clinic was conceived as a high-end, results-driven clinic offering a curated selection of treatments. The space was designed to offer an unusually wide range of services for a department store. Harrods assembled a multidisciplinary team covering everything from injectables and body contouring to cryotherapy, DNA-based personalised skincare, IV vitamin infusions, dental services, osteopathy, podiatry and physiotherapy. A dedicated partnership with a wellness expert brought daily personal training and nutritional coaching on-site. Taken together, the concentration of luxury through brands, services and dining creates an unmatched gravitational pull.
Yet Harrods is structurally vulnerable due to over-reliance on tourism. Sensitivity to international travel cycles, currency swings, visa regimes, geopolitical shocks, and economic decisions, such as the discontinuation of tax-free shopping in the UK, can stimulate or depress luxury shopping.
Bergdorf Goodman’s unparalleled curation
Where Harrods commands through scale, Bergdorf Goodman commands through editorial precision. That distinction is deliberate and structural, based on scarcity, craftsmanship and belonging. Across eight floors of the women's store, in a Beaux Arts building erected in 1928 on the former site of the Cornelius Vanderbilt II mansion, the store houses highly directional selections with an intentionality that goes beyond buying. The house's online magazine, the BG Edit, extends this curatorial voice into editorial territory, positioning the store as a taste authority.
The store's curatorial identity is also embodied in its leadership. Linda Fargo, SVP Fashion and Store Presentation Director since 2006, occupies a role with no true equivalent at any other department store: her personal edit has its own dedicated space within the building, her aesthetic sets the tone for the store's visual identity, and her presence at fashion weeks carries the authority of an institution. That level of human curatorial investment, rooted in decades of relationship-building with designers, is itself a form of product offer that cannot be replicated.
Private labels becoming global brands
Liberty prints: woven into the business model
The story of Liberty's fabric business is, in many ways, the story of Liberty itself. When Arthur Lasenby Liberty opened on Regent Street in 1875, textiles were at the heart of his vision. He had made his reputation importing fine silks, Japanese kimono fabrics and printed Indian cottons, and it was not long before he began commissioning original designs. By the 1880s, Liberty was working with British artists and craftspeople aligned with the Arts and Crafts movement. Collaborations with figures such as William Morris helped establish the brand as a pioneer of Art Nouveau. In 1884, Liberty acquired the Merton Abbey Print Works, taking direct control of its fabric production for the first time. By the 1890s, Liberty fabrics had become synonymous with the finest avant-garde textile design, its floral, paisley and abstract patterns recognised across Europe. Central to the entire print business is a single extraordinary material: Tana Lawn cotton, which remains the most iconic and commercially important fabric Liberty produces. In the early 1920s, Liberty sourced ultra-fine long-staple cotton fibres. The result was a revolutionary textile, fine, breathable and durable, with a silk-like lustre and fluidity that no other cotton has matched. It became the store's best-selling textile almost immediately.
Today, Liberty holds an archive of 45,000 original designs. Its fabrics are sold in-store, online and through a wholesale network spanning 32 countries. In 2019, the fabrics business grew at 15% year over year, making it the largest contributor to the Liberty Group, with combined in-store and online growth of 37% from 2018 to 2019. To serve its expanding international wholesale market, Liberty launched a dedicated B2B platform, www.libertyfabric.com, in 2019, making its archive accessible to trade buyers globally for the first time. The fabric business also enables Liberty to collaborate with brands as varied as Uniqlo, Loewe, Nike, Supreme and the Bridgerton series, reaching additional customers. The company has also used its fabric platform to support emerging designers through the Liberty Discovers programme, developed with the London College of Fashion, offering access to the archive, mentorship from the buying team, and exposure through the store's communications. Richard Quinn's early career is one example of what the programme has produced.
What the Liberty print business represents is rare and structurally significant: a proprietary creative asset that generates value simultaneously across retail, wholesale, licensing and collaboration. As the brand's design director noted in 2019, "Through the Liberty London store we are curators; through our fabrics business we are makers." That combination is unique among global department stores. The fabric business also solves a structural challenge specific to the single-location model: how to generate revenue from customers who may never visit the store. Liberty in-house brand now accounts for 30% of the company's turnover.
The label is the product: Harrods' food and gifting business
Charles Henry Harrod opened his first venture in 1834, a grocery business in London's East End. By 1849, he had relocated to Knightsbridge, occupying a single room at 105 Brompton Road, and was already dispatching hampers of preserves and teas. Food has therefore been at the very core of the Harrods brand since before the current store existed.
The iconic Food Halls opened in their current form in 1905, featuring elaborate Arts and Crafts tiled interiors. The store's motto, Omnia Omnibus Ubique, "all things for all people, everywhere," captures the ambition. The Harrods own-brand food range, bearing the store's name on tea, coffee, preserves, biscuits, chocolate, gift sets and hampers, is now one of the most recognisable luxury private labels in global retail. Sold in-store, online and through a dedicated Corporate Service division for business gifting, it operates at significant scale. Personalised hampers can be built by individual customers and corporate clients alike, with bespoke packaging, custom branding, thematic curation and coordinated global delivery available for large-volume orders.
The Harrods name is not a generic private label but functions as a signal of luxury and provenance. Own-brand food products are sold as souvenirs and gifts, not commodity alternatives. Harrods controls the full value chain: product development, in-house manufacturing of chocolates and baked goods, curation, packaging, corporate sales and international fulfilment. Each gifting season, from Christmas to Eid to Easter to corporate year-end, is anchored by new collections designed to sustain that cycle of demand.
Like Liberty's fabric business, the Harrods food and gifting operation extends the store's commercial reach far beyond its Knightsbridge address. A hamper dispatched to Calcutta or Boston in 1849 carried exactly the same logic as one delivered to Tokyo or Dubai today. The store has one location. The brand has no geographic limits.
The limits of singularity: Samaritaine, a store looking for its customers
When uniqueness is not enough
La Samaritaine was founded in 1870 by Etienne Cognacq and Marie-Louise Jaÿ, two people from modest backgrounds who built one of Paris's most celebrated retail institutions. Growing steadily over six decades, they assembled a complex of four buildings completed in 1932. LVMH, which had acquired Le Bon Marché in 1984, bought La Samaritaine in 2000, envisioning the two stores as complementary flagships with distinct identities on each bank of the Seine.
The store closed in 2005 due to safety concerns. What followed was sixteen years of closure, legal disputes, contested designs and repeatedly deferred reopening dates. When it finally reopened as Samaritaine in June 2021, the total investment was estimated at €750 million.
The renovation, led by Pritzker Prize-winning studio SANAA in collaboration with heritage specialists, was a remarkable achievement. The Art Nouveau features, cast-iron signs, ceramic decorations, enamel-tile facades and decorative pillars were meticulously restored. The Art Deco façade overlooking the Seine, the glass-roofed atrium, and the famous peacock fresco on the upper floor were restored to their original condition. The new undulating glass curtain wall on the Rue de Rivoli, a shimmering wave echoing the rhythm of the Haussmann-era streetscape, was widely praised as a feat of contemporary architecture.
But the renovation, however admired, was not the commercial strategy. The store was conceived and operated as a luxury destination, managed by DFS, LVMH's Hong Kong-based duty-free subsidiary, with an explicit ambition: to capture affluent international tourists, and above all, Chinese luxury shoppers. The assortment, the operating model, and the entire commercial logic were calibrated for that one customer, leaving. Parisian locals were not the target, and the store's offer made that evident. Samaritaine reopened at the height of the post-COVID travel shutdown, with no international tourism. And when travel resumed, the anticipated wave of Chinese luxury spending never materialised. The store was left without its intended customer, and, having never courted a local one, without a viable alternative.
In search of the right commercial proposition
The virtues of the single-location model are real, but they are not unconditional. They depend entirely on the coherence of the underlying commercial proposition. When architecture becomes the destination without a sustainable customer base to support it, uniqueness alone cannot save it. Curious visitors come for the building, mostly for the peacock fresco, but they do not come to shop. Samaritaine has become, in effect, a cultural monument with a retail floor inside it. The lesson is that no amount of architectural magnificence can compensate for a missed customer strategy.
In 2025, LVMH extracted Samaritaine from DFS Group to reposition the department store for individual shoppers rather than Chinese tour groups, creating a new governance structure with Le Bon Marché and Samaritaine under single leadership. This reorganisation signalled a strategic shift, moving from travel retail toward a more sustainable, locally relevant business model. Shifting away from its previous focus on Chinese tour groups, the move aims to leverage the complementary strengths of both properties: Samaritaine's exceptional location and Le Bon Marché's established Parisian identity, combining creativity with professional execution.
The stores examined in this article have little in common at first glance. Yet they share the same strategic truth: one location mastered is more valuable than multiple locations, and what cannot be reproduced cannot easily be threatened. The single-location department store is not a relic of a pre-expansion era. It is a model that, when built on genuine and irreplicable assets, whether a heritage building, a proprietary product or a deeply local identity, is among the most defensible positions in retail. The cautionary tale of Samaritaine does not undermine this conclusion. It sharpens it. Singularity is not inherently an advantage, but it becomes one when it is backed by a coherent commercial proposition and a customer base broad enough to sustain it. In an industry that has spent decades chasing scale, these stores are a reminder that some things gain value precisely because they cannot be everywhere.
Credits: IADS (Christine Montard)
IADS Exclusive: Department Stores Spring windows 2026
IADS Exclusive: Department Stores Spring windows 2026
Spring 2026 is here, and department stores around the world are making their mark. IADS has brought together the season's standout window displays, in-store installations, and visual moments from members and beyond.
DEPARTMENT STORES WINDOWS, IN-STORE INSTALLATIONS, VISUALS & SOCIAL MEDIA SPOTS
CLICK HERE TO SEE THE 2026 SPRING WINDOWS REPORT
Credits: IADS Team
IADS Exclusive – DEI at a crossroads: US retail trajectory since Trump’s Executive Order
IADS Exclusive – DEI at a crossroads: US retail trajectory since Trump’s Executive Order
This is the second article in IADS's series expanding on themes from the January 2026 White Paper DEI at a crossroads in retail. After reviewing the Abercrombie & Fitch business case the focus shifts to the broader US retail landscape.
In 2020, following George Floyd's murder, U.S. retailers launched ambitious DEI programmes and made sweeping public commitments. By early 2026, many had eliminated or scaled back their initiatives, citing changing political realities and legal risks. Target ended its Racial Equity Action and Change initiative. Walmart wound down its racial equity centre. Nike became the first major retailer targeted by federal investigators over its diversity goals.
For U.S. retailers, the stakes extend beyond reputation to legal and financial exposure. Federal contractors face potential liability for maintaining programmes the Trump administration deems "illegal DEI." Yet enforcement remains inconsistent, with conflicting court rulings creating uncertainty about what's permissible. In late April 2026, that uncertainty sharpened. The U.S. Supreme Court's ruling in Louisiana v. Callais effectively ended sixty years of protections against racial discrimination in elections. The Trump administration's executive order barring DEI programmes among federal contractors remained in force despite legal challenges, carrying significant financial penalties for non-compliance.
The political pendulum: From 2020 to "We ended DEI”
On September 22nd, 2020, President Trump issued Executive Order 13950, curtailing federal diversity training. At the same time, America was reeling from nationwide protests over the murder of George Floyd on May 25th, 2020, prompting a wave of corporate DEI commitments. On January 20th, 2021, President Biden rescinded Trump's ban and issued Executive Order 13985 to advance racial equity. The reprieve was short-lived. On June 29th, 2023, the Supreme Court struck down affirmative action in college admissions, emboldening legal challenges to corporate diversity programmes. By the end of that year, eleven states had passed anti-DEI laws; by mid-2025, that number reached 28.
Trump had campaigned against 'woke' business practices, and his return to office brought immediate executive action. In January 2025, he signed two executive orders directing federal agencies to 'terminate any equity-related plans' and investigate private-sector DEI programmes. Executive Order 14173 required federal contractors to certify they don't operate "illegal DEI" programmes, exposing non-compliant contractors to potential treble damages. On February 24th, 2026, Trump declared victory in his State of the Union address: "We ended DEI in America." Yet between Trump's declaration and the reality on the ground lies a picture that is neither as decisive nor as uniform as his words suggested.
Corporate retreats: Target and Walmart lead the rollback
The political pressure of 2023–2025 translated quickly into corporate action. Among US retailers, the rollbacks were neither tentative nor incremental:
- Target: On January 24th, 2025, just four days after Trump's anti-DEI executive orders, Target announced it would end its three-year DEI goals and its Racial Equity Action and Change (REACH) initiative. The retailer stopped participating in diversity indices and renamed its "Supplier Diversity" team to "Supplier Engagement." Seven months later, CEO Brian Cornell stepped down and transitioned to executive chairman. Analysts disagreed on whether the DEI rollback or operational struggles drove his departure .
- Walmart: The nation's largest retailer rolled back several DEI programmes in November 2024, choosing not to renew its five-year racial equity centre and ending supplier diversity goals. Conservative activist Robby Starbuck hailed Walmart's retrenchment as "the biggest win yet. " in the movement to “end wokeness.”
Target's double bind: The ICE crisis
Target's January 2025 DEI rollback was intended to reduce the retailer's exposure to political controversy.
Operation Metro Surge
In December 2025, the Department of Homeland Security launched Operation Metro Surge, deploying 3,000 federal immigration agents to Minnesota. The Trump administration simultaneously announced a 120% increase in ICE's workforce, adding 12,000+ officers. On January 7, 2026, ICE fatally shot Renee Good, a US citizen. On January 8, ICE agents detained two Target employees—both US citizens—at the Richfield, Minnesota, store in a widely circulated video. Target issued no public statement. Bloomberg characterised Target's silence as "overcorrection," arguing that while Target may have believed silence broadcast neutrality, "to customers and employees, it more likely suggests cooperation or collusion.”
Employee activism and corporate fear
More than 300 Target employees signed an internal letter urging executives to deny ICE access to Target properties without a warrant. Workers at multiple stores called out sick, fearing for their safety. On January 24th, Alex Pretti, a US citizen, was shot and killed during a Minneapolis protest. The next day, more than 60 Minnesota CEOs (including Target's incoming CEO) issued a cautious letter calling for "de-escalation" but neither condemning the killings nor calling for concrete action. The New York Times reported the muted response reflected "corporate fear of retaliation from the administration.
For Target, the silence contrasted sharply with its vocal 2020 response to George Floyd's murder. The company's trajectory from DEI champion (2020) to DEI sceptic (January 2025) to silent bystander (January–February 2026) illustrated what some call a "double bind": the DEI rollback failed to insulate Target from conservative criticism while alienating progressive customers and employees.
Broader retail impact
Target's predicament was not unique. Federal immigration enforcement targeted retail stores nationwide—Home Depot parking lots became a focal point for ICE sweeps, while hotel chains faced similar pressure: at least one franchisee's decision to decline rooms to ICE agents triggered a public rebuke from the authorities and the severing of its franchise agreement. Consumers organised multi-front boycotts. The "Resist and Unsubscribe" campaign targeted Amazon, Apple, Google, and others for ICE-enabling contracts. Target faced boycotts from both progressives, angered by the DEI rollback, and community members outraged by its ICE silence. Foot traffic fell 2% in Q4 2025.
In Worthington, Minnesota, where one in three residents is an immigrant, businesses reported sales declines of 50–70%. Latino grocery stores remained open but with locked doors, requiring employees to visually confirm that customers were not federal agents. The ICE surge threatened economic viability in communities where immigrant entrepreneurs had revived downtowns hollowed out decades earlier.
Legal uncertainty: When courts and agencies contradict each other
By early 2026, the legal landscape became a patchwork of competing rulings. On February 21st, 2025, a U.S. District Judge blocked key provisions of both executive orders, finding them "facially unconstitutionally vague." Nearly a year later, the U.S. Circuit Court of Appeals delivered a contrasting ruling in a separate case, vacating a preliminary injunction, ruling that Trump could direct agencies to terminate equity-related funding based on policy priorities.
For retailers, uncertainty crystallised when the Equal Employment Opportunity Commission (EEOC) targeted Nike on February 4th, 2026, investigating alleged discrimination against white employees based on Nike's public commitment to fill 30% of director positions with racial minorities. Yet six days later, EEOC backed down from investigating 20 major law firms, acknowledging compliance was "voluntary."
Later that month, the EEOC sued Coca-Cola, alleging that a two-day employer-sponsored networking event violated Title VII because only female employees were invited, excused from work, and paid, while male employees were excluded. The case suggested that the new enforcement climate was not limited to race-conscious targets or hiring goals; it could also reach sex-specific leadership and networking initiatives framed as inclusion efforts.
Private litigation compounded the pressure. A conservative legal strategist filed lawsuits challenging diversity fellowships at major law firms; three subsequently changed their eligibility criteria to allow any applicant to apply. McDonald's settled a lawsuit by opening its scholarship programme to "any student who can demonstrate an impact on or commitment to the Latino community."
The message was contradictory: DEI programmes faced heightened scrutiny, yet government enforcement authority remained contested and inconsistently applied. Federal contractors operated under strict prohibitions while non-contractors navigated murky guidance.
Holding the line or letting go: How department stores responded
Retailers responded with varying strategies. Macy's and Nordstrom maintained DEI commitments and chief diversity officers. Kohl's took a middle-ground approach, rebranding its role to "Chief Inclusion & Belonging Officer" in March 2025 while continuing related efforts. TJ Maxx maintains that "inclusion and diversity have been an important part of who we are." Smaller retailers like Faherty and Mason Dixie Foods publicly doubled down, framing DEI as core to company identity. Costco continues to support DEI initiatives, citing brand value alignment.
For retailers seeking a middle path, the evidence points toward inclusive universalism. Research by NYU suggests that opening diversity initiatives to everyone can encourage allyship, reduce backlash, and engage all employees in an inclusive culture. However, employees from historically marginalised groups may lose spaces for frank peer conversation—requiring acknowledgement of "what's been lost" rather than "toxic positivity."
From rollback to redesign: New DEI frameworks for retail
The question facing retailers in 2026 is not whether to pursue inclusion, but how to do so in ways that are legally defensible, genuinely effective, and able to survive the next political shift.
Levelling vs. Lifting
NYU research distinguishes between "lifting" strategies (targeted programmes for specific marginalised groups) and "levelling" strategies (removing bias from systems so processes become fairer for everyone). While lifting strategies face mounting legal challenges, levelling initiatives—structured interviewing, anonymised résumés, clear evaluation rubrics—create fairer processes and carry less legal risk. "The Supreme Court is never going to say it's illegal for an organisation to level the playing field by removing unconscious bias," a researcher notes.
The FAIR Framework
Inclusion consultant Lily Zheng's FAIR approach (Fairness, Access, Inclusion, Representation) prioritises "outcomes over intentions, systems over self-help, coalitions over cliques, and win-win over zero-sum." Rather than heritage month celebrations, FAIR demands interventions that solve problems by changing systems. Zheng reframes representation itself—shifting from demographic boxes to measuring trust: leaders who, regardless of identity, "understand our needs" and "speak with true understanding of what I care about." This emphasises the development of skills: critical thinking, relationship-building, and handling disagreement.
Targeted universalism
The most powerful concept is targeted universalism, developed by UC Berkeley's Othering and Belonging Institute: acknowledge group disparities while using that understanding to fix shared environmental problems. Zheng illustrates with a company where men dominated leadership but reported the worst well-being, while women had better outcomes but were underrepresented. Rather than framing it as a gender battle, they discovered that the underlying problem was a culture of overwork designed around the assumption that employees had stay-at-home spouses and few responsibilities outside work. Addressing the broken system improved outcomes for both men and women.
This embodies the "curb-cut effect"—when designing for those with the worst experiences, improvements benefit everyone. For retailers: rather than "How do we get more women into store management?" ask "What systemic barriers prevent excellent employees from advancing—and how do those barriers disproportionately affect certain groups?" Solving scheduling inflexibility or childcare support may disproportionately help women and parents while creating stronger talent pipelines for everyone.
As Target's experience illustrates — from DEI champion to rollback to ICE silence — attempts to sidestep inclusion through "neutrality" can backfire spectacularly. Trump's February 2026 declaration that "we ended DEI in America" glossed over a complex reality: while many companies rolled back targeted programmes under legal and political pressure, the work of creating fair, inclusive workplaces continue under different frameworks.
As documented in IADS' 2026 White Paper: DEI at a crossroads in retail, the retailers that weathered this period most effectively shared a common approach: DEI embedded in operations rather than siloed to HR, visible CEO backing, transparent communication during setbacks, and systems redesigned for their most marginalised employees — creating improvements that benefited everyone. The frameworks offered by various researchers suggest a clear direction: not abandoning the goal of fair workplace creation but reshaping how that work gets done. Systems-level changes removing bias don't just survive legal challenges — they build workplaces where everyone can contribute and advance based on actual merit. For retail facing persistent labour challenges and shifting consumer expectations, that is not just ethically sound — it is strategically essential.
By mid-February 2026, as Operation Metro Surge wound down, Target was left rebuilding trust on multiple fronts: with employees who felt abandoned, with customers questioning the company's values, and with a hometown that watched the retailer retreat from civic leadership. The lesson resonates beyond Target: the retailers that emerged from 2025–2026 with both credibility and capability intact were
Credits: Maya Sankoh
IADS Exclusive: Harrods points of differentiation
IADS Exclusive: Harrods points of differentiation
Few retailers conjure such immediate images of glamour, scale, and international cachet as Harrods. Yet behind the emerald-green awnings and gleaming marble halls lies a story of almost two centuries of reinvention. This single-site retailer has grown from a modest Victorian grocer’s shop into a global icon of luxury commerce. Harrods’ journey mirrors the evolution of modern retail itself: a chronicle of shrewd pivots and calculated risks, of disasters turned into opportunities, and of an unrelenting pursuit of the extraordinary in both product and experience.
We took the pretext of a member’s request on Harrods’ points of differentiation to proceed to an in-depth research about the iconic store. More than a department store, Harrods is a case study in how legacy can be leveraged, risks managed, and differentiation sharpened in a marketplace where change is the only constant. IADS CEOs were fortunate to have a behind-the-scenes visit in November 2023 during the General Assembly in London, with Mr G, a colourful character. We blend the notes taken during this visit with the results of thorough research to explore in more depth what Harrods represents today.
From “A small corner shop” in 1849…
Charles Henry Harrod opened his first venture in 1824, at the age of twenty-five: a drapery shop located in London’s South Bank, by then a district of taverns and inns. By 1834, having identified higher margins in the wholesale grocery trade, he pivoted towards selling pre-blended tea. He transferred to Cable Street, on the North Bank, and became recognised for his probity, as he insisted that only tea that he personally tasted could be sold in his premises.
However, the pivot took place in 1849, when Harrod identified an opportunity in Knightsbridge, which was then a semi-rural district adjacent to what would soon become the Crystal Palace grounds for the 1851 Great Exhibition. He leased a single-room shop at 105 Brompton Road to serve visitors to the exhibition, who discovered a merchant willing to dispatch hampers of preserves and teas to Glasgow, Calcutta, or Boston via the nascent railway and packet-boat networks. By 1855, it is said that Harrod employed 15 assistants and started annexing the neighbouring units.
Leadership passed to his son, Charles Digby Harrod, in 1861, who introduced new ideas, including dress fabrics, millinery, a perfumery counter, and, by 1870, a pharmacy. The introduction of fixed prices—still novel in Victorian England—liberated middle-class women from the chore of haggling and allowed them to shop unaccompanied, also accelerating turnover. Sales soared from an estimated £18,000 in 1861 to £118,000 by 1880 (equivalent to €19 million today). Technological innovations kept pace: gas-lit window displays extended trading hours, a lift expedited stock movement, and a pneumatic-tube network whisked cash to a central counting room.
On 6 December 1883, a fire destroyed the building on the eve of Christmas week. Overnight, Harrod rented a disused bakery, re-established departments and still posted a record profit, converting calamity into legend1. To finance reconstruction, he floated his company on the Stock Exchange in 1889, raising £120,000 and retiring days later.
The new board engaged architect Charles William Stephens, who erected today’s building in phases between 1894 and 1905. Innovation became a selling tool: in 1898, the store unveiled England’s first escalator (before the London Underground)—a leather‑belt “moving staircase” with staff waiting at the top with glasses of Cognac to comfort unnerved passengers. Electric lighting was the final touch, with 12,000 bulbs installed on the façade in 1906.
With the building complete, the company shifted focus from architecture to global reach. The Latin motto “Omnia Omnibus Ubique”—“All Things for All People, Everywhere”—was carved in 1908, coinciding with the launch of illustrated catalogues sent abroad. Orders arrived by telegram and, after 1911, by wireless. Export receipts accounted for an estimated 12‑15 % of turnover by the eve of the Great War.
The inter‑war decades burnished the store’s cultural cachet. Society diaries note lunching beneath the newly installed Art Nouveau stained‑glass dome of the first‑floor Georgian Restaurant (1913), where playwright Noël Coward reputedly purchased a baby alligator in the 1920s. Harrods also joined the International Association of Department Stores in 1928. Along with Filene’s from Boston and Printemps from Paris, to name a few, the then IADS members aimed to introduce modern management methods derived from the scientific management movement to their retail format.
During WWII, the Food Halls’ marble counters were sandbagged, and the basement converted into an air‑raid shelter. Despite rationing, the store maintained “Make‑Do‑and‑Mend” workshops and even a couture salon supplying utility clothing that met Ministry of Supply regulations but still permitted discreet elegance.
The 1950s brought optimism and a surge in interest. In 1959, House of Fraser outbid Debenhams to acquire Harrods for £7.6 million. The deal provided the flagship capital for mechanical goods-handling systems, while allowing operational autonomy—a “federal” model of ownership. During that period of ownership, the store was struck by an IRA car bomb, in which six were killed and ninety were injured[2].
House of Fraser sold Harrods (and itself[3]) to Egyptian‑born entrepreneur Mohamed Al‑Fayed for £615 million in 1985. Over the next quarter-century, Al-Fayed spent a reported £400 million on restorations that blurred the lines between commerce and spectacle: the themed Egyptian Hall with its gilded sarcophagi, the opaline-glass Egyptian Escalator, and marble memorials to Diana, Princess of Wales, and Dodi Al-Fayed. Footfall doubled from roughly 12 million in 1984 to 23 million by 1999, fueled by long-haul tourism and the weak sterling of the late-1990s Asian crisis. He pioneered experiential retail: celebrity book signings, Britain’s first in-store Ladurée tearoom in 2005, and the By Appointment personal-shopping suite introduced in 2006, which featured minimum-spend thresholds. Finally, Michael Ward was installed as managing director in 2005.
In May 2010, Qatar Holding, part of the Qatar Investment Authority (QIA), paid about £1.5 bn and invested in modernising the company:
- Harrods.com was launched in 2011, followed by a Mainland-China WeChat storefront in 2018,
- “Superbrands Hall”, a 3,716 sqm “store above the store”, opened in 2014 to monetise shop-in-shop tenancies from Chanel to Audemars Piguet,
- “The Residence”, unveiled in 2020, created a private-members’ enclave rumoured to require a £ 250,000 annual spend covenant.
Today, the Knightsbridge store occupies 92,000 sqm of selling space across eight public floors and 330 departments, supported by 22 branded restaurants and bars. It sells a wide variety of luxury products, from €5,000 per kg rare tea, to yachts or gold ingots (since 2010). Approximately 70% of the floor space is operated on a concession or consignment basis. Following the men’s department transformation and the beauty section renewal with a VIP section unveiled in 2016 at a cost of £200 million, another £200 million rolling refurbishment (2023-26) is reshaping sales floors as “experiential precincts.” The 1,500 sqm lingerie and loungewear hall opened in June 2023 (for £60 million), featuring wellness pods, fitting salons, and a café run by Parisian pâtissier Pierre Hermé. The Dining Hall’s relaunch in autumn 2024 introduced a complete offer of 22 chef-counter concepts—most notably a 12-seat omakase bar by Masayoshi Takayama, which now has a nine-month waiting list, and four distinct food halls (including an on-site chocolate factory and bakery). Finally, the “By Appointment” private-shopping suites on the hidden fifth floor are said to account for roughly 11% of GMV, with an average transaction value exceeding £55,000.
Baseline footfall rebounded to its pre-pandemic base of roughly 15 million visits, with peaks of up to 300,000 daily visitors in the Christmas trading window and the loyalty programme is believed to house 2m members. Revenue density in Knightsbridge is estimated to reach € 29,000 per sqm[4]. Overseas customers generate 45% of sales[5], despite the UK’s abolition of VAT-free shopping. To make sure a specific part of this clientele (Chinese tourists) is properly served even when not in the UK, Harrods opened a private member club in Shanghai in 2024.
Beyond Knightsbridge, the group operates six standalone H Beauty stores, a format of 2,000–2,800 sqm aimed at Millennial and Gen-Z luxury beauty shoppers. A seventh unit, in Chester, is under construction for 2025, followed by Leeds in 2026.
Harrods employs 4,550 FTEs, who follow a rigorous line of conduct to convey the excellence the store aims to represent. However, labour relations remain tricky, as shown by the strike mandate covering 176 shop-floor, hospitality and cleaning employees for the peak Christmas week of 2024 in a dispute over bonuses, service-charge distribution and pay indexation.
…to a diversified powerhouse in 2025
The Knightsbridge store operations, harrods.com, and the adjacent subsidiaries (including other stores, airlines, and real estate) sit within Harrods Ltd, a holding company. It is unclear where the Chinese club operations are located[6].
Full-year 2024 group results show gross transaction value up 6% (£2,25 bn), group turnover up 9% to £988.5, and store turnover up 8% to £898.4 m (+8% vs. LY), the highest in the store’s history. Operating profit edged up to £162.9 million, delivering an 18 % margin, while a one-off £46m pension buy-in trimmed pre-tax profit to £111.5 million. Despite that hit, Qatar Holding, the owner, took a £180m dividend for the second year running. Net cash closed at just over £50 million after capital expenditure of roughly £95m on store refurbishment and digital projects. Measured over four post-pandemic years, sales have compounded at a 27% annual rate and operating profit at a 33% yearly rate, outstripping every Western department-store peer in both metrics. Even after normalising for one-offs, its 18% operating margin dwarfs Western department-store averages (5-10%).
Online sales on harrods.com are estimated to have reached £230 million during FY2024, equivalent to 26% of retail turnover, with mobile devices accounting for 72% of sessions. A smart, RFID-enabled distribution centre at West Thurrock is set to go online in H2 2025, aiming to reduce click-to-ship times to below 90 minutes and eliminate 99% of picking errors. Also, in November 2024, Harrods adopted Global-e’s cross-border platform, localising pricing, payments, and duty prepayment for more than 200 markets. February 2025 marked the launch of an AI marketing partnership with Incubeta; its Seamless Search engine reallocates paid media spend in real-time across PPC, SEO, and social in the UK, US, GCC, and Asia hubs. Loyalty penetration has climbed to 87 % of transactions since the introduction of a new Platinum tier (annual spend threshold £50,000) within the five-level Harrods Rewards scheme. Repeat-purchase frequency averages 3.2 times per year across the Rewards base and 6.8 times for Black-tier members.
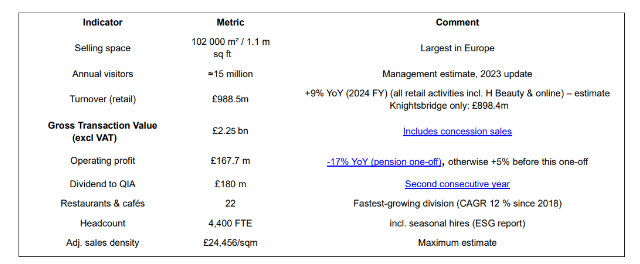
Regarding other activities, the aviation cluster—Harrods Aviation (FBO/MRO at Luton and Stansted) and Air Harrods helicopter charter—generated £78.8m of turnover in 2024 and employs 275 staff, feeding ultra-high-net-worth clients back to the retail and property arms. Harrods Estates, the prime-property brokerage, leverages Rewards-tier data but keeps its financials private.
Finally, as of FY2023, the board has incorporated explicit ESG and customer-experience key performance indicators into the audit and risk committee’s remit, aligning management remuneration with decarbonisation and service-quality milestones. Harrods’ inaugural ESG report logged a 2.4% absolute carbon reduction against the 2022 baseline and reiterated the 90% cut goal for 2030. Eighty per cent of lights are now LED, and trigeneration supplies a growing share of on-site energy. Major projects include a £60 million façade and HVAC retrofit—Phase I was completed in Q4 2024—which underpins the pledge to cut Scope 1–2 emissions by 90% by 2030.
What are Harrod’s points of differentiation?
While being unique in the world, Harrods competes in the same league as Selfridges, KaDeWe, Galeries Lafayette Haussmann, Saks Fifth Avenue, Isetan Shinjuku, SKP Beijing, Bergdorf Goodman, Hankyu Umeda, Shinsegae and El Corte Inglés Serrano Madrid. For this reason, we review how the store differentiates from this array of peers from a selection of criteria: real estate ownership, revenue density, the nature of the concession ecosystem, the private client culture, the approach to service and experience, and the loyalty and omnichannel approach.
Harrods occupies a five-acre, Grade II* listed city-block[1] that it controls outright; the 92,000 sqm selling floor was purpose-built for the brand between 1894 and 1905 and has remained under single ownership ever since. This freehold status (acquired in 1921) allows Harrods to avoid rent inflation or landlord risk that has crippled rivals such as KaDeWe, whose 2024 insolvency filing cited “significantly rising index-linked rents” as the key trigger. By contrast, Selfridges’ Oxford Street flagship sits in a separate property vehicle whose £638 million write-down last year illustrates the balance-sheet drag of leasehold real estate.
While Saks Fifth Avenue and Bergdorf Goodman all operate on highly-leveraged trophy real estate (Saks’ flagship alone is mortgaged at a $3.6 bn appraisal), owning the land lets Harrods commit substantial horizons of capital (e.g., a self-funded £300 m restoration of its historic Food Halls, a £200 m womenswear revamp slated to 2026).
Even though some commentators tried to assess department stores’ productivity, often on partial data (which raises questions, see the 2019 Sybarite report), Harrods was often cited pre-pandemic as the most productive department store in the world, outpaced by SKP during the pandemic in 2020-2021.
However, when looking at the details, proceeding to a complete comparison of companies is difficult when it comes to productivity:
- Selfridges and El Corte Inglés do not publish verified single-store turnover, forcing extrapolations.
- No verified information has been published by Isetan Shinjuku since 2007 regarding its size,
- When it comes to the definition of selling space itself, some groups exclude restaurants or event space, others include them.
- Chinese and Korean department stores quote tax-inclusive transaction value; Western peers report net revenue. Density rankings, therefore, give a directional, not absolute, comparison.
- SKP, Bergdorf Goodman and Galeries Lafayette figures rely on management statements rather than statutory filings.
- In a similar manner, gross transaction value for 2024 for Harrods is only released at the group level, not the store level, which makes the comparison slightly incorrect.
The below chart is a tentative ranking, taking into account the limitations above. While Asian mega-stores and Galeries Lafayette compete with Harrods in terms of sheer turnover, and in sales density by others, Harrods punches above its size in productivity, thanks to ultra-high conversion rates in luxury categories and tourist spending.
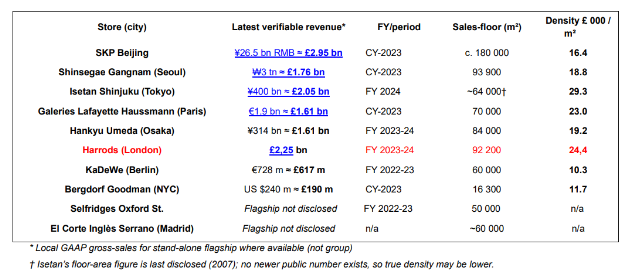
Harrods remains the archetype of the concession-first model (estimated to represent 70% of turnover): brands control product, staffing, and visual merchandising, while the store takes a commission or minimum rent, guaranteeing near-zero gross-margin risk and securing the store’s time-bound exclusives. Retail commentators have long noted that, unlike Selfridges’ pop-up-heavy strategy, Harrods “has stuck with its traditional model of in-store luxury brand concessions” as the core of its offer. For instance, on the sixth floor, Harrods boasts the world’s largest Apple concession, uniquely operated by Harrods rather than Apple itself. Harrods is also said to have a model where it provides staff, whose gross salary is passed on to brands, either in full or proportionally, according to their contractual agreement. Similarly Harrods is the only location to house a Tom Ford women’s store outside of the brand’s DOS network.
While Isetan maintains a traditional mix, Selfridges has moved closer to a wholesale and consignment model hybrid to drive newness and curation. Selfridges mitigates its risks by imposing guaranteed sell-through to many wholesale brands, while Bergdorf still carries significant own-buy risk in seasonal fashion. SKP Beijing replicates Harrods’ concession logic. Hankyu and KaDeWe blend concessions with outright buy, leaving them more exposed to markdowns in weak cycles. Harrods is one of the few Western stores that uses the concession structure at the whole-store scale, enabling more than 330 brand-managed spaces, increasing (by delegation) refresh cycles and gross margin.
As put by Michael Ward, “our customers come back as friends. It is not just a question of sales, but relationships.”
In addition to a Chief Customer Officer appointed as early as 2018, Harrods fields more than 3,000 customer-facing staff and formalises elite service through two-tiered programs: By Appointment (fifth-floor personal shopping with a worldwide-known quality of service) and Private Shopping – The Penthouse (invitation-only suites on the sixth floor with separate entrance). Comparable offers exist, but with less spatial grandeur: Bergdorf Goodman’s seventh-floor “BG Salon” occupies less than 10,000 sq ft each, versus Harrods’ full-floor 35,000 sq ft client area. Saks Fifth Avenue club rooms remain a minority of sales. Selfridges offers personal shopping suites on the first and second floors. SKP and Shinsegae run powerful VIP clubs, but none monetises membership as visibly in-store through physical By Appointment suites overlooking Hyde Park. Exclusivity extends to customer engagement, with only 250 elite customers selected by directors, representing 10% of the business.
To cater for the ultra-wealthy, security and exclusivity are paramount at Harrods, with more police on duty within the store than in the surrounding borough, and even a dedicated police station onsite.
In addition, the Knightsbridge flagship is only one profit engine powering a full ecosystem. Harrods operates:
- Harrods Aviation – two London-area FBOs turning over £78.8 m in 2024.
- H Beauty – five suburban beauty-only stores, seeding the brand with younger customers.
- Harrods International – franchised airport units from Heathrow to Shanghai.
- A private member club in Shanghai, opened in 2024, including a tea room, bar and Gordon Ramsay restaurant.
None of the peers has such an integrated private-aviation, specialist beauty chain ecosystem, or overseas club. That allows to provide a very specific experiential ecosystem for the wealthy: in-store, food-to-fork gastronomy (22 restaurants after the Georgian Room relaunch) plus on-site spa, safe-deposit vaults. Granted, Bergdorf and Saks excel at curated fashion edits; Galeries Lafayette and El Corte Inglés leverage tourist tax-free shopping. However, Harrods goes beyond by also providing the ecosystem outside of the store. While Selfridges has flirted with hotel and property development but remains retail-centric, KaDeWe and Galeries Lafayette have few meaningful non-retail subsidiaries, Isetan’s side-lines are largely food halls and credit cards, Harrods layers on aviation, helicopter charter and prime-property brokerage (businesses that add profit streams and feed ultra-high-net-worth clients back to Knightsbridge), enlarging its share-of-wallet beyond a store visit.
Loyalty and omnichannel approach
Harrods’ four-tier Rewards programme—recently augmented by a Platinum layer for clients spending £50 k+ per annum—delivers SKU-level data on approximately 2.8 million active members, feeding dynamic CRM and increasing lifetime spend. Loyalty IDs are linked to 87 % of transactions. Selfridges and Galeries Lafayette have broader membership bases but lower spend thresholds, limiting luxury specificity.
When it comes to online, Harrods has historically resisted a full e-commerce push until it could replicate concession economics online, first with Farfetch. Its 2024 Global-e partnership instantly opened 200+ localised markets while letting brands keep price control—again, landlord logic extended to the cloud. Most continental peers still rely on cross-border marketplaces or border-free shipping intermediaries rather than direct localisation. Selfridges.com and Saks.com are further advanced in terms of volume, yet rely on marketplace inventory models that dilute margin and branding discipline.
As a corollary, the store does not envision promotional activities in a traditional way, but rather as a collection of “theatrical experiences” available at each floor. It is all about leveraging private relationships with customers and creating a feeling of closeness with the store, as the iconic Christmas market or Rihanna launching in person her brand Fenty in 2021 suggest. There are no sales campaign apart from the Harrods Winter and Summer sales which remain very elegant and far away from promotional sales seen in other department stores.
What are the potential risks faced by Harrods?
Harrods’ performance edge rests on a delicate macro-and-micro balance that can be fragile.:
Since January 2021 the UK has refused non-EU visitors a VAT rebate, a decision that has pulled high-spending tourists towards Paris and Milan and cost London’s West End retailers an estimated £220 million in lost sales in the first half of 2024 alone. Internal modelling shared in lobbying documents seen by Walpole suggests that Harrods itself lost roughly £80-90 million of Chinese and GCC spend in FY 2024[1]. As long as the Treasury resists reinstating tax-free shopping, the growth will depend on compensating volume from domestic and US consumers whose currency advantage is already eroding.
Harrods’ ESG report discloses that just 4% of active shoppers account for 28% of revenue. A correction in luxury-equity valuations, further sanctions on Russian or Middle-Eastern elites, or geopolitical tension that curtails Gulf air routes could therefore reverberate disproportionately through top-line sales.
The Qatar Investment Authority has extracted consecutive £180 million dividends in the last two financial years, signalling a possible shift from long-duration capital stewardship to cash harvesting as the Gulf state funds other diversification projects. Should that preference harden, capex headroom for the ongoing £200 million Knightsbridge refurbishment could narrow, forcing trade-offs between experience upgrades and balance-sheet prudence.
Although Harrods has spent about £75 million updating its tech stack since 2018 and completed a 360-degree SAP/KPS customer-data rebuild in 2023, order-management and stock-ledger systems remain largely monolithic. By contrast, Selfridges moved to a micro-service architecture last year and now tasks multichannel teams with fulfilling most web orders inside 24 hours, a KPI advertised internally and in recruitment posts; Harrods’ average sits closer to two days. Lags of that magnitude can become visible to premium shoppers who benchmark their experiences against Farfetch‐style next-day standards.
SKP Beijing booked RMB 26.5 billion (£2.9 billion) in 2023, illustrating how purchasing power and brand exclusivity are clustering in Asia’s mega-malls. The same dynamic is visible in Shinsegae Gangnam and Isetan Shinjuku. If luxury brands choose to allocate limited-edition products on the basis of absolute volume, Harrods could cede pre-launch exclusives that have historically underpinned its differentiation. This is therefore interesting that they have opened a private member club in China, allowing them to leverage this presence to luxury brands and ask for ultra-exclusive collaborations or special editions.
The Knightsbridge block is Grade II*: every structural alteration requires listed-building consent under Westminster guidance, a process that local planning files show can extend beyond eight months for even minor plumbing or ductwork changes. Asset intensity thus stymies rapid re-configuration at a moment when luxury merchandising is shifting from static departments to theatrical, fast-turn “activations”.
The National Crime Agency’s unexplained-wealth-order pursuit of Zamira Hajiyeva, who spent more than £16 million at Harrods, spotlighted the store’s in-house bureau de change and its attraction for high-value cash clients; the case ended in a forced property forfeiture last August. The Financial Conduct Authority has since tightened monitoring of high-value dealers, meaning any lapse in anti-money-laundering controls could trigger fines or even suspension of the currency-exchange licence that lubricates tourist spending.
Conclusion: Harrods, a unique model?
Harrods’ differentiation is not a single attribute but a mutually reinforcing system: debt-free freehold real estate, global-class revenue density, a concession model that limits risk, a service culture scaled through data-rich loyalty, and lateral businesses—from aviation to H Beauty—that diversify earnings while feeding the core brand halo. Said in other words, and using Porter’s resource-based lens, Harrods converts location (Knightsbridge cluster of five-star hotels), hard assets (unencumbered freehold) and organisational heritage (175-year archives) into sustained differentiation. Among the expanded peer set, each competitor can match Harrods on one or two vectors (SKP on revenue, Bergdorf on architectural prestige, Shinsegae on turnover growth), but none combines all of them with the same depth.
Looking forward, management faces a triad of macro uncertainties—modulated Chinese tourism, geopolitical shocks and emergent regulation of high-end consumables—yet enjoys four built-in shock absorbers:
- Sovereign-wealth backing capable of counter-cyclical investment (which can also be a double-edged sword),
- A landlord-concession template that shifts inventory risk (but comes with its own constraints, too),
- A heritage narrative proven to restore confidence (unless, like in the Al Fayed sex scandal, some timebombs emerge),
- An ESG roadmap designed to meet stakeholder capitalism head-on.
Expansion is unlikely to resemble branch proliferation; instead, incremental monetisation of vertical space, deeper data-driven clienteling and selective brand residencies will probably continue to increase sales density.
Credits: IADS (Selvane Mohandas)
IADS Exclusive: The great beauty reset: department stores in search of a new model
IADS Exclusive: The great beauty reset: department stores in search of a new model
Beauty is no longer simply a category. It has become a strategic cornerstone for department stores, as the category is booming but is also highly challenged. Department stores used to be the primary channel for beauty discovery, but e-commerce and social media have eroded their historical authority. As an example, only 24% of US shoppers now visit a department store to learn about new products. Instead, 71% turn to Sephora or Ulta Beauty, according to a PowerReviews survey. In parallel, department store revenues are declining across much of the sector, and apparel and luxury are facing structural headwinds. Under such circumstances, the relevance of the beauty offer across all its dimensions becomes critical. Galeries Lafayette Haussmann has recently unveiled its new beauty department, the perfect occasion to gain perspective on the current state of beauty in department stores and to address a pressing question: is it possible to evolve the category model?
Floors reborn: department stores bet big on beauty reinvention
Nordstrom: beauty takes centre stage in NYC
The picture is not completely bleak for department stores. As a replenishable category, beauty is structurally resilient. From that perspective, many department stores accelerated their in-store investments to create beauty destinations in an attempt to counter competition from speciality retailers. In August 2025, Nordstrom unveiled its new beauty floor at its NYC flagship store, turning what had been a fragmented experience into a unified beauty destination. Positioned at the main entrance, the rationale is simple: beauty should be the first thing customers see when they walk in.
The new space is organised into distinct but connected zones.
- A large make-up zone at the store entrance with brands like Charlotte Tilbury, MAC and Westman Atelier. The Beauty Bar, a communal space where customers can test products from different brands, attend makeup classes or experiment on their own terms, is a new feature. A dedicated area for emerging brands completes the section.
- Then, the space flows into a luxury and designer zone housing names like La Mer, La Prairie and Dior, each with their full store concept.
- The fragrance area has been doubled in size, featuring a floor-to-ceiling floral installation and an exclusive new technology called “AirParfum,” developed with Puig, which allows customers to discover up to 60 scents without overwhelming the senses.
- Finally, a section oriented towards beauty rituals offers a more open, self-discovery format covering skincare, haircare, body and wellness, with heritage brands like Estée Lauder and newer labels like Tata Harper and 111Skin.
Beyond the products, Nordstrom is investing heavily in service and community with a team of around 100 sales associates, a full-time beauty concierge team for agnostic advisory and a packed event calendar. There is also a medi-spa in addition to 250 free or paid services, ranging from nail and brow services to blowouts. The beauty department now spans 1,670 sqm, more than doubling the previous layout, signalling that the retailer is not just selling beauty products but building a destination.
Macy’s Herald Square classic beauty overhaul
In November 2025, Macy's completed the first phase of a major renovation of its beauty floor at the NYC Herald Square flagship store, the first significant update in over a decade. Interestingly, around 70-75% of the store's beauty customers are locals rather than tourists, making the investment relevant far beyond passing visitors. Once fully finished, the space will span 5,000 sqm and have more than 20 new brand shops.
Right from the entrance, customers are welcomed by big names like Chanel and Dior, as is often the case on beauty floors. The customer journey moves from fashion-house shop-in-shops at the front, through niche brands and luxury skincare, to a trendier multi-brand discovery space at the back. With the current category boom, fragrance remains a key driver, with over 200 references across 65 brands, and Macy's continues to hold the largest share of fragrance sales in the country.
Also, following the beauty trend book, Macy’s adds technology and services to the experience, with AI-powered skin diagnostic tools from Shiseido, an augmented reality headset from Parfums de Marly, and five relaxation rooms. A new space is planned for events such as brand masterclasses and pop-up stores.
Selfridges goes niche: the fragrance hall reimagined
Selfridges has completed a major refresh of its fragrance hall at its London store in February 2026, marking the final phase of a two-year renovation of the entire beauty floor. Fragrance has become Selfridges' fastest-growing category, and the store has decided to lean into that momentum. Placed right at the main entrance, the hall aims to become a world-leading fragrance destination. The selection spans nearly 50 brands, with 75% of the offering dedicated to niche or limited-distribution brands, grouped into three distinct themes: established, contemporary and emerging. More than 30 exclusives are on offer, including names like Discothèque.
Niche houses such as Maison Crivelli, Marc-Antoine Barrois, Initio and Matière Première sit alongside heritage names, giving the space a sense of discovery. Rather than leaving customers to navigate scents on their own, Selfridges has placed knowledgeable sales associates throughout the hall to guide and advise.
Beyond capitals: John Lewis sets a blueprint for beauty in the regions
In August 2025, John Lewis unveiled a major transformation of its Liverpool beauty hall, showing beauty is also a priority in secondary city stores. The department has been expanded by almost 40% to 1,500 sqm. Interactive zones replace some of the traditional counters. The hall now houses 132 premium brands, including 23 new or expanded counters, and introduces exclusive brands such as Fenty Beauty, Trinny London, Byredo and Maison Francis Kurkdjian to Liverpool for the first time. This renovation emphasises service and social shopping to create a seamless integration between in-store atmosphere and online convenience. The transformation is a part of John Lewis's £800 million brand investment and reflects the retailer's success in the beauty category, where sales have grown by more than 40% over the past five years. The Liverpool concept will serve as a blueprint for five additional beauty hall transformations planned in the coming months.
The renovations undertaken by these department stores show that scale matters. Whether it is Nordstrom doubling its beauty footprint, Macy's committing to 5,000 sqm, or Selfridges offering 50 perfume brands, the strategy is clearly to compete with Sephora's depth and curation and the endless discovery possibilities offered by social media. Also, with Nordstrom's concierge team and Selfridges’ fragrance experts, it seems retailers are betting on people to deliver a differentiating, more agnostic beauty experience. In a world where any product can be purchased with a click, expertise and experience are the true differentiators.
Beyond the brand counter: the beauty business model at a crossroads
The Sephora effect: the rise of brand-agnostic beauty spaces
Transforming the traditional brand counters beauty model into more open, experiential spaces is a growing concern on the department store beauty floors. Customers are now accustomed to browsing at Sephora or Space NK and tend to reject the conventional model with brand counters and their staff attached. Instead, they are increasingly expecting retailers to offer them the possibility to explore a range of brands and products with agnostic sales advisors who can guide them across all options. For department stores so far, the question has been more about how to best adapt to this trend than about transforming the brand counter business model. Complementing rather than replacing brand counters, many department stores are developing multi-brand areas. These spaces allow customers to browse freely and touch products. However, they usually offer a limited number of brands, as is the case at the Galeries Lafayette Haussmann store’s space dedicated to emerging and niche brands positioned at the centre of the Wellness Galerie. Dedicated Galeries Lafayette staff help shoppers in their decision. Display tables serve as small pop-up spaces, allowing for brand rotation and product novelty. The space is not big, though it gives a true sense of choice and is successful. Galeries Lafayette recently took a further step toward agnostic shopping by opening a second multi-brand area. In March 2026, they unveiled a 250 sqm “French pharmacy” space (also known as dermo-cosmetics). This time, using a different business model, it is operated by an external partner (Carré Opéra Pharmabest) on a concession basis with staff attached to the partner. Answering locals and tourists’ appetite for French pharmacy with 200 brands (such as La Roche-Posay, Bioderma, SVR, Caudalie, Nuxe, Melvita, Vichy, etc.) and 6,000 references, the launch has been successful with customers filling their baskets with several products at the same time.
A few years ago, Manor also onboarded external partners: L’Oréal for dermo-cosmetics spaces (including brands like La Roche Posay or CeraVe) and Sephora to offer Gen Z customers trendy colour cosmetics brands as well as the Sephora Collection private label. More recently, Manor has moved forward in developing multi-brand areas, with the Green Beauty Lab. The space includes brands such as Glowery, Melvita, Erborian, Weleda and Avril in addition to the dermo-cosmetics brands, organised under four distinct areas: clean, botanical, wellness and sustainable. This concept will be rolled out in ten stores with local adaptations. These examples show attempts to step back, at least in part, from the brand-counter-only model. It offers customers a more agnostic shopping experience and, in the case of Sephora, allows Manor to also carry additional brands which may have been difficult to attract otherwise.
Falabella’s Glow Bar is also a recent example of a multi-brand space. The first 80 sqm pink space gathers 55 brands in skincare, makeup, fragrances, hair care, accessories, dermo-cosmetics and a prominent K-beauty section. Inspired by international benchmarks in beauty speciality retail, the company aims to offer a curated, experiential format focused on trend discovery, including Fenty Beauty arriving in the country for the first time. This launch clearly caters to consumers seeking experience, novelty, expert advice and, most important of all, the freedom to browse and try before you buy.
Galeries Lafayette's three-floor beauty vision
The recent beauty rehaul at the Galeries Lafayette Haussmann store offers more than a French pharmacy space. In fact, the beauty department now spans three floors, a deliberate vertical journey as stated by CEO Arthur Lemoine:
- The -1 floor offers a renewed version of the Wellness Galerie opened in 2022, oriented towards care brands (see more below).
- The ground floor centres on fragrance and makeup. The integration of new hot brands such as Victoria Beckham and Louis Vuitton makeup offerings increased the ground floor appeal. In parallel, they introduced a section of 13 niche fragrance brands, including Bottega Veneta and Creed.
- Creating a destination within the luxury RTW floor, the +1 floor proposes a convergence between luxury fashion, jewellery and beauty with high perfumery spaces for Loewe, Guerlain, Dior, Chanel, Maison Francis Kurkdjian, Officine Universelle Buly 1803 and, from June, Saint Laurent's first-ever beauty-accessories fusion concept.
This overhaul aims to differentiate Galeries Lafayette from competitors by providing an experience that blends luxury and beauty, for a lifestyle feeling and a customer journey that encourages cross-category discovery and higher conversion rates. Now accounting for about 10% of the store’s annual volume, beauty has posted double-digit growth, continuing into 2026. The refurbishment has expanded the beauty selling space to 3,700 sqm, an increase of 500 sqm and brought the total brand count to 440.
The normalisation of wellness
Harrods' closed-door wellness: when retail meets the clinic
Shifts in customer behaviour towards self-care, the relentless need for retailers to diversify into new categories and to add a revenue stream by taking a share of a business McKinsey estimated at around $1.5 trillion in 2020… these are all reasons why retailers have explored wellness. What was initially a blurry category encompassing fitness, nutrition, overall physical and mental health and appearance, is now normalised, with a key question at its core: services as a way to evolve the business model.
First on the trend, Harrods made a bold move in 2017 by opening a closed-door, appointment-only Wellness Clinic on the fourth floor in Knightsbridge, a significant shift in how luxury department stores were beginning to think about beauty and wellbeing. Spanning almost 1,000 sqm, the space was never intended to be a traditional spa or beauty salon. Instead, Harrods’ very own take on wellness was conceived as a high-end, results-driven clinic offering a curated selection of treatments.
The space was designed to feel clinical without being cold, and luxurious without being indulgent. The goal was not pampering but rather treatments with measurable results. The range was unusually wide for a department store. Harrods assembled a multidisciplinary team covering everything from injectables and body contouring to cryotherapy, DNA-based personalised skincare, IV vitamin infusions, and more. A dedicated partnership with a wellness expert brought daily personal training and nutritional coaching on site, with a bespoke programme created exclusively for Harrods clients. The Wellness Clinic also offers dental services, osteopathy, podiatry and physiotherapy. More than simply a new service, the Wellness Clinic, which is still running to this day, was an early and clear signal that brick-and-mortar retail needed to reinvent its purpose, and that experience, expertise and personalisation were the most important reasons to visit a department store. However, it didn’t reinvent beauty in department stores, just evolving and developing beauty services to a scale never seen before
From ambition to pragmatism: Galeries Lafayette’s reality check
Galeries Lafayette also made headlines in 2022 when the Wellness Galerie opened on a whopping 3,000 sqm surface spanning the whole -1 floor of the Haussmann flagship store. It was a step forward in terms of space and share allocated to services compared to products, with an impressive 60%-40% ratio. Galeries Lafayette had an ambitious goal: becoming the destination for well-being in Paris, with a gym studio, a healthy restaurant, a full catalogue of services such as osteopathy, cryotherapy, hyperbaric chamber, meditation, muscle strengthening, yoga and Pilates, infrared saunas, anti-ageing and silhouette-enhancing treatments, nutritional coaching, physiotherapist, nails and brow services and more. The brands embedded in the space were oriented towards care, as exemplified by the multi-brand area (see above) and traditional brand counters such as Barbara Stürm, Augustinus Bader, Clinique and The Ordinary, to name a few.
In March 2026, they unveiled an updated version of the Wellness Galerie. Department store floors are obviously in constant evolution, but this rehaul probably demonstrates how challenging it is to convey the wellness message to customers to maximise service profitability. Maintaining some of the previous services such as massages, anti-ageing treatments, brow and nail salons and the gym, the revamp emphasises a “care” message over the wellness word and adopts a more classic approach to services. Their overall number has decreased, but the most important difference lies in the addition of brands’ three-walls shop-in-shops, large enough to accommodate beauty cabins, doubling the number of treatment rooms to 20 (with Clarins, La Mer, Estée Lauder, Helena Rubinstein, EviDenS, for example).
The contrasting trajectories of Harrods and Galeries Lafayette offer a picture of where wellness stands in department stores, showing the commercial tension at the heart of the “category”: services are expensive to operate, difficult to scale, and require more customer education than products. Harrods' model endures because it never tried to democratise wellness. By keeping its clinic expensive and appointment-only, it defined a niche that aligned with its affluent clientele and price positioning. It did not attempt to reinvent the beauty floor. Galeries Lafayette's original Wellness Galerie was a genuine experiment in rethinking what a beauty floor could be: a rethink of the business model through an extensive catalogue of services. Both a sign of maturity and normalisation of wellness, the 2026 revision also shows how difficult it is to change the business model. As Lemoine describes it, the floor is now capitalising on the right balance between services and products.
The satellite bet: additional commercial models against competition
From anchor to standalone: how Harrods built a scalable off-flagship business
Despite competition from local retailers such as Space NK, The Fragrance Shop and Superdrug, Harrods has long held its position as the UK’s biggest beauty retailer, with a 9.3% share of the national market from a single 8,300 sqm location. In 2019, they announced an ambitious expansion plan with the launch of H Beauty, a new concept of standalone beauty boutiques set to open across the UK. The first store opened in late 2020, swapping Harrods' green signature for a pink aesthetic, deliberately targeting a younger, digitally savvy generation.
The first stores didn’t open in a prestigious city-centre location, but in the suburban shopping centres Intu Lakeside in Essex and Intu in Milton Keynes. The rationale was clear: the flagship in Knightsbridge caters primarily to tourists and an older, wealthier demographic, while H Beauty would be explicitly designed to reach a younger, local consumer base that had shopped previously at competitors. Stores are built around experience and exclusivity, with makeup stations, virtual try-on mirrors and masterclasses, all part of a broader omnichannel vision.
Industry reactions were mixed in 2019: some questioned why Harrods had not chosen a more premium location, while others saw it as a smart and timely move to claim territory before competitors did, aka Sephora (which would enter the market in 2023). What most agreed on was that the success of H Beauty would ultimately depend on the quality of the in-store experience and Harrods' ability to translate its luxury credentials into a format that is accessible to younger customers. In 2026, Harrods operates seven H Beauty stores, demonstrating a successful model that is giving the department store greater control and access over brands.
The limits of the concept: Harvey Nichols' standalone bet failed
Not all department stores were as successful as Harrods. In March 2025, Harvey Nichols announced they would close their only standalone beauty shop, Beauty Bazaar, in Liverpool’s ONE shopping centre. Opened in 2012, the store was originally considered a pioneering concept, as it was the first time a major luxury retailer had created an entirely dedicated beauty and wellbeing space of this kind outside of London. It was supposed to set a new benchmark for what a beauty destination could look like: a single space where luxury retail, social experience and professional treatments could coexist under one roof.
The ground floor brought together established international names and niche and contemporary brands, for depth and discovery. A standout feature was a perfume library designed to let customers explore fragrances freely, with no counter or sales assistant standing between them and the bottles. The +1 floor was more social. A champagne and cocktail bar was surrounded by open treatment areas for pedicures, a hair salon, brow, lashes and nail services. Customers could browse, book treatments, or shop online via iPads, making the floor feel as much like a social venue as a beauty destination. The +2 floor completed the journey with a private spa reminiscent of a five-star hotel.
The department stores’ investments in beauty are striking in their scale and their ambition. The message is consistent: beauty is no longer just a floor, but rather a strategy. Department stores are not simply upgrading a category: with its repeatability and experiential potential, beauty has to stay on-trend, but also becomes an answer when apparel stumbles and luxury fragments and grows increasingly direct-to-consumer.
Away from the brand counter and towards spaces that prioritise the customer's journey, the rise of multi-brand zones points to an industry that has absorbed Sephora's lessons and is acting on them. Partnering with external specialists represents a pragmatic willingness to give away control in exchange for relevance. The wellness chapter offers a more sobering lesson. Galeries Lafayette's Wellness Galerie was visionary. Its recalibration is grounded. Harrods' Wellness Clinic endures, but it is the exception rather than the rule. For most department stores, wellness will remain a layer rather than a foundation. The H Beauty satellite experiments add a final dimension and a possible, yet not universal, growth vehicle to reach demographics that a single store cannot do.
Credits: IADS (Christine Montard)
IADS Exclusive: From exclusive to inclusive – Lessons from Abercrombie & Fitch’s DEI journey
IADS Exclusive: From exclusive to inclusive – Lessons from Abercrombie & Fitch’s DEI journey
Abercrombie & Fitch (A&F) was once the epitome of “cool” for American teens in the late 1990s and early 2000s – a brand built on exclusivity, aspirational imagery, and a very narrow definition of who fits in. Its stores, with thumping music and overpowering cologne, became social hubs for youth and symbolised status for those deemed attractive enough to “wear the moose”. Yet the same exclusivity that fuelled Abercrombie’s rise eventually led to its fall. Controversies over discrimination and a lack of diversity tarnished the brand’s image, leading to lawsuits, public backlash, and a significant loss of relevance.
This is why, in the 2025 IADS White Paper, DEI at a crossroads in retail, Abercrombie & Fitch is cited as a case where DEI was neglected, inconsistently sustained, and ultimately mishandled—resulting in significant reputational, cultural, and operational consequences. Positioned as a lesson from the field rather than an isolated failure, the brand’s trajectory illustrates how progress on inclusion is neither linear nor guaranteed.
This Exclusive examines Abercrombie & Fitch’s history through a DEI (Diversity, Equity, and Inclusion) lens – how an exclusionary culture caused harm, who was most impacted, and what lessons retail and department store leaders can draw from A&F’s reckoning and ongoing turnaround.
The rise of an exclusive brand
A&F’s modern incarnation was crafted in the 1990s under CEO Mike Jeffries, who transformed the 100-year-old sporting goods outfitter into a preppy, sexy, youth-oriented apparel empire. Jeffres’ vision fused Calvin Klein-style provocative marketing with Ralph Lauren’s all-American prep, sold at prices teens could aspire to. The brand cultivated a “cool kids” image at every turn. Stores were designed like nightclubs, with thumping music, dim lighting, and a signature musk (Fierce) sprayed into the air to create an exclusive atmosphere that drew young shoppers. Staff were hired for looks and instructed to appear nonchalant (even borderline snobbish) toward customers, reinforcing the sense that shopping at A&F was a privilege. Teens of the era, lacking today’s social media, took cues from mall culture and A&F’s giant glossy ads to learn what was “in”. In the late ‘90s and early ‘00s, Abercrombie & Fitch became a pop culture phenomenon, defining teen fashion and beauty standards. However, those standards were largely “thin, white, and young”, as described in the Netflix documentary White Hot: The Rise & Fall of Abercrombie & Fitch (2022).
Abercrombie & Fitch’s marketing in the 1990s-2000S glorified and idealised an exclusive image. Stores prominently displayed huge posters of scantily clad, athletic young models (usually white), reflecting CEO Mike Jeefries’ vision of “attractive, all-American” youth. This aspirational branding, combined with dimly lit, music-filled stores and “cool” aloo staff, made A&F a status symbol for some shoppers while implicitly alienating those who didn’t fit the mould.
From advertising to store associates, Abercrombie’s concept of “All-American” was extremely narrow. Former CEO Mike Jeffries infamously admitted that the brand was built on exclusion: “We go after the cool kids… A lot of people don’t belong [in our clothes], and they can’t belong. Are we exclusionary? Absolutely.” In practice, this meant A&F’s public image featured almost exclusively white, fit, conventionally attractive models and actors. The company deliberately did not offer plus sizes for women for many years (women above size 101 or so simply weren’t apart of the target look). In the store environment, “all-American” often functioned as code for white, a reality that would soon lead to serious trouble.
Exclusion by design
Abercrombie’s exclusionary ethos extended beyond marketing; it permeated hiring and operations. By the early 2000s, reports and complaints surfaced that A&F was systematically hiring and promoting based on looks and race. Store managers were under pressure to staff sales floors with what the company deemed “on-brand” people – overwhelmingly white, clean-cut, and slim. Minorities who were hired were often assigned to back-of-store stockroom positions or had their hours cut if they didn’t fit the desired image. In one noted case, a Latino applicant was told he could work in the stock room but not out front with customers, a humiliation he later described in court. The company even had “Look Policy” guidelines forbidding certain personal styles disproportionately associated with nonwhite individuals (for example, banning dreadlocks for employees).
These practices led to a landmark class action lawsuit in 2003 (Gonzalez v. Abercrombie & Fitch), filed by Asian American, Black, Latino, and female plaintiffs. They charged that Abercrombie refused to hire qualified minority candidates for sales jobs, or hid them in the back, solely because they didn’t match the “A&F look.” The case uncovered that recruiting often targeted white fraternities and sororities to pipeline “attractive” (and mostly white) staff, and managers were instructed to maintain the look, even if it meant overt discrimination. In late 2004, A&F settled the lawsuit for about $40 million without admitting wrongdoing. The settlement’s consent decree required Abercrombie to address its biased practices: the company had to implement diversity programs, hire a Vice President of Diversity & Inclusion, bring in 25 recruiters to recruit minority employees, and ensure that marketing materials included models of colour. Essentially, Abercrombie was forced to implement basic DEI measures that, in hindsight, could have prevented the debacle in the first place.
Around the same time, A&F’s marketing provoked public outrage for racism and insensitivity. The brand produced graphic T-shirts with caricatures and slogans that offended Asian Americans – most notoriously a shirt featuring two smiling Asian figures and the words “Two Wongs Can Make It White,” which played on a racist trope. After Asian American student groups organised protests and boycotts, the company pulled the shirts and issued a sheepish apology. But the pattern of operating “in a bubble” with tone-deaf ideas was clear. Abercrombie’s exclusion was so entrenched that even satirists took notice – comedy sketches lampooned the brand’s elite, white image and the unfriendly attitude of its store staff. By the early 2010s, Abercrombie was increasingly seen as out of touch and out of step with evolving social values.
One flashpoint came in 2013, when comments Mike Jeffries had made years earlier resurfaced and went viral. In a 2006 interview, Jeffries proudly embraced “exclusionary” marketing and suggested that A&F wanted only “thin and beautiful” people wearing their clothes. The public reaction in 2013 was swift and negative – petitions garnered thousands of signatures urging Abercrombie to offer larger sizes and to stop “fat shaming” would-be customers. That year, a young activist named Benjamin O’Keefe started a viral petition calling out Abercrombie’s discriminatory sizing and marketing; he urged a boycott until the brand catered to “people of all sizes.” Looking back, O’Keefe said, “They [A&F] rooted themselves in discrimination at every single level.” His campaign captured a growing sentiment that Abercrombie’s once “cool” exclusivity had become ugly and unacceptable.
Impact on people and culture
For those who didn’t fit Abercrombie’s narrow ideal, the brand’s practices were more than just offensive – they were personally damaging. Employees and job applicants from minority backgrounds were perhaps the most directly harmed. Numerous young people had the experience of being implicitly told “you’re not what we’re looking for” because of their skin colour, ethnicity, or features. The 2003 lawsuit included students from Stanford and other colleges who were deeply discouraged after being steered away from customer-facing roles for being Latino, Black, or Asian. This kind of bias not only denied equal opportunity but also inflicted lasting psychological harm on those rejected for who they were. As one plaintiff recalled, “I felt it was because I was a Latino – but there was no one I could report this to at the time.” The legal case finally gave these youths a voice and a measure of justice through compensation and mandated reforms.
Customers were also affected in less quantifiable but real ways. Throughout the 2000s, A&F’s advertising sent a message that only certain people were “cool enough” for the brand – namely, white, athletic, attractive teens. This contributed to a toxic beauty standard that left many young people feeling inferior. Teenagers who were heavier, or of a different race, or couldn’t afford the clothes, often internalised that they “didn’t belong” in Abercrombie’s world. The documentary White Hot: The Rise & Fall of Abercrombie & Fitch notes that the brand “kept those messages pretty overt” about whose bodies and looks were considered right. In an era before body positivity and diversity were mainstream, A&F’s popularity actually amplified insecurities among those on the outside. As director Alison Klayman observed, talking about Abercrombie inevitably brings up personal stories about “body insecurities” and “what it meant to be a young person” bombarded with these images.
Additionally, certain religious and cultural groups clashed with Abercrombie’s policies. A notable example is the case of a Muslim teenager who in 2008 was denied a sales job because she wore a hijab, which violated Abercrombie’s strict “Look Policy” prohibiting head coverings. This led to a lawsuit that went all the way to the U.S. Supreme Court. In 2015, the Court ruled 8–1 against Abercrombie, declaring that refusing to hire someone in order to avoid accommodating a religious practice (like wearing a hijab) was a violation of civil rights law. The Supreme Court decision underscored how discriminatory policies had been literally built into Abercrombie’s dress code, and it further damaged the company’s reputation. By then, what once was sold as the “perfect All-American look” had been widely exposed as a euphemism for prejudice, alienating not only people of color but anyone who didn’t mirror the company’s very limited image of American youth.
The fall : business consequences of a toxic culture
The social and legal backlash against Abercrombie & Fitch ultimately led to significant business problems. In the late 1990s, exclusivity might have helped A&F stand out, but by the 2010s, consumer values had shifted dramatically. A new generation prioritised inclusion and social justice, and they had many more clothing options. A&F’s sales plunged as teens and young adults flocked to competitors that seemed more inclusive or authentic. By the mid-2010s, the once “white hot” brand was losing money and closing stores. Its image was stale – even to its core audience. As one commentator put it, exclusion stopped being cool. Many shoppers simply “don’t spend money where you feel bad about yourself”, and Abercrombie has made a lot of people feel bad
Internally, the company also struggled. After 2004, Abercrombie did make some superficial changes under the consent decree – hiring more people of colour, adding diversity training – but the toxic ethos persisted. Executives like Jeffries did not publicly acknowledge the cultural failings. Former diversity officer Todd Corley later noted that while he managed to increase the diversity of the workforce (A&F went from about 90% white employees to closer to 50% white in roughly eight years), he often lacked full support. Jeffries continued to make tone-deaf remarks or policies that “arguably worked against Corley’s progress”. Indeed, when the court-appointed monitoring ended in 2011, Abercrombie was quick to slip back into old habits in marketing, still featuring almost all-white models in giant store posters. The culture at the top had not fundamentally changed. This tension culminated in Mike Jeffries’ ouster in late 2014 amid slumping sales and mounting public criticism. By then, Abercrombie & Fitch had, in the words of one retail analyst, burned “white hot” and burned out– it had lost the cachet it once exploited, and was left with a battered reputation among both consumers and prospective employees.
Notably, revelations about the deeper dysfunction of Abercrombie’s leadership continued to emerge even after Jeffries’ departure. In 2023, news investigations alleged that Mike Jeffries had engaged in exploitative conduct with models during his tenure. Such headlines reinforce how a company culture that tolerated discrimination and objectification can breed other unethical behaviours. Abercrombie’s fall stands as a cautionary tale: a brand that glorified exclusivity to the point of discrimination sowed the seeds of its own decline.
Turning the ship: Abercrombie’s attempt at reinvention
With Jeffries gone and mounting pressure to improve, Abercrombie & Fitch began a slow turnaround, seeking to transform itself from an exclusionary brand to a far more inclusive one. New leadership took the helm – most notably Fran Horowitz, who became CEO in 2017. Horowitz publicly acknowledged that Abercrombie had to fundamentally change, saying “We are fundamentally a different company than we were back then” and “very focused on diversity and inclusion”. Under her direction, A&F finally abandoned the “cool kids only” playbook and made moves to invite a broader range of customers:
- Inclusive marketing: The company dropped its hyper-sexualised, whitewashed ads. Abercrombie’s campaigns now feature models of many different skin tones, body types, and sizes, emphasising real people and everyday stories instead of unattainable fantasies. This shift aligns the brand with modern expectations – as the director of White Hot noted, Abercrombie’s new imagery “puts them in line with what good business looks like today”.
- Product range and sizing: Abercrombie finally extended its sizing and styles to cater to more body types. It introduced “Curve Love” jeans and expanded women’s sizes beyond the previous limits. By embracing plus-size customers and offering more diverse fits (looser cuts, curvy fits, etc.), the brand signalled that everyone is welcome – a stark contrast to its old stance of refusing to carry larger sizes. These changes not only won back some customers but even created a “cult following” for certain inclusive products like the Curve Love line.
- Workforce & culture: Building on earlier efforts, A&F’s workforce today is much more diverse, and the overt “look” biases have been curtailed. Store associates are no longer hired (or fired) based on a single aesthetic mold. There’s also a greater emphasis on employee experience and openness – a far cry from the days when only one kind of person could thrive at the company. (It’s telling that Abercrombie won several Best Place to Work for LGBTQ Equality awards in the late 2000s under Corley’s guidance, reflecting some cultural growth.) Still, questions remain about how fully the internal culture has reckoned with the past; meaningful inclusion requires ongoing commitment beyond just marketing fixes.
These reforms have started to pay off. By 2021–2022, Abercrombie’s sales had stabilised and even grown, after years of decline. The company’s rebrand resonated with some young adults who rediscovered the label after it shed its old baggage. On TikTok, for instance, the hashtag #AbercrombieIsBack trended as new customers showed off the revamped styles and messaging. A&F’s share price rebounded as investors gained confidence in the turnaround. While Abercrombie will likely never dominate culture the way it did in 1999, it has at least moved from being a case study in exclusion to a case study in redemption through inclusion.
Horowitz’s strategy – focusing on knowing the customer and “meticulously building the product, voice and experience to match their needs” – is essentially a customer-centric approach that couldn’t be more different from the old Jeffries approach. Where Abercrombie once dictated a fantasy to consumers, it now listens and adapts to them. That includes the simple realisation: diversity is a business imperative. In fact, part of the 2004 consent decree was a line from civil rights attorneys noting “Abercrombie now realises diversity makes good business sense”– a lesson it took the company another decade to truly embrace.
Lessons for retail
Abercrombie & Fitch’s DEI journey – from exclusive to inclusive (and still in progress) – offers several powerful lessons for retailers and consumer brands in general:
- Exclusion is not a sustainable strategy: What might create short-term buzz, or a feeling of “elite” coolness, can backfire spectacularly. Catering to a narrow ideal of beauty or identity alienates large segments of potential customers and ultimately becomes a liability as societal values evolve. In retail, coolness is a moving target, but respect and inclusion have enduring value. Brands that hinge their appeal on putting others down are on borrowed time.
- Diversity and inclusion are smart business: Embracing DEI is not just a moral stance but a market opportunity. A&F learned the hard way that exclusion comes with real business consequences. By excluding large demographics (whether through limited sizing, racist imagery, or biased hiring), Abercrombie left money on the table for years. Retailers succeed when customers feel seen and welcome – which translates into broader market reach and loyalty. Companies, from department stores to startups, can take note: an inclusive brand can attract a wider customer base and avoid unnecessary reputational risks.
- Toxic culture starts at the top: Abercrombie’s downfall illustrates how leadership attitudes cascade into company culture. Jeffries’ openly exclusionary philosophy became “baked in” to every policy, from hiring to marketing. Leaders in any organisation must recognise their role in setting the tone. A culture that tolerates discrimination or objectification in any form will eventually face scandal or legal action, as seen with A&F’s lawsuits and even the personal misconduct allegations against its former CEO. Conversely, leadership commitment to inclusion can drive positive change – Horowitz’s approach has clearly helped rehabilitate Abercrombie’s culture and image.
- Accountability and continuous improvement: A&F’s initial responses (settlements, hiring a diversity officer, etc.) were not enough because they weren’t accompanied by genuine accountability or attitude shifts. The consent decree imposed changes, but once external monitoring ended, old habits crept back. True inclusion is an ongoing effort, not a one-off PR fix. Retailers must continuously engage with diverse voices (employees, customers, consultants) to identify blind spots and hold themselves accountable to progress even when public attention wanes.
- Representation matters: One of the simplest takeaways is the importance of representation in both branding and staffing. Abercrombie’s story shows that seeing only one type of person in ads or in sales roles sends a message – and people notice. Modern consumers expect brands, especially mainstream retailers and department stores, to reflect the real diversity of society. This means featuring different races, body types, ages, and abilities in advertising, and ensuring inclusive hiring from the sales floor to the boardroom. Representation isn’t about political correctness; it tangibly impacts how welcome customers and employees feel.
Conclusion: DEI as part of retail resilience
The saga of Abercrombie & Fitch serves as a lesson from the field in how a deliberately cultivated image of exclusivity became a company’s Achilles’ heel. What was once heralded as “aspirational” came to be seen as discriminatory and out of touch. The people most hurt along the way were those whom A&F’s leadership chose to exclude – racial minorities denied jobs, young women shamed for their bodies, individuals whose sense of self-worth took a hit from not “belonging” in the A&F world. In the end, Abercrombie paid the price in lawsuits, lost customers, and a near-collapse of the business.
Yet, Abercrombie & Fitch’s ongoing reinvention also demonstrates that change is possible, if not always easy. The company has begun rebuilding trust by doing what it should have done all along: embracing inclusion as part of its brand identity. As explored further in the IADS White Paper DEI at a crossroads in retail, Abercrombie & Fitch is not an isolated case; it sits alongside other global retail examples that show how progress on DEI can stall, reverse, or regain momentum depending on leadership focus and sustained commitment. Inclusion and diversity are not antithetical to a cool brand – they are the new currency of cool. A&F’s fall and rise underline a broader truth: in today’s world, the brands that thrive will be those that make everyone feel like they belong. Abercrombie & Fitch had to learn this through failure, but others can heed the lesson upfront – exclusivity might sell cologne and T-shirts for a season, but inclusion sells longevity.
Credits: IADS (Maya Sankoh)
IADS Exclusive: Zara, competitor, benchmark or mirror for department store?
IADS Exclusive: Zara, competitor, benchmark or mirror for department store?
CLICK HERE TO SEE PHOTOS OF ZARA BOUTIQUES!
Zara is, by any measure, the archetype of fast fashion. No other brand has done more to define the model: rapid design cycles, vertically integrated supply chains, relentless store expansion. The parent company, Inditex, is valued among Europe’s most capitalised corporations.
Yet something has shifted. Over the past five years, Zara has been reinventing what its stores look and feel like, how they operate, and what they aspire to be. Flagship after flagship, the brand has moved toward larger, locally rooted, experientially rich formats that blur the line between monobrand retail and something that looks remarkably like a department store. The prices remain accessible; the ambition does not.
As the recent flagship openings documented by Newstores, IADS’ retail observation partner, illustrate, this evolution deserves more than a passing glance from department store leaders. Zara is not merely a competitor occupying adjacent real estate in prime urban locations. It is, arguably, the most disciplined and best-capitalised retailer currently converging on the department store’s own territory — in format, in positioning, and in the role it seeks to play in cities. Understanding how it got there, and where it is heading, is not an exercise in competitive anxiety. It is an opportunity to ask what department stores can learn, where they must differentiate, and what they should refuse to concede.
How Zara became a global retail powerhouse
The story began in 1963, when Amancio Ortega, then a delivery boy, founded Confecciones GOA in La Coruña to manufacture women’s bathrobes and lingerie for local retailers, by copying popular designs and selling them at accessible prices. The pivot came in 1975 when a customer cancelled a large order, forcing Ortega to open a store to sell the stock himself.
The inaugural collection featured white blouses and shirts inspired by American preppy style, marketed as fashionable “high-end lookalikes” at prices ordinary Spaniards could afford. The business model was new: Ortega controlled everything from design to retail, eliminating intermediaries. Success came quickly. By 1983, there were nine Zara stores across Spain, and in 1984 the company opened a logistics centre near La Coruña, enabling frequent, small, just-in-time deliveries to stores.
In 1985, Ortega formalised this growing empire by creating Inditex (Industria de Diseño Textil) as the holding company for all operations, built on rapid fashion cycles, tight supply-chain control, and the ability to test, learn, and iterate fast. The brand portfolio expanded through the acquisition or launch of Pull&Bear (1991), Massimo Dutti (1991–94), and Bershka (1998). Yet Zara remained the volume driver and image engine of the group, growing internationally: Portugal in 1988, New York in 1989, Paris in 1990, as a prelude to broader European expansion in the 1990s and Mexico City (1992). By the decade’s end, Zara had entered the Middle East, Latin America, Turkey and Japan, reaching approximately 1,000 retail locations.
In 2001, Inditex listed on the Spanish stock exchange at a valuation of €9 billion; shares surged on the first day, making Ortega Spain’s richest person overnight. The listing funded aggressive growth strategy in Asia, and by 2009, Zara operated in 69 countries, with a store count surpassing 2,000.
By then, Zara had become synonymous with fast fashion itself: global scale, twice-weekly store deliveries, lead times of just a few weeks from design to the shop floor, and a distinctive sourcing strategy. While competitors moved production entirely to Asia for cost savings, Zara maintained approximately 50% of production in “proximity markets”—Spain, Portugal, Morocco, and Turkey—for trendy, fast-turning items, reserving Asian production for basics with longer lead times. This dual-speed supply chain allowed Zara to react to emerging trends mid-season while competitors were locked into collections planned six months in advance.
Operational sophistication went hand in hand with technology. From 2013 to 2015, Zara implemented RFID tagging across its entire network, enabling individual garment tracking, improved stock visibility, click-and-collect services and self-checkout. E-commerce launched in 2010 in six European markets with a deliberately simple interface. A mobile app followed shortly after, and by 2013, online sales had expanded to 106 countries. Today, e-commerce is available in 200 markets through the website, app or partners. At the group level, online accounts for more than a quarter of total sales, with 218 million active app users, 8.1 billion annual visits, and 257 million social media followers — Zara being the primary driver of engagement.
In 2011, Amancio Ortega stepped down as CEO, handing the reins to Pablo Isla. Under his leadership, Inditex reached its peak store count in 2019 with 2,139 locations. The COVID-19 pandemic hit hard: sales fell 44% year-on-year, resulting in a €409 million net loss as store closures were not offset by a 50% surge in online sales in Q1 (however, the company posted a total €1.1 bn net profit for the full year 2020). Inditex responded with massive investment — approximately €2.7 billion in technology and store integration — while earmarking 600+ stores for closure between 2020 and 2024 in China, Spain, France and Germany. The philosophy shifted from maximising store count to a “fewer, larger, better” flagship strategy.
In 2021, Óscar García Maceiras succeeded Isla as CEO, and in 2022, Marta Ortega Pérez—the founder’s daughter—became Non-Executive Chair. Under her influence, Zara began repositioning toward a more premium, “fashion house” identity rather than pure fast-fashion volume play. This translated into price increases in 2023 (without significant customer defection—a sharp contrast to struggles faced by competitors like H&M and Uniqlo with similar moves), designer collaborations (Stefano Pilati, Ludovic de Saint Sernin, Narciso Rodríguez), and a new visual language through the works of fashion photographers like Steven Meisel and Mario Sorrenti. Curation and quality took precedence over sheer speed and volume.
Brand extensions accompanied this repositioning. Zara Beauty launched in May 2021 and expanded into hair care by 2025. Zara Pre-Owned debuted in 2022, offering repair, resale, and donation services as part of sustainability initiatives aimed at luring younger consumers.
Technology investments continued to transform operations — soft-tag RFID now deployed in 100% of stores (and set to cover 90% of products across all formats by Spring/Summer 2026), AI-driven demand forecasting and trend detection, logistics automation and a major new distribution centre near Zaragoza scheduled to open in mid-2026. Online, Zara has introduced an AI-based virtual fitting tool (”Zara Try-on”) that allows customers to generate a synthetic avatar from their own photos and see it wearing real products — already deployed in 43 markets with over 7 million sessions since launch in late 2025. But the most visible changes were in the flagship stores themselves, which became laboratories for customer experience innovation. The Manchester Trafford Centre store (3,200+ sqm) featured automated sorters, assisted checkouts and in-store repair booking. The expanded Hudson Yards location in Manhattan (2,200 sqm) and the Nanjing flagship (2,500+ sqm) showcased Zacaffè — Zara’s in-store café concept — alongside “Fit Check” smart mirrors and apparel vending machines. The Osaka store (2,040 sqm, the 64th in Japan) demonstrated that even in mature markets, Zara saw value in enhanced physical experiences.
Zara stores today: why they matter to department stores
The brand remains the crown jewel of the Inditex group, which also operates Pull&Bear, Massimo Dutti, Bershka, Stradivarius, Oysho. Under the group’s current reporting structure, Zara, Zara Home and Lefties together generated €28.1 billion in FY2025 (year ending January 2026, and up from €27,8 billion in 2024), representing 70% of Inditex’s total revenue of €39.9 billion. As of January 2026, Zara operates 1,500 stores globally — down from 1,550 a year earlier — while total selling space for the Zara cluster grew to 3.18 million sq m (+1.3%), confirming the “fewer, larger, better” thesis. At the group level, gross space increased 5.3% in the year, and the financial trajectory continues to strengthen.
The newest stores are organised into semi-independent sections — women, men, kids, fragrances, Zara Origins, Zara Athleticz — each with its own visual identity but unified by a coherent overall architecture. Technology is embedded throughout: RFID-enabled inventory, interactive fitting-room mirrors, self-checkout, and dedicated areas for online pickup and returns. Each store acts as a mini fulfilment hub, raising complexity in labour planning, backroom capacity and service design.
Flagships aim to become destinations. Experiential elements — cafés, immersive displays — blend retail, hospitality and services. They are increasingly referred to as “monobrand department stores” due to their size and scope. Meanwhile, peripheral or smaller stores, especially in mature European markets, continue to be consolidated in favour of productivity per square metre over maximum coverage.
Zara’s store fleet is converging toward a smaller number of highly invested flagship “magnets”, often in the same urban nodes as department stores, competing for fashion traffic while potentially driving broader footfall to premium retail districts. Fully integrated into the digital ecosystem through their fulfilment and experience capabilities, these flagships also serve as physical engagement funnels for Zara’s online business.
Department store leaders can therefore view Zara both as a competitor and as a benchmark: a vertically integrated, data-rich fashion machine that is deliberately reducing its physical footprint while upgrading every remaining location into a highly choreographed, omnichannel-enabled flagship. Like department stores, Zara is seeking to escape the Shein/Temu low-price race by moving upmarket without alienating its core customers — through improved brand image, upgraded store concepts and elevated décor.
What recent flagship openings reveal: four signals for department stores
Between 2024 and 2026, IADS’ partner Newstores documented a series of notable Zara openings and relocations across Europe and Japan, including the expansion of the standalone Zara Man format — now in its fourth location. Taken individually, each is a well-executed store. Taken together, they tell a far more consequential story: Zara is methodically building the capabilities, aesthetics, and spatial logic that have historically been the preserve of department stores. Four patterns stand out.
The “rooms” logic: a monobrand department store in all but name
Walk into the relocated Zara in Manchester’s Trafford Centre (3,000+ sq m on a single floor) or the new Leeds flagship (4,300 sq m across three floors) and the layout is immediately striking: instead of one continuous selling floor, the space is broken into a sequence of distinct rooms — a baby boutique here, an accessories and handbags shop-in-shop there, each with its own visual register. Newstores’ John Ryan described the Trafford store as “a mall within a mall“. The same principle is at work in Yokohama, where the relocated 2,000 sq m store is organised as a series of boutique-style rooms, with tonal and lighting shifts demarcating womenswear, menswear and younger fashion. Even the more compact standalone Zara Man formats follow this grammar: the recently opened 700 sq m Berlin store in the Mall of Berlin — the fourth standalone Zara Man after Osaka, Rome and South Coast Plaza — is designed as a series of linked rooms across two floors, with Zara Athleticz given its own separate entrance from the mall.
This is, of course, the foundational spatial grammar of the department store: curated worlds under one roof, each with its own identity, connected by a coherent architectural envelope. Zara is now applying it — at scale, under a single brand — in the very retail districts where department stores operate.
Local roots as a premium signal
One of the most striking shifts in recent Zara flagships is the deliberate rejection of a standardised global format in favour of deep contextual anchoring.
In Lisbon, the 5,000 sq m store occupying an entire block on Rossio Square preserves the character of the original building, lending the interior — especially the Zara Home floor — a distinctly Portuguese domestic atmosphere35. The in-store café is a partnership with a local pastéis de nata atelier: a reference that no global playbook could have prescribed. In Madrid, the reopened Calle Serrano flagship deploys an interpretation of Castilian architecture — exposed brick, reclaimed wood, iron and ceramics — with a graduated lighting scheme (darker below, brighter above) that choreographs the vertical journey through the building. The fourth floor hosts “El Apartamento”, a 400 sq m space designed as a curated domestic setting blending Zara Home and clothing36.
In Japan, Zara goes further still. The Osaka Zara Man store wraps its façade in burnt cedar, furnishes the interior with Sunuke wood and antique Japanese chairs, and includes a “Listening Room” where customers can sit and listen to music from custom-designed speakers37. In Barcelona, the new Diagonal flagship — designed with Vincent Van Duysen — inhabits one of the avenue’s traditional buildings, using brushed metal, natural wood, soft stone and exposed timber beams to create what Newstores calls “a restrained sense of luxury“ at mid-market prices38.
For department store leaders, the parallel is direct: the ability to be of a city, not just in it, has long been a defining advantage of the format — think Harrods in London, Le Bon Marché in Paris, or Isetan in Tokyo Shinjuku. Zara is now investing heavily in precisely that kind of local resonance, store by store.
Luxury codes at mid-market prices
Barcelona’s Diagonal flagship raises a question that should preoccupy every department store CEO positioning in the premium segment. As Newstores pointedly observed: what can mid-market competitors be doing when their interiors begin to match — or surpass — those of luxury merchants?
The Madrid Serrano store is explicitly designed to feel like it “fringes on luxury“, a deliberate departure from Zara’s familiar cream-and-brushed-metal aesthetic. In Osaka, the Zara Man store uses Spanish artworks, sculpture and a vintage motorcycle as props — the visual vocabulary of a concept boutique, not a volume retailer. In Berlin, the new standalone Zara Man deploys a palette of black, steel and plain light wood under a blacked-out open ceiling, with a sculptural matt-black staircase linking the two floors — a deliberately minimalist environment in which a restrained number of garments are on display, reinforcing the sense of curation over volume. In Barcelona, the Van Duysen collaboration produces an interior of such restraint and material quality that, absent the price tags, it could pass for a high-end maison.
This is the tangible translation of Marta Ortega’s repositioning: designer collaborations, fashion-house photography, controlled price increases absorbed without meaningful customer defection. The flagships are where the strategy becomes tangible. And for department stores that compete on curation, environment and brand elevation, the gap is narrowing — not because department stores are declining, but because Zara is ascending.
The store as omnichannel infrastructure
Beneath the design ambition, these flagships are also logistical machines. In Yokohama, customers can scan items to check in-store availability, use digital readers to locate products on the floor, and pick up online orders from a robotic pickup point. In Manchester’s Trafford Centre, 20 “assisted checkout” desks replace conventional tills entirely, with contactless payment as the default39. These are not add-ons, they are structural to the store concept.
Combined with RFID-tagged inventory, ship-from-store capabilities, and dedicated online pickup and return zones, each flagship operates as a fulfilment hub that also serves as a beautifully designed retail space. This dual function — experience venue and logistics node — is one that department stores have been pursuing for years, but that Zara now executes with the advantage of vertical integration and a single-brand product architecture that radically simplifies operations.
For department stores: competitor, benchmark, or mirror?
The conventional framing positions Zara as a competitor to department stores. It occupies the same prime urban locations, targets overlapping customer segments, and increasingly deploys the same tools: curated environments, local architectural identity, hospitality elements, omnichannel fulfilment. In cities like Manchester, Madrid, Barcelona, or Osaka, Zara flagships now sit next door to — and sometimes outperform — department stores in terms of design ambition, technological sophistication, and footfall. The competitive overlap is real and growing.
Yet the more instructive lens may be that of the benchmark. Zara’s trajectory over the past five years offers department store leaders something rarer and more valuable than a threat assessment: a live case study in strategic reinvention under pressure.
What department stores can learn
Faced with the twin squeeze of ultra-fast-fashion platforms undercutting on price and speed, and a post-pandemic consumer expecting more from physical retail, Zara did not retreat into either discount volume or digital-only efficiency. Instead, it made a series of decisions that department store CEOs will recognise as familiar ambitions — but that Zara executed with a speed, coherence and capital commitment that few multibrand retailers have matched:
- It shrank to grow: From a peak of 2,139 stores in 2019 to 1,500 in 2026, Zara closed over 600 locations while increasing total commercial space. Every closure funded a larger, better-positioned flagship. Department stores have been debating portfolio rationalisation for years; Zara did it, absorbing the short-term pain and emerging with a more productive, more investable estate.
- It moved upmarket without losing its base: Price increases in 2023, designer collaborations, fashion-house photography, new store concepts — all signalled a deliberate premiumisation. Yet customer defection remained minimal because the repositioning was grounded in tangible improvements to product and experience, not mere aspiration, and simultaneously customers can still shop access price items. Department stores attempting similar moves — elevating private labels, introducing premium services, curating more selectively — often struggle with the execution gap between intention and perception. Zara closed it.
- It made technology invisible: RFID, AI-driven demand forecasting, robotic pick-up, assisted checkouts, in-store product locators — the technological stack in a Zara flagship is formidable. But none of it is presented as innovation theatre. It simply works, quietly, in the background of a beautifully designed space. This stands in contrast to some department store technology investments, where digital screens and interactive installations can feel bolted on rather than woven in.
- It turned stores into stories: The burnt cedar façade in Osaka, the pastéis de nata café in Lisbon, the “Apartamento” in Madrid, the Listening Room — these are not gimmicks. They are narrative devices that give each flagship a reason to exist beyond product distribution. They create memory, talkability, and a sense of place. They make the store worth visiting even when customers have no purchase intent — precisely the dynamic that drives discovery, conversion, and loyalty over time.
However, if Zara is a benchmark, it is a bounded one — and understanding its limits is essential for department stores defining their own strategic space.
The limits of the comparison
Zara is, and will remain, a monobrand operator. However skilfully it fragments its offer into “rooms”, collections and sub-brands (Origins, Athleticz, Beauty), the customer walks in knowing they are in a Zara store. The department store’s foundational proposition — the ability to juxtapose dozens of brands, price points and product categories under editorial curation — is structurally unavailable to Zara. This is not a marginal advantage. It is the reason a customer can walk into a department store looking for a fragrance and leave with a coat: the serendipity of adjacency, the productive collision of worlds that no monobrand environment can replicate.
Zara cannot broker trust across categories in the way a department store can. When a department store introduces a new beauty brand, endorses an emerging designer or curates a homeware edit, it lends its accumulated credibility to that selection. It acts as filter, guarantor and tastemaker. Zara can curate within its own universe, but it cannot play this intermediary role across the broader market. In an era of infinite online choice and eroding consumer trust, this curatorial authority — if actively exercised — remains a powerful differentiator.
Zara’s experiential ambitions are constrained by its economics. A café, a listening room, a curated apartment — these are meaningful gestures within a Zara flagship, but they are secondary to the core business of moving product at scale through fast-turning inventory. Zara’s gross margins (59.7%) are built on volume, speed and vertical integration. Every square metre devoted to non-selling experience is a square metre that must be justified against that model. Department stores, by contrast, have historically operated as platforms where experiences — restaurants, spas, cultural programming, personal services, events — can coexist with and reinforce commercial activity. The format is structurally better suited to deep experiential investment.
Zara cannot serve as a community anchor the way a department store can. A Zara flagship, however beautiful, is a retail destination. A department store, at its best, is a civic institution: a place where a city meets itself, where cultural programming, dining, services and commerce intertwine to create something irreplaceable in the urban fabric. This dimension — part public space, part commercial enterprise, part cultural venue — is the department store’s deepest moat, and it is one that no monobrand retailer, however ambitious, can credibly claim.
Conclusion: the experience trap
The fact that Zara’s most ambitious stores are increasingly described as “monobrand department stores” should be read as both a compliment and a warning to the sector. A compliment, because it confirms that the department store model — multi-world, experiential, locally rooted, service-rich — remains the aspirational template for physical retail at scale. Yet it is also a warning: if a vertically integrated group with €11.0 billion in net cash, €6.2 billion in annual net income, a 58.3% gross margin and €10.7 billion in online sales is converging on your format, the bar for execution is rising fast.
The logical response would be to invest even more heavily in experience as a differentiator. Yet this leads to an uncomfortable question: at what point does a department store risk becoming a destination people visit but do not buy from?
If every investment dollar flows toward restaurants, cultural programming, wellness services, co-working spaces and immersive installations — and away from the hard work of product curation, buying excellence, brand exclusivity and commercial edge — the department store may end up as a beautifully curated food hall with a diminishing fashion floor attached. The footfall metrics will look healthy. The conversion metrics will not.
This is not a theoretical risk. Some department store companies have seen experiential investments drive significant increases in traffic and dwell time, without proportional gains in product sales. The experience becomes the product — and the actual product becomes an afterthought.
The antidote is not to retreat from experience, but to insist that experience and commerce remain structurally linked. The most effective department store innovations of recent years share a common trait: they make the act of buying better, not separate from the visit. A personal styling service that ends with a curated selection ready to try. A restaurant on the fashion floor, not in a separate building. A beauty counter where the consultation is the experience and the purchase is its natural conclusion. A homeware floor designed as a series of shoppable rooms — not unlike, in fact, what Zara Home does in Lisbon.
Department stores do not need to become Zara. They cannot, and should not. But they must match Zara’s discipline in portfolio rationalisation, its rigour in technology integration, its boldness in premiumisation, and its instinct for making every store feel inevitable in its city. And they must do all of this while leveraging the one thing Zara can never replicate: the power of being a platform — for brands, for experiences, for communities, and for the irreplaceable serendipity of walking in for one thing and discovering another.
The only question is whether the sector will invest in this with the same conviction that Zara invests in its own.
Credits: IADS (Selvane Mohandas du Ménil)
IADS Exclusive - A landmark entry: Galeries Lafayette and the evolution of Indian luxury retail
IADS Exclusive - A landmark entry: Galeries Lafayette and the evolution of Indian luxury retail
CLICK HERE TO SEE PHOTOS OF GALERIES LAFAYETTE MUMBAI
Galeries Lafayette’s first Indian flagship store opened in the Kalaghoda district in Mumbai, at the historic Turner Morrison and Voltas House buildings. Indian shoppers were already among the top international clients at Galeries Lafayette’s Paris Haussmann flagship, with India’s luxury market projected to reach USD 85 billion by 2030[1].
Income inequality in India is stark and ever-increasing, resulting in a nascent luxury segment while mass-market retailers are squeezed. Mumbai, home to over 450 billionaires and 142,000 millionaires[2], and the cultural and financial capital of the country, was the logical entry point for Galeries Lafayette.
Despite a later-than-planned opening due to the complexity of restoring heritage buildings, the Mumbai opening of Galeries Lafayette marks India’s first true luxury department store. It results from a seven-year ambition and partnership announced in November 2022 between Galeries Lafayette Group (Paris) and Aditya Birla Fashion and Retail Limited (ABFRL), the fashion arm of India's Aditya Birla Group conglomerate. The deal was structured as a 20-year exclusive franchise agreement, giving ABFRL the sole rights to operate Galeries Lafayette stores across India. Strategic advisory firm Pike Preston served as the deal's advisor on record. The next planned store opening is in Delhi in 2027.
Beyond being a commercial retail space, this opening represents an extension of French cultural diplomacy and is part of strategic and geopolitical cooperation between France and India. By integrating local architectural heritage and hosting joint Franco-Indian initiatives, Galeries Lafayette Mumbai serves as a symbol of deepening cultural ties between the two nations.
India’s luxury market and competitive context
The Indian luxury sector has entered a period of structurally accelerating growth with the personal luxury goods (fashion, accessories, watches, beauty) segment being valued at $10.6 billion[3]. Bain and Altagamma’s 2025 report highlighted a shift in luxury retail, in which the Middle East, Latin America, Southeast Asia, India, and Africa combined represent a market value of around €45 billion in 2025, matching Mainland China in scale.
The competitive narrative in India's luxury retail market has been framed as ‘Ambanis vs. Birlas’. Reliance Brands Limited (RBL), owned by the Ambani family, manages a portfolio of 90+ brands, including Balenciaga, Bottega Veneta, Versace, Jimmy Choo, Valentino, Tiffany & Co., Burberry, and Ferragamo. It absorbed Genesis Luxury, the original broker that brought Western luxury to India, and operates Jio World Plaza, the country's most advanced luxury mall, located in Mumbai. Its digital arm, AJIO Luxe, extends brand access nationally. In January 2025, RBL also secured the franchise for Saks Fifth Avenue in India.
Aditya Birla Group built its luxury presence through The Collective (India’s original multi-brand luxury store with 12 locations and 85 brands) and through equity stakes in Indian designers, including Sabyasachi, Tarun Tahiliani, and Shantnu & Nikhil. It now operates Galeries Lafayette Mumbai, India’s first multi-brand department store model with over 250 brands in a luxury South Mumbai heritage location and plans to open a location in Delhi by 2027.
Tata Group defines Indian luxury hospitality through Taj hotels and operates Tata CLiQ Luxury, India’s leading digital luxury marketplace.
Further to this, India faces a key structural constraint: a lack of luxury malls. India has precisely three genuine luxury malls: DLF Emporio (Delhi), DLF The Chanakya (Delhi), and Jio World Plaza (Mumbai). In March 2026, DLF’s head of luxury retail reported zero availability despite 15 top-tier brands ready to enter immediately. DLF Emporio’s planned expansion (doubling to 320,000 sq ft) will not be ready until the end of 2028. This bottleneck is a significant constraint on the speed at which the market can absorb demand — and it is one reason the Galeries Lafayette location strategy (a standalone heritage building rather than a mall) is particularly notable.
Architectural localisation and Franco-Indian programming
Galeries Lafayette’s Mumbai store is located in the heart of Kalaghoda, one of Mumbai's most culturally and architecturally significant districts, neighbouring flagships for Hermès, Christian Louboutin, and Sabyasachi. The store spans 90,000 sq ft (approximately 8,400–9,000 sqm) across five floors, plus a dedicated basement Beauty Hall. The ground floor is dedicated to leather goods and accessories, with luxury womenswear on the first floor, contemporary womenswear on the second, menswear and tailoring on the third, and streetwear and concept retail on the fourth. The rooftop terraces of both buildings are earmarked for future dining offerings.
Architecturally unique, the store spans two restored century-old heritage structures — the Turner Morrison Building (a colonial-era, arched neoclassical building originally built for a British trading company) and Voltas House (a mid-century modernist post-independence industrial building) — which have been physically interconnected through a new architectural insertion. This is one of India's first major façade-retaining renovation projects.
The store was designed by Virgile + Partners, blending Parisian and Indian design motifs. The result is a distinctive retail interior; key design features include a life-size Cupola inspired by the French observation balloon L'Intrépide (1796), which floods the central atrium with natural light, an elliptical ‘Jardin de Paris’ staircase with hand-embroidered wallpaper created by Indian artisans and lotus-motif parchinkari stone inlay at the ground-floor entrance, inspired by the Taj Mahal’s craftsmanship. Three Indian artists, Sheehij Kaul, Reshidev RK, and Aashika & Tanishaa Cunha (from Plane Crazy Studios) were commissioned for permanent in-store works.
Beyond retail, the store has positioned itself as a cultural destination bridging France and India. Starting in November 2025, Galeries Lafayette Mumbai displayed rotating art installations, live activations and pop-up shows.
In February this year, the store also hosted a flagship event for the India-France Year of Innovation 2026, attended by two French government ministers (Roland Lescure, Minister of Economy, and Éléonore Caroit, Minister Delegate for Europe) and featured a collaboration with contemporary Indian artist Ankon Mitra. During the same time, Galeries Lafayette Mumbai participated in the India Design ID 2026 fair in New Delhi (the second edition of ‘Art de Vivre à la française’), reinforcing its cultural presence ahead of the planned Delhi store.
Brand selection and specialised services
The pace of brands’ market entry in India has accelerated dramatically. 27 new international brands entered India in 2024 (nearly double the 14 in 2023), with 56% from EMEA, led by France and Italy. 2025 entries include Messika (via The Chanakya), Chanel Beauty on Nykaa, Stella McCartney (via RBL), Maje (Jio World Drive, via RBL), and Kilian Paris. French luxury group SMCP (Sandro, Maje, Claudie Pierlot) entered via Reliance in 2023, with its first Sandro store opening in Mumbai in January 2025. The 2026 pipeline includes Lululemon (via Tata CLiQ), Abercrombie & Fitch/Hollister (via Myntra), and Off-White.
Indian designer labels are closing the revenue gap with global players at a striking pace. By Fiscal Year 2025, Sabyasachi reached ~INR 500 crore in revenue, Tarun Tahiliani ~INR 350 crore, and Manish Malhotra INR 308 crore, exceeding Gucci India (INR 265 crore and down 17% YoY) and Christian Dior India (INR 257 crore and down 3% YoY)[4].
At opening, Galeries Lafayette Mumbai carried over 250 brands with approximately 70% of the assortment exclusive to India, and 200 brands entering Indian retail for the first time. Notable India-firsts include Coperni, Patou, Marni, Valextra, Diptyque, and Parfums de Marly. Indian designers confirmed at launched included Bodice (Ruchika Sachdeva), Dhruv Kapoor, Almost Gods, Hemant & Nandita, Rococo Sand, Verandah (Anjali Patel Mehta), Chorus (by Chanakya atelier), Misho (jewellery), Deepa Gurnani (jewellery), plus Sabyasachi and Tarun Tahiliani[5].
Services offered at the store include personal styling and personal shopping appointments, private reception lounges and VIP client spaces, in-store concierge services, and seasonal cultural programming and live activations. It will also offer special wedding-season services, a key focus given India’s luxury wedding market and valet parking services, catering to Mumbai’s car-travel culture.
Cultural dynamics and the Indian luxury consumer
The purchasing behaviour of Indian luxury consumers is heavily influenced by cultural traditions and a growing appetite for experiences. The $50 billion Indian wedding market is a primary catalyst, driving over half of all gold jewellery sales and prompting large-ticket spending across fashion and hospitality. For these key celebratory occasions, consumers show strong cultural loyalty to homegrown designers like Sabyasachi and Tarun Tahiliani, whose revenues now rival or surpass major European fashion houses operating in India.
Geographically and digitally, the Indian luxury consumer is also evolving. While Mumbai and Delhi-NCR remain crucial hubs, luxury consumption in non-metro cities is booming, driving over 50% of all luxury e-commerce sales. Automobiles constitute the largest and fastest-growing luxury category in India[6]. Within personal luxury goods, watches and jewellery dominate the category, alongside a rapidly growing beauty segment.
However, domestic luxury shopping faces a structural hurdle: high import duties and a 28% Goods and Services Tax mean luxury goods can cost up to 40% more than in markets like Dubai, leading many wealthy Indians to systematically shop abroad. The India-EU and India-EFTA trade deals are the first policy changes in decades to address this directly. Galeries Lafayette’s response is to align pricing with Dubai levels where possible.
For those shopping domestically, especially newer entrants climbing the luxury ladder, Galeries Lafayette can act as an accessible premiumisation gateway, offering a less intimidating experience than mono-brand boutiques. During the launch, Galeries Lafayette’s international development director Philippe Pedone also acknowledged that more local brands would be added.
Galeries Lafayette’s Indian market roadmap
Galeries Lafayette’s entry into Mumbai marks the group’s strategic pivot away from competitive Western markets (highlighted by the July 2024 closure of its Berlin store) and toward high-growth regions like Asia and the Middle East[7]. With a global ambition to increase international revenue from 10% pre-pandemic to 25% by 2030, India sits at the core of this strategy alongside markets like Dubai, Doha, and Macau. The immediate next phase for the Mumbai flagship involves completing its experiential offerings. While food and beverage concepts were not operational at the November 2025 launch, CEO Arthur Lemoine confirmed that rooftop dining will launch in 2026, with the Parisian dining concept La Cantine du Faubourg in advanced talks for the space.
Beyond the Mumbai flagship, Galeries Lafayette’s roadmap in India relies on both physical footprint expansion and digital penetration. A second flagship store in New Delhi, spanning approximately 5,500 square meters within the DLF Emporio complex, is now targeted for 2027 following developer timeline delays. To capture the growing wealth and demand outside major metro areas, the brand also plans to launch a dedicated e-commerce platform aimed at consumers in Tier-2 and Tier-3 cities.
Ultimately, the long-term success of this expansion will lean on its partnerships. By leveraging Aditya Birla Group’s deep connections with homegrown brands and continuing to act as a conduit for Indian-French cultural diplomacy, Galeries Lafayette is positioning itself not just as a foreign retailer but as a deeply integrated platform bridging global luxury with India’s evolving consumer landscape.
Credits: Anchita Ranka
[1] Galeries Lafayette to open its first store in India amid luxury boom
[2]Hurun-India Wealth Report 2025
[3] India Luxury Goods Market Size, Share, Trends and Forecast by Product Type, Distribution Channel, End User and Region, 2026-2034
[4] Indian luxury brands close revenue gap with global players in FY25: Rediffusion report
[5] Galeries Lafayette Bows in Mumbai, a Major Step for Retail in India
[6] Experiential luxury, cars and beauty driving Indian luxury market
[7] ‘The timing is finally right’: Galeries Lafayette arrives in India
