
Articles & Reports

Can Saks Global overcome its missteps and recover in 2026?
Can Saks Global overcome its missteps and recover in 2026?
What: Saks Global faces leadership upheaval and imminent bankruptcy as debt, vendor disputes, and declining sales threaten its future.
Why it is important: The company’s struggles highlight how weak vendor relations and financial missteps can rapidly erode even the most established retail brands, as seen in recent industry analyses.
Saks Global’s position as a leading luxury retail conglomerate is under severe threat, with the company experiencing significant leadership turnover and reportedly preparing for bankruptcy. Despite attempts to boost profitability through high-profile acquisitions, cost-cutting, and partnerships, Saks Global’s revenue has fallen sharply, and its debt load has become unsustainable. The acquisition of Neiman Marcus, financed by substantial borrowing, compounded existing financial pressures and led to widespread vendor payment delays, resulting in lawsuits and a loss of supplier trust. These operational failures have contributed to inventory shortages and a diminished customer experience, further weakening the brand’s market relevance. Analysts point to a lack of focus on retail fundamentals—such as curation, exclusivity, and service—as a key factor in Saks Global’s decline. The company’s predicament serves as a cautionary tale for the luxury sector, demonstrating how financial mismanagement and poor vendor relations can undermine even the most storied retail institutions.
IADS Notes: In January 2026, The Guardian reported on Saks Global’s leadership changes and imminent bankruptcy, reflecting deep challenges in the luxury department store sector. Retail Dive in December 2025 highlighted the company’s ongoing debt, inventory shortages, and declining sales, while WWD detailed the operational and reputational risks stemming from vendor payment delays and lawsuits. Financial Times in August 2025 discussed the impact of Saks’ acquisition debt and creditor negotiations, and Inside Retail in August 2025 examined the broader implications of layoffs, restructuring, and the urgent need for renewed brand differentiation.
Can Saks Global overcome its missteps and recover in 2026?

Forrester’s 2026 predictions for the payment industry
Forrester’s 2026 predictions for the payment industry
What: Retailers and payment providers are adapting to a new era of AI-assisted payments, niche stablecoin adoption, and enhanced biometric authentication, preparing for broader transformation in the years ahead.
Why it is important: This shift highlights the need for retailers to proactively invest in payment innovation and security, ensuring resilience and consumer trust as the payments landscape evolves.
The payments sector in 2026 is entering a phase of steady, foundational change, as retailers and payment providers embrace AI-assisted transactions, experiment with stablecoins in niche applications, and deploy advanced biometric authentication to combat fraud. While fully autonomous, agentic payments are gaining traction in B2B workflows, most consumer-facing innovations remain “human-in-the-loop,” reflecting ongoing concerns around trust, consent, and user experience. Stablecoins, despite their promise of faster and cheaper transactions, continue to face adoption barriers in mainstream retail, finding their strongest foothold in cross-border B2B payments and crypto-native segments. Meanwhile, biometric solutions are evolving rapidly, with deepfake detection and liveness checks becoming standard to address emerging security threats. As the industry navigates these shifts, leaders who invest early in secure, flexible payment infrastructure and educate both staff and consumers about new risks will be best positioned to capitalize on the broader transformation expected in the coming years.
IADS Notes: The payments landscape in 2026 is undergoing a fundamental transformation, as confirmed by recent IADS sources. BCG’s Global Payments Report (September 2025) highlights the convergence of stablecoins, agentic AI, and real-time payments as key drivers reshaping retail operations, with major retailers adopting stablecoins for near-zero transaction fees and leveraging agentic AI to automate e-commerce and payment workflows. Visa’s May 2025 announcement of its Intelligent Commerce initiative and Mastercard’s Agent Pay program both signal a shift toward AI-powered, agentic payment solutions, establishing new protocols for security, transparency, and consumer control. Journal du Net’s January 2025 analysis details the evolution of payment terminals into multifunctional, AI-driven tools with enhanced security and biometric authentication, while a16z’s January and October 2025 reports confirm the mainstreaming of stablecoins and blockchain infrastructure, with department stores and major platforms integrating crypto products for faster, cheaper, and more accessible transactions. McKinsey and Journal du Net (September–November 2025) further document the rise of agentic commerce, where AI agents automate shopping journeys and payments, shifting power from traditional retailers to digital intermediaries and tech giants. Collectively, these sources underscore the need for retailers to adapt to a rapidly evolving payments ecosystem, balancing innovation in AI, security, and digital currencies with the imperative to build trust, transparency, and operational resilience.
Forrester's 2026 predictions for the payment industry
Click here for Forrester’s complimentary Prediction guides for 2026
Resale market 2026: From thrift to retail’s next growth engine
Resale market 2026: From thrift to retail’s next growth engine
What: The resale market is emerging as a primary growth engine for retail, driven by consumer demand for thrift, sustainability, and innovation.
Why it is important: The rise of resale highlights the growing influence of circular economy models and consumer demand for responsible retail.
The resale market is rapidly evolving from a niche segment into a central force in retail’s growth trajectory, propelled by shifting consumer values around thrift, sustainability, and innovation. As more shoppers prioritise environmental responsibility and affordability, retailers are responding by integrating resale platforms and circular economy strategies into their core business models. This transformation is not only attracting new investments and partnerships but also prompting established brands to rethink inventory management, customer engagement, and brand positioning. Technology is playing a pivotal role, with AI-driven curation and digital authentication enhancing trust and operational efficiency. The sector’s expansion is further evidenced by the strong performance of leading resale platforms and the increasing adoption of loyalty programs and digital certificates. These developments are fundamentally reshaping the retail landscape, making resale a mainstream, profitable, and trusted channel that appeals to a broad spectrum of consumers. As regulatory and societal pressures for sustainability intensify, the resale market’s influence on retail strategy and growth is set to deepen further.
IADS Notes: The rise of the resale market as a retail growth engine is substantiated by several key developments reported in 2025. In January 2025, WWD highlighted the expansion of The RealReal and Nuuly, underscoring the sector’s increasing viability. The Economist, in March 2025, reported the global second-hand fashion market reaching $100 billion, while The Retail Bulletin examined the adoption of circular economy strategies in retail. October 2025 saw Journal du Net detail how brands are using technology and loyalty programmes to build trust and profitability in the second-hand market, and BoF described the shift toward curated, AI-driven experiences on online resale platforms.
Resale market 2026: From thrift to retail’s next growth engine
Beyond Amazon: The coming recalibration of work, education, skills, and careers
Beyond Amazon: The coming recalibration of work, education, skills, and careers
What: AI and automation are rapidly transforming workforce structures, skill requirements, and career paths.
Why it is important: The transformation reflects a broader trend toward skills-based organizations, emphasizing adaptability and human-machine collaboration.
AI and automation are fundamentally altering the landscape of work, accelerating changes in workforce structures, required skills, and career trajectories. As automation extends beyond traditional factory settings into areas such as analysis, management, and decision-making, organizations are compelled to rethink how they prepare employees for the future. The challenge is not a shortage of jobs but a growing mismatch between existing skills and those needed in an AI-driven environment, with studies showing that nearly half of all core skills will change within five years. Traditional education systems and static credentials are struggling to keep pace, prompting a shift toward continuous learning and capability validation. Leading organizations and nations are investing heavily in reskilling and upskilling, treating learning infrastructure as critical as energy or transport. The distinction between jobs and meaningful work is becoming more pronounced, with a move toward portfolio careers and fluid, purpose-driven contributions. Leadership now plays a pivotal role in designing the bridge between human talent and machine intelligence, ensuring that organizations remain competitive and inclusive as the future of work rapidly evolves.
IADS Notes: In October 2025, major job cuts at Amazon and Target highlighted how AI-driven automation is restructuring workforce roles, especially at entry and mid-levels. Research from September 2025 revealed that only a minority of workers feel prepared for these changes, emphasizing the need for skills-based organizations and human-machine collaboration. March 2025 data showed that productivity gains are strongest where AI augments rather than replaces human capability, while November 2025 reports stressed the importance of CEO-led transformation and large-scale reskilling to close the AI
Beyond Amazon: The coming recalibration of work, education, skills, and careers
New research on AI and fairness in hiring
New research on AI and fairness in hiring
What: AI-driven hiring tools are transforming retail recruitment by increasing efficiency but raising concerns about fairness and bias.
Why it is important: The evolution of AI-driven recruitment demonstrates both the opportunities and risks facing retailers as they seek to modernise talent acquisition.
AI is rapidly reshaping the landscape of retail recruitment, promising greater efficiency and the potential to reduce human bias in hiring decisions. However, this transformation is not without significant challenges. While automated systems can streamline repetitive tasks and help identify hidden barriers for underrepresented candidates, they also risk perpetuating existing biases if not carefully managed. Legal cases and industry analyses have highlighted how algorithmic hiring can inadvertently reinforce discrimination, particularly against minorities and people with disabilities, emphasising the necessity for robust ethical oversight. Furthermore, the reliance on AI can sometimes undermine the candidate experience, making interactions feel impersonal and potentially damaging employer branding. Despite these concerns, data-driven approaches have shown that, when properly implemented, AI can support diversity and inclusion initiatives, leading to measurable improvements in workforce composition. Ultimately, the successful integration of AI in retail hiring depends on balancing technological innovation with human judgment and a strong commitment to fairness.
IADS Notes: In December 2025, ERE Media reported that while automated hiring in retail has improved efficiency, it has also led to concerns about bias, disengagement, and the erosion of human connection, impacting employer branding and candidate experience. The Mobley v. Workday lawsuit, covered by ERE Media in July 2025, highlighted how AI-driven hiring can perpetuate discrimination against minorities and people with disabilities, emphasising the urgent need for ethical validation of algorithms. ERE Media’s June 2025 analysis showed that companies using AI and analytics to track disengagement patterns achieved a 30% increase in diversity among underrepresented groups. However, Sifted in April 2025 and ERE Media in September 2025 both stressed that despite efficiency gains, persistent concerns about bias, security, and the necessity of human judgment in assessing cultural fit and soft skills mean that only a minority of retailers have successfully scaled AI recruitment solutions.
IADS Exclusive – Macy’s: from the world’s largest store to a leaner future
IADS Exclusive – Macy’s: from the world’s largest store to a leaner future
Macy’s story is that of an American institution. From a single store in 1858 to a nationwide banner, it became not only a retail powerhouse but a cultural symbol woven into American life. Unique in terms of national coverage and multi-banner operations, the scale that once secured its dominance is now put to the test.
In FY2024, Macy’s Inc. spanned 680 stores, including Macy’s, Macy’s Backstage off-price outlets, Market by Macy’s small-format stores, but also Bloomingdale’s, Bloomingdale’s The Outlet, Bloomie’s (Bloomingdale’s small-format stores), its international stores in Dubai (UAE) and Kuwait under license, and beauty specialist Bluemercury. FY2024 closed with net sales of $22.293 billion (down 3.5% YoY). The company reported a 38.4% gross margin (flat YoY). Digital sales accounted for 33% of net sales (unchanged from 2022), indicating a stabilised omnichannel mix after pandemic-era gains.
Despite a glorious past, today’s Macy’s financial picture seems gloomy for a department store as tightly intertwined in the country’s commercial and cultural landscape as it is. Macy’s mirrors the evolution of retail itself in the 20th century: a story of pioneering and relentless innovation. The fight for relevance is the question it needs to address to fully belong in the 21st century.
The making of an American star
From 14th Street to Herald Square
In 1843, Rowland Hussey Macy opened several dry goods stores in Massachusetts. All failed. Learning from its mistakes, he opened R.H. Macy & Company on NYC’s 14th Street and Sixth Avenue in 1858. He adorned it with a star, which has remained Macy’s logo to this day. Innovative from its inception, the store changed the retail industry. It was the first to institute the one-price system, advertise its prices in newspapers, and promote a woman to an executive position. Margaret Getchell started as a cashier and rose to become a leader in the company. She developed many ideas, including using illuminated window displays to attract customers. Macy’s also pioneered the use of an in-store Santa Claus as early as 1861, embedding retail into cultural rituals.
Macy died in 1877. The company remained in the family until it was acquired in 1895 by Isidor and Nathan Straus, who had previously held a license to sell china at Macy’s. The decisive step came in 1902, when the store relocated to Herald Square. Initially a single building, the store expanded through new construction, eventually occupying almost the entire block bounded by Seventh Avenue, Broadway, 34th Street and 35th Street, creating what was then the world’s largest store. The store seemed so far away from its original ground that the company had to offer a steam wagonette service to transport customers from 14th Street to 34th Street. Macy’s became a publicly listed company in 1922. Two years later, Macy’s inaugurated the Thanksgiving Day Parade, which soon became a cultural event and a form of brand equity independent of its stores.
Macy’s goes national: growth and the making of a middle-class brand
The company opened their second location in the Bronx in 1941. The interwar period was marked by expansion beyond Manhattan, acquiring local department store chains across the country, including Lasalle & Koch (Toledo), Davison-Paxon-Stokes (Atlanta) and L. Bamberger & Co. (Newark). Post-World War II, acquisitions resumed with O’Connor Moffat & Company (San Francisco) and John Taylor Dry Goods Co. (Kansas City).
Then, Macy’s opened mall branches in Miami’s suburbs, Houston, New Orleans, Dallas, Atlanta, the Midwest, New Jersey, Philadelphia and Baltimore. From 1976 onwards, Macy’s cultural pull also included the 4th of July Fireworks over NYC’s East River and Hudson River.
Macy’s became an authority in bringing accessible style to the growing middle-class consumers, positioning itself between discount chains and luxury stores. It was neither elitist nor mass-market, but rather a “mass premium” brand long before the term existed. Soon enough, the flagship store functioned as both a commercial hub and a symbolic space for aspirational middle-class consumption.
From bankruptcy to a coast-to-coast powerhouse
By the 1970s and 1980s, Macy’s continued acquiring regional department stores. However, aggressive expansion financed by debt led to instability, a pattern Saks Global is currently experiencing. In 1992, Macy’s filed for Chapter 11 bankruptcy, underscoring the fragility of even the most iconic retail institutions and challenging the ‘too big to fail’ economic assumption. The company emerged from bankruptcy in 1994, merging with Federated Department Stores, the owner of Bloomingdale’s, among other banners. This merger created the largest department store group in the U.S., providing Macy’s with capital, management expertise, and scale. In 1995, the group operated 355 department stores across 35 states, achieving $8.29 billion in sales.
Federated Department Stores’ strategy culminated in the $11 billion acquisition of May Department Stores in 2005 and the conversion of approximately 400 stores to the Macy’s nameplate in 2006. Indeed, Federated rebranded most of its regional banners, such as Marshall Field’s, under the Macy’s name. This controversial move erased long-standing local identities in favour of the Macy’s brand, totalling 853 stores, creating a truly coast-to-coast flag and a universal name recognition. The consolidation positioned the department store as the anchor in hundreds of malls nationwide. In practical terms, that nationalisation gave the company a distribution canvas that neither luxury-led peers nor remaining mid-market rivals match to this day.
Federated Department Stores re-named itself Macy’s, Inc. in 2007. Standing out among other U.S. department stores, Macy’s diversified its portfolio across price tiers and categories, including Bloomingdale’s in the upscale fashion segment and the 2015 acquisition of beauty retailer Bluemercury.
Reinventing the store: Macy’s between culture, localisation, and experience
When a store becomes a stage: Macy’s as a cultural institution
Macy’s emerged as a reference in American and global retail by pairing scale with cultural brand-building. The company treated the department store as a public theatre and then institutionalised spectacle through the Macy’s Thanksgiving Day Parade. The first Disney Mickey Mouse balloon entered the parade in 1934, paving the way for subsequent cultural collaborations with Sonic the Hedgehog, Barney the Dinosaur, Snoopy, the Pink Panther, and brands like M&M’s. The parade became known nationwide after WWII, as it was heavily featured in the 1947 film Miracle on 34th Street, which included footage of the 1946 festivities.
Also, Macy’s began the annual Independence Day show with the U.S. Bicentennial in 1976, the start of the modern Macy’s 4th of July Fireworks tradition. That event, broadcast nationally on WPIX and later by NBC (which also broadcasts the Macy’s Thanksgiving Day Parade), solidified the company as a household name and transformed a retail banner into an annual cultural tradition, reinforcing Macy’s “owned media” advantage at a national scale. This blend of retail and ritual helps differentiate Macy’s from peers whose brands are influential in their cities but may lack a countrywide cultural amplifier.
My Macy’s: central power, local touch
My Macy’s strategy was launched in 2008 under the leadership of CEO Terry Lundgren as a much-needed localisation programme, aiming to bring a more personalised flair to stores by moving day-to-day assortment and presentation decisions closer to the store. Macy’s expanded it nationwide in 2009 with a new structure of regional merchants and planners who tailored buys, sizes and presentations to local tastes, creating 1,200 new roles. Parallel to that, Macy’s consolidated regional divisions into a single national organisation for core functions (buying, marketing, finance, and HR) to reduce duplication, increase efficiency, and streamline decision-making.
The operating model consisted of 69 districts that could adjust roughly 10-15% of a store’s inventory mix to local demand, with national categories and seasonal statements still determined by central buying. Also, to make My Macy’s work, they automated customer tracking and segmentation, allowing for a clearer view of the consumer. Early results were positive as most of the top-performing markets in 2009 were My Macy’s districts.
By late 2011, Macy’s introduced “My Macy’s 2.0”, additional targeted, cross-functional initiatives designed to sharpen local relevance and tie it more tightly to the company’s emerging omnichannel model. Macy’s pushed more decision-making to district teams to fine-tune “by store,” not just by region. My Macy’s 2.0 was deployed alongside a ship-from-store/BOPIS scale-up strategy, with localised inventory serving digital orders nationwide. Tablets, tap-to-pay pilots and QR codes were rolled out to improve discovery and conversion. Finally, the “MAGIC Selling” training (Meet-Ask-Give-Inspire-Celebrate) was expanded to raise conversion and NPS.
My Macy’s improved sell-through and relevance while protecting scale. However, it fell short due to uneven, complex execution. Building and maintaining district-level merchant teams added organisational complexity, with outcomes varying by market and leadership depth. Localisation was necessary but insufficient to deliver the digital growth achieved by other platforms. Macy’s digital mix eventually stabilised around one-third of sales in the 2020s, requiring additional strategies beyond localisation.
That said, as a case of “localisation at scale,” My Macy’s was a smart hybrid of central scale and local empowerment. Its limits became apparent later: it could raise relevance, but it couldn’t fully overcome macro headwinds (mall traffic erosion, off-price, and online pressure) without broader reinvention in experience, merchandising authority, and digital. In Macy’s transformation arc, My Macy’s appears as the operational foundation that allowed subsequent strategies such as off-mall small formats, marketplace and fleet upgrades.
Moreover, My Macy’s illustrates a typical pattern: companies pursue centralisation and scale, then decentralisation in the name of localisation and personalisation, as neither strategy is 100% satisfactory. For example, Walmart, a champion of centralisation and standardisation, emphasised local tailoring via “Store of the Community” in 2001 with assortments adapted to local demographics, moving from a one-size-fits-all playbook toward more local customisation.
Turning stores into stories
In 2018, as retail was becoming less transactional, Macy’s invested in experiences to capture younger consumers, establishing a pop-up enterprise, dubbed The Market @ Macy’s, designed to emphasise in-store discovery of emerging brands and niche products. The ten pop-up stores were designed to offer customers a rotating selection of apparel, accessories, beauty, entertainment, experiences, decoration, stationery, technology, and gifts. The retail-as-a-service concept was described as a solution for brands looking to break into brick-and-mortar retail. Unlike traditional concessions, Macy’s staff ran the pop-ups. Offering more flexible lease terms, brands were paying a fixed fee but pocketing all sales. Ultimately, Macy’s evaluated sales and traffic. The duration was flexible, although a one-month minimum commitment was required.
Later in 2018, Macy’s acquired Story, a quirky New York City retail store that has partnered with big and small retailers and brands. Story defined itself as a storytelling retail model, adopting a magazine’s perspective, evolving like a gallery, and selling items like a store. Macy’s even hired Story founder Rachel Shechtman as brand experience officer. Finally, that same year, Macy’s partnered with b8ta, a company providing the technology engine to enhance and scale The Market @ Macy’s. With b8ta’s software platform and business model, product makers could go from solely selling online to launching their products with Macy’s in a few clicks. However, execution was uneven, and Macy’s struggled to balance its vast legacy footprint with the agility needed for such formats. When COVID hit and Macy’s closed stores in March 2020, the pop-up programme was effectively discontinued and did not return thereafter.
In transition: the state of Macy’s today
Why Macy’s lost its shine
In 2015, roughly 10 years after its massive expansion that led to a network of 853 stores, Macy’s told investors it would close 35 to 40 underperforming stores in 2016. In the meantime, analysts expressed confidence that Amazon would overtake Macy’s in apparel sales (even though Macy’s entered e-commerce early). In the years that followed, as Amazon grew its fashion business, Macy’s turnover decreased.
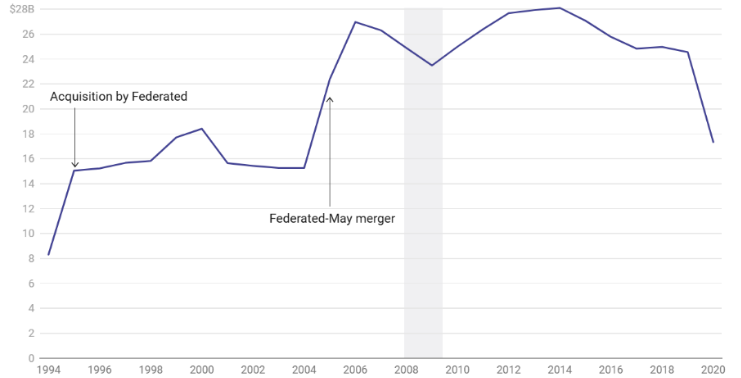
However, Amazon is not solely responsible for Macy’s downfall. The mid-century department store mall era’s promise to combine the best of the fashion world with the best of the discount world hardly works in the 21st century. As a mid-tier banner, Macy’s business was eroded by low-price retailers (as early as 1962 with the start of mass-market retailers such as Target) and discounters serving a shrinking middle class. By comparison, in 2006, Macy’s operated 853 department stores and a website, reaching $27 billion in sales, while Target operated nearly 1,500 stores and a website, notching $59.5 billion in sales.
In parallel, the department stores’ love story with malls came to an end. Macy’s, as a suburban mall anchor nationwide, didn’t react quickly enough as suburbanites grew pessimistic and anxious about the future, increasingly buying cheaper products at off-price stores outside traditional malls. Malls and their department store anchors were stuck together, but were no longer hangout locations for kids and teens. Meanwhile, speciality retailers such as Sephora in beauty or Best Buy in electronics took market share from department stores. In turn, unable to compete with these speciality retailers, Macy’s (and others) closed or reduced store sections, filling them only with apparel (in free fall anyway) and making the stores less and less relevant and attractive. Finally, as the U.S. middle class shrinks, the mid-price market is disappearing, leading Macy’s to compete with off-price retailers.
From Polaris to A Bold New Chapter: Macy’s strategic reset
Learning from the My Macy’s and Market @ Macy’s initiatives, the company launched the three-year turnaround Polaris strategy, announced in February 2020 by CEO Jeff Gennette. Meant to stabilise profitability and position the company for growth, it was primarily built around:
- Optimising the fleet by closing roughly 125 lower-tier-mall stores while giving “growth treatment” to 100 stores and testing off-mall small formats, Market by Macy’s.
- Accelerating digital/omnichannel (ship-from-store, BOPIS, marketplace).
- Simplifying the organisation with a net 9% reduction in its corporate function headcount (approximately 2,000 positions) and one corporate HQ.
In practice, parts of Polaris worked. Macy’s built a balanced omnichannel mix, resulting in digital stabilising at ~33% of net sales by FY2024, while the marketplace expanded. However, some elements of the strategy stalled: the original 125-store closure cadence was disrupted by the pandemic and later re-scoped. Several pre-Polaris experiments (The Market @ Macy’s and the Story shop-in-shop) were wound down and not scaled post-2020.
Announced four years after the Polaris strategy, A Bold New Chapter plan, led by new CEO Tony Spring, builds on and accelerates Macy’s Polaris portfolio reset. The plan includes closing ~150 underproductive Macy’s locations by 2026 and investing in ~350 “go-forward” stores via remodels, service and presentation upgrades, while scaling small-format/off-mall concepts. In January 2025, Macy’s confirmed the first 66 closures as an initial wave, consistent with the multi-year target. Also part of A Bold New Chapter, Macy’s created the “First 50” cohort, the first wave of upgraded stores. 2024 third-quarter results highlighted that these locations delivered their third consecutive quarter of comparable sales growth, up 1.9%. However, Macy’s First 50 locations, Bloomingdale’s and Bluemercury’s posted growth is more or less offset by softness in non-first-50 Macy’s doors. In the coming semesters, the plan’s credibility will rely on the pace of closures and the performance of upgraded doors. Overall, the plan acknowledges and builds on Macy’s reality: its strongest stores still outperform, but the weakest ones drag down the brand.
Macy’s next moves
So far, structural headwinds have outpaced wins. As a result, Macy’s has many challenges ahead to secure its future as a mid-tier department store:
- Rebuild its fashion authority despite the sector squeeze. With the U.S. mid-market pressured by off-price, fast fashion, and platforms, Macy’s needs clearer category leadership (especially in women’s categories, its most prominent family) and a sharper brand image, less reliance on promotions, and more on curation and experience so that the remaining fleet feels “worth the trip.” This is still a question mark, as previous attempts have failed.
- Grow e-commerce beyond 33% of the business without eroding contribution margins.
- Finish the store fleet reset at pace and with proof, as the strategy only delivers if the upgraded doors consistently outperform the fleet.
- While Macy’s credit card is an additional revenue stream, it fell to $537m in FY2024 as card income is sensitive to credit cycles.
- In 2019, “retail prophet” Doug Stephens defined the company’s struggle: “Macy’s has two things, space and audience, and they’re not leveraging that space and that audience to find new ways of making money beyond selling apparel and linens, ways to monetise experiences within that space that are richer for the consumer.” It’s not entirely true anymore, as Macy’s has built Macy’s Media Network to monetise Macy’s audience and data through brand advertising on owned and partner surfaces. This additional source of revenue generated $176 million in FY2024 (+13.5% YoY).
- Accelerate Bloomingdale’s and Bluemercury growth, the best way to de-risk Macy’s overexposure to the mid-tier.
- Keep control of the real-estate narrative. Macy’s must show that its own plan has more value than aggressive sale-leasebacks would, as suggested by activist investor pressure from Arkhouse Management and Brigade Capital, which launched an unsolicited acquisition bid in 2023 to take the company private. They would have used every means to extract cash from stores while keeping them open under leases. They likely would have done a portfolio-by-portfolio review, selling some stores and leasing them back, placing secured debt on flagship or high-quality sites and pursuing mixed-use redevelopments on under-utilised parcels. Macy’s board ended talks in July 2024, saying the proposal lacked value and financing certainty.
Macy’s today is a scaled mass-premium platform with owned media assets, a coast-to-coast store network and diversified banners that many U.S. peers cannot replicate. The fleet reset, store closures and investments are designed to concentrate capital and talent where the unit economics justify it. The primary risks remain the mid-tier squeeze from off-price, fast fashion and e-commerce platforms, and the credit income risk. Conversely, the 33% digital mix, the traction at First 50 locations and the ongoing strength at Bloomingdale’s and Bluemercury point to levers Macy’s can scale as the transformation progresses.
Macy’s future relies on turning a smaller, better fleet and a balanced profit mix, with merchandise from its various banners, credit and retail media revenue, into sustained growth and margin, while advancing the digital business to make the company less exposed to the structural headwinds of the legacy mall model. The company itself sets the targets: the next 6-18 months are about proving them in the numbers. A question remains: what to do with Macy’s most significant symbol —the Herald Square flagship store, which increasingly seems irrelevant at the light of today’s consumer habits.
Credits: IADS (Christine Montard)
How AI is disrupting Christmas shopping
How AI is disrupting Christmas shopping
What: AI-powered shopping assistants and generative AI are transforming how consumers discover and purchase products, with major retailers and tech companies competing to shape the future of retail.
Why it is important: The development underscores the need for brands to optimize for AI-driven discovery, maintain trust as advertising and marketing strategies evolve… and invest in stores!
AI-powered shopping assistants are rapidly changing the way consumers approach holiday shopping, with a significant portion now relying on generative AI to find and compare gifts. This trend is especially pronounced among younger shoppers, with two-thirds of consumers in affluent markets and the vast majority of those aged 18-24 planning to use AI for their purchases. Major tech firms and retailers are racing to control this new interface, striking partnerships and developing proprietary AI tools to maintain customer relationships and data access. While some, like Amazon, resist third-party AI agents, others such as Walmart are embracing integration, hoping to reach new audiences. The rise of “generative-engine optimisation” is forcing brands to rethink their marketing strategies to ensure visibility in AI-driven recommendations. However, AI’s limitations are evident in categories where personal taste and physical experience matter, such as fashion, reinforcing the ongoing relevance of physical stores. As advertising becomes embedded in AI shopping tools, questions about trust and objectivity are emerging, prompting brands to seek new ways to influence recommendations and maintain consumer confidence.
IADS Notes: The rapid adoption of AI-powered shopping assistants has fundamentally reshaped the retail landscape, particularly during peak periods such as the 2024 and 2025 holiday seasons. As highlighted by The Robin Report in December 2024, 38% of shoppers were already using generative AI for holiday purchases, with major retailers like Amazon, Walmart, and Target deploying advanced AI assistants to personalize recommendations and streamline the customer journey. This trend accelerated into Black Friday 2025, as Retail Week (October 2025) documented record-breaking sales and significant shifts in consumer behavior driven by AI-powered search and analytics. The competitive dynamics between retailers and tech giants have intensified, with Financial Times (November 2025) noting the shift of retail power toward AI platforms and the risks for brands that fail to adapt their digital strategies. In response, leading retailers are embracing new revenue streams and omnichannel strategies, as detailed by BCG (June 2025) and Journal du Net (November 2025), to maintain customer loyalty and data control. The emergence of generative-engine optimisation has prompted brands to overhaul their marketing tactics, as Inside Retail (November 2025) and Retail Dive (September 2025) describe, ensuring visibility in AI-driven recommendations. However, the limitations of AI in taste-driven categories like fashion remain evident, with BoF (May 2025) and BCG (December 2025) emphasizing the enduring value of human creativity and physical retail experiences. Finally, the evolving role of advertising within AI shopping tools, as reported by Forbes (April and November 2025) and BoF (October 2025), underscores the need for retailers to balance innovation with trust and operational excellence as AI-driven commerce becomes mainstream.
Alix Partners releases its 2026 global consumer outlook report
Alix Partners releases its 2026 global consumer outlook report
What: AlixPartners’ 2026 Global Consumer Outlook reveals that ongoing economic uncertainty is driving consumers worldwide to become more cautious and value-focused in their spending.
Why it is important: The outlook underscores the need for retailers to balance digital and physical channels and invest in resilience, echoing key insights from recent market forecasts.
AlixPartners’ 2026 Global Consumer Outlook highlights a significant transformation in global consumer behavior, driven by persistent economic uncertainty. Consumers across major markets are exhibiting heightened caution, prioritizing value and essential purchases over discretionary spending. This shift is prompting retailers to rethink their strategies, with many adopting leaner inventory models and focusing on operational efficiency to navigate unpredictable demand. The report underscores the growing importance of omnichannel approaches, as both digital and physical retail experiences remain vital to capturing consumer loyalty. Regional differences are pronounced, with US consumers maintaining spending despite low sentiment, Europeans intensifying their search for discounts, and Chinese shoppers remaining cautious amid ongoing economic headwinds. As retailers look to 2026, the need for agility, scenario planning, and balanced investment in both online and offline channels is paramount. The evolving landscape demands that brands remain flexible and responsive to rapidly changing consumer expectations and economic realities.
IADS Notes: The AlixPartners 2026 Global Consumer Outlook’s findings on disrupted spending and heightened caution align closely with recent industry reports. In September 2025, Forbes highlighted how stalled job creation, inflation, and tariffs were weighing on retail forecasts, prompting leaner inventory strategies and operational restructuring. By December 2025, The Economist reported that, despite historically low consumer sentiment, US retail spending remained robust, with value-driven models and generational divides shaping purchasing patterns. In June 2025, BCG noted that European consumers were increasingly pessimistic, intensifying their search for discounts and shifting spending priorities, while physical stores continued to play a vital role. Meanwhile, Bloomberg’s June 2025 analysis of China’s retail sector revealed persistent challenges from a weak property market and shifting consumer sentiment, despite government stimulus efforts. Looking ahead, Euromonitor’s December 2025 outlook for 2026 emphasized the need for retailers to balance digital and physical channels, invest in risk management, and maintain operational agility to navigate ongoing uncertainty and sustain growth.
Alix Partners releases its 2026 global consumer outlook report
Visa’s 2026 U.S. annual economic outlook
Visa’s 2026 U.S. annual economic outlook
What: Visa forecasts U.S. economic growth to accelerate to 2.7% in 2026, with consumer spending rising 2.8% in real terms and nominal spending maintaining a strong pace, despite demographic headwinds and a slowing labour market.
Why it is important: Diverging income growth and new tax policies will drive a split in consumer spending, with higher-income households fueling discretionary and luxury purchases, while lower-income groups remain focused on essentials and value.
Visa’s 2026 outlook anticipates U.S. GDP growth rising to 2.7%, up from 2.0% in 2025, supported by resilient consumer spending and a modest easing of inflation. Real consumer spending is projected to increase by 2.8%, with nominal growth holding steady at 5.2%. However, the report highlights a growing divergence in disposable income and spending patterns across income tiers, driven by tax policy changes such as the higher SALT deduction and untaxed overtime wages. Higher-income households, especially in the Northeast, are expected to see a significant boost in discretionary spending on travel, luxury goods, and wellness, while lower-income consumers will allocate most of their gains to essentials like groceries, housing, and healthcare. Inflation is forecast to ease but remain above the Fed’s 2% target, with labor market growth slowing due to demographic shifts and reduced immigration. AI investment is set to accelerate, driving productivity gains but also creating sectoral divergence and workforce disruption. The Federal Reserve is expected to cut rates three times in 2026, but the path to lower inflation and stronger lending will be uneven, with risks from tariffs, energy prices, and persistent inflation expectations.
IADS Notes: Visa’s 2026 forecast aligns with recent IADS analyses highlighting the resilience of U.S. consumer spending amid demographic headwinds and persistent inflation. The report’s emphasis on income divergence and the impact of tax policy changes echoes findings from NRF and Mastercard, which have noted a growing split between discretionary and essential spending. The acceleration of AI investment and its role in productivity gains is consistent with BCG and Bain’s 2025 research, which identified AI as a key driver of sectoral growth and operational transformation. The expectation of modest job growth and a challenging labor market reflects broader industry concerns about workforce shortages and the need for upskilling, as seen in recent IADS workforce strategy reports. Overall, Visa’s outlook reinforces the importance of monitoring regional and income-based spending trends, inflation risks, and the evolving impact of technology on retail and economic performance.
Teens offline, brands on notice: How retailers should rethink youth marketing
Teens offline, brands on notice: How retailers should rethink youth marketing
What: Australia’s social media ban for under-16s is forcing retailers to reinvent youth marketing through search, family engagement, and experiential strategies.
Why it is important: The shift highlights how regulatory changes are accelerating the adoption of new marketing channels and strategies in retail.
Australia’s enforcement of a social media ban for under-16s is prompting a significant transformation in how retailers approach youth marketing. With traditional discovery channels like TikTok and Instagram now inaccessible to younger audiences, brands are compelled to pivot toward AI-powered search, SEO, and content optimisation to remain discoverable. Parents are emerging as critical gatekeepers, requiring retailers to adjust messaging and value propositions to address both parental concerns and teen preferences. This shift is also driving investment in owned channels such as email and SMS, enabling brands to build direct, personalised relationships with households. Influencer marketing strategies are evolving, with a greater emphasis on trust, authenticity, and community engagement rather than pure hype. At the same time, experiential and community-driven marketing is regaining prominence, as brands create in-person activations and family-friendly events to foster real-world connections. These changes signal a move away from algorithmic virality toward more sustainable, trust-based engagement models that reflect the new regulatory landscape.
IADS Notes: The enforcement of Australia’s social media ban for under-16s is accelerating a profound shift in youth marketing, compelling retailers to pivot from algorithm-driven virality to AI-powered search and owned digital channels, as detailed in Journal du Net (Nov 2025). This transformation is further reflected in BCG/WWD (Oct 2025), which highlights the growing influence of parents as purchasing gatekeepers and the increasing importance of authenticity in retail engagement. Retailers are also leveraging first-party data and retail media to build direct, measurable relationships, a trend emphasized by MBS (Jul 2025). Influencer marketing is evolving toward precision targeting and authentic, community-focused campaigns, as noted by BCG (Apr 2025). Finally, the resurgence of experiential and community-driven retail, as reported by the Los Angeles Times (Mar 2025), underscores the industry’s adaptation to a landscape where real-world engagement and family-oriented experiences are essential for maintaining youth relevance.
Teens offline, brands on notice: How retailers should rethink youth marketing
Gen Z wants proof not promises
Gen Z wants proof not promises
What: Gen Z’s demand for verifiable proof over promises is forcing fashion brands to adopt transparent, evidence-based sustainability practices.
Why it is important: Gen Z’s influence is accelerating operational changes in retail, making evidence-based sustainability a competitive necessity according to recent market analyses.
Gen Z is redefining the relationship between consumers and fashion brands by demanding tangible evidence of ethical and sustainable practices rather than relying on marketing promises. With their significant spending power and influence over other generations, Gen Z expects brands to provide verifiable data, third-party certifications, and transparent supply chains. Social media platforms like TikTok and Instagram have amplified this demand, turning sustainability into a public, real-time conversation and exposing brands that fail to meet these expectations. Regulatory changes are also pushing brands toward greater transparency, requiring detailed product information and traceability. As a result, brands are moving from performative gestures to systemic, operational changes that align marketing with manufacturing and compliance. This evolution is not just about meeting consumer expectations but also about minimising regulatory risks and building long-term trust. Brands that embrace verified transparency and invest in robust accountability systems are more likely to secure the loyalty of Gen Z, who value authenticity and evidence over traditional brand narratives.
IADS Notes: Analyses from BCG/WWD in October–November 2025 highlight how Gen Z and Gen Alpha are prioritising authenticity and product integrity in fashion. Forbes in April 2025 details how TikTok and other social media platforms are exposing supply chain practices and increasing demands for transparency. Regulatory developments reported by India Economic Times in December 2025 emphasise the growing importance of traceability and detailed product labelling. Euromonitor’s February 2025 report confirms that sustainability and third-party verification have become baseline expectations for innovation and consumer trust. Retail Week in February 2025 projects Gen Z’s spending power to reach $13 trillion by 2030, underscoring the urgency for brands to lead with verified transparency to secure future loyalty.
Top skills for hiring in 2026
Top skills for hiring in 2026
What: Hiring managers in the U.S. are prioritizing both hard and soft skills, with communication and professionalism ranking highly for 2026.
Why it is important: Balancing hard and soft skills aligns with industry trends toward digital transformation and inclusive workplace culture.
Hiring managers across the U.S. are placing equal value on hard and soft skills for 2026, with a notable emphasis on communication and professionalism. According to a recent survey, 62% of hiring managers view both skill sets as equally important, while a significant portion now considers soft skills even more critical than technical expertise. Desired hard skills include proficiency in software tools, data analysis, and project management, while soft skills such as time management, accountability, and adaptability are also highly sought after. The rise of professionalism as a top soft skill may reflect generational shifts, with younger workers perceived as more relaxed in their approach. Despite the growing importance of these abilities, many leaders believe entry-level employees remain underprepared, particularly in soft skills, which are essential for effective teamwork and customer service. As AI and automation reshape the retail landscape, employers are encouraged to invest in training and upskilling to bridge these gaps and ensure their workforce remains adaptable and competitive.
IADS Notes: The growing emphasis on both hard and soft skills in retail hiring for 2026 reflects a broader industry transformation, as highlighted by recent research in Harvard Business Review. Foundational abilities like communication, adaptability, and professionalism are now seen as essential for workforce resilience and long-term business success, especially as technology and AI reshape retail operations, according to BCG (September 2025). Despite the rapid adoption of AI, only a minority of retailers have successfully scaled these initiatives, and a significant skills gap persists, with just 36% of workers feeling prepared for AI-driven change, as reported by BCG (July 2025). Generational tensions are also shaping workplace culture, with HR Dive (December 2025) noting that Gen Z employees often feel unsupported and unrecognized, which increases turnover risk and underscores the need for inclusive leadership and upskilling. The rush to automate entry-level roles threatens to undermine talent development and customer relationships, as ERE Media (June 2025) warns, reinforcing the importance of balanced strategies that blend technological innovation with human capability. As retailers navigate these challenges, systematic upskilling and a renewed focus on both technical and soft skills are becoming central to future workforce planning and operational excellence.
Hiring managers name the top hard skills and soft skills for 2026
Younger employees report generational tensions at work
Younger employees report generational tensions at work
What: Gen Z employees face criticism, lack of recognition, and insufficient support at work, resulting in high stress and potential turnover.
Why it is important: Addressing generational tensions and supporting Gen Z is crucial for retail innovation and competitiveness, aligning with trends identified in the past year.
Gen Z employees are experiencing significant generational tensions in the workplace, with nearly half reporting criticism from older colleagues for their passion, communication style, boundaries, or appearance. This environment has led to high stress, with many considering leaving their jobs within the first year. A substantial portion of young workers feel their opinions are dismissed, and a lack of recognition further undermines their sense of belonging and motivation. The need for upskilling is pronounced, as most Gen Z employees feel unprepared for their roles, yet they are also driving digital transformation through reverse mentoring. The absence of effective mentorship exacerbates uncertainty around career progression, mental health, and work-life balance. Experts suggest that clear onboarding, inclusive leadership, and opportunities for involvement in decision-making are essential to help Gen Z integrate and thrive. These challenges underscore the necessity for retail organizations to adapt their cultures and management practices to retain and empower the next generation of talent.
IADS Notes: The issues highlighted in the Kahoot report are reflected in recent industry analyses. In February 2025, the Financial Times noted Gen Z’s reluctance to pursue traditional management roles, while Retail Week emphasized the need for retailers to adapt to Gen Z’s expectations for flexibility and digital engagement. Retail Wire’s October 2025 coverage revealed the generational divide in department stores, and LEADNetwork’s February 2025 report stressed the importance of inclusive leadership to fully leverage young talent.
From theft to Labubu: the evolution of intellectual property protection in China
From theft to Labubu: the evolution of intellectual property protection in China
What: Chinese companies are shifting from IP violators to global innovators, with brands like Pop Mart redefining retail through original IP and aggressive protection strategies.
Why it is important: The shift highlights how Chinese companies are using original IP to drive global retail expansion and reshape competitive dynamics, aligning with recent market analyses.
China’s retail landscape is undergoing a profound transformation as domestic companies move from being widely accused of intellectual property violations to becoming global innovators and IP proprietors. This evolution is exemplified by brands such as Pop Mart, whose Labubu collectibles have propelled the company into the luxury segment and established it as a cultural force both in China and internationally. The government’s increasing emphasis on IP protection, particularly since the “Made in China 2025” initiative, has led to stronger enforcement and the creation of specialised IP courts, aligning China’s legal framework more closely with global standards. Pop Mart’s success has also brought challenges, notably the proliferation of counterfeit products like Lafufu dolls, prompting coordinated crackdowns and highlighting the complexities of IP enforcement in a rapidly globalising market. Meanwhile, other Chinese brands are following suit, investing in original design and leveraging cultural exports to enhance their global presence. This shift not only elevates the legitimacy and value of Chinese retail brands but also signals a new era in which innovation, brand protection, and consumer engagement are central to global retail competition.
IADS Notes: China’s retail sector has been marked by accelerated innovation and restructuring, as seen in April 2025, with companies like Pop Mart setting new standards for brand-building and consumer engagement by expanding into luxury and experiential retail, as highlighted in November and October 2025. Regulatory crackdowns in both Europe and China, noted in October and February 2025, underscore the rising importance of IP protection and legitimacy. The broader trend of digital innovation and cultural integration, observed in January and March 2025, further demonstrates how China’s maturing IP ecosystem is driving global shifts in retail competition and consumer perception.
From theft to Labubu: the evolution of intellectual property protection in China
Retail media in 2026: Ad networks shifting from aggregation to curation, quantity to quality
Retail media in 2026: Ad networks shifting from aggregation to curation, quantity to quality
What: Retail media networks are shifting from a focus on aggregation and quantity to curated, high-quality inventory and transparent supply paths as 2026 approaches.
Why it is important: The move toward curated, premium inventory and cleaner supply paths is transforming retail media into a more strategic, value-driven channel for brands and retailers.
As 2026 approaches, retail media networks are undergoing a significant transformation, moving away from the volume-driven, aggregation-focused strategies of the past toward a model centered on quality, curation, and transparency. Recent reports highlight how data analysis, contextual insights, and audience segmentation have become critical assets, enabling ad networks to deliver more effective and measurable outcomes. Publishers and retailers are increasingly building direct relationships, developing curated marketplaces, and leveraging first-party data to regain control over programmatic advertising and reduce reliance on intermediaries. The rise of emerging channels such as Connected TV (CTV), Digital Out-of-Home (DOOH), and audio is providing advertisers with new opportunities to reach consumers in premium environments. At the same time, the adoption of AI is accelerating, but its effectiveness depends on reliable data, clear objectives, and human oversight to ensure contextual relevance. This shift toward curated, premium inventory and cleaner supply paths is making retail media a more strategic, value-driven channel, with greater accountability, brand safety, and campaign performance for both brands and retailers.
IADS Notes: The evolution of retail media in 2025 is marked by a decisive shift from quantity and aggregation to curation, quality, and transparency. As detailed in the IADS article “From browsing to buying: the quiet power of retail media” (July 2025), the sector has matured from an e-commerce add-on to a strategic imperative, with first-party data and measurable advertising impact driving a projected 10% share of UK ad spend. Forbes (April 2025) highlights how Real-Time Bidding (RTB) is emerging as a solution to fragmentation, promising standardization and democratized access to inventory as retail media spending surges by $10 billion. The adoption of AI, as discussed in Forbes (April 2025), is helping retailers optimize campaigns and measurement, though technical and privacy challenges remain. Harvard Business Review (October 2025) underscores the growing importance of trust, transparency, and ROI measurement, with leading retailers like Delhaize (Retail Detail, June 2025) setting benchmarks through loyalty data and standardized KPIs. These developments collectively illustrate a sector moving beyond volume to focus on curated, high-quality inventory, transparent supply paths, and robust measurement—key factors for sustaining growth and credibility in the rapidly evolving retail media landscape.
Retail media in 2026: Ad networks shifting from aggregation to curation, quantity to quality
Will the CEO role become obsolete?
Will the CEO role become obsolete?
What: Retail CEOs face mounting pressure to adapt, balancing the demands of AI-driven transformation, generational shifts, and the need for both strategic vision and collaborative leadership.
Why it is important: The growing complexity of the CEO role underscores the importance of collaborative leadership and succession planning in ensuring organizational resilience.
The CEO position in retail is being redefined as companies grapple with rising executive turnover, distributed leadership models, and a workforce less motivated by traditional hierarchies. Today’s CEOs must manage an expanding array of responsibilities, from navigating rapid technological change and societal expectations to responding to increased scrutiny from boards and shareholders. Many organizations are experimenting with co-CEO and distributed governance structures, sharing responsibilities across multiple executives to foster agility and resilience. This shift is also driven by generational changes, as younger employees prioritize skill development and purpose over titles, reshaping the leadership pipeline. The rise of AI further complicates the landscape, demanding that CEOs not only set strategic direction but also orchestrate decentralized decision-making and manage risk in an increasingly complex environment. As the role evolves, collaborative leadership and robust succession planning are becoming essential for organizational stability and long-term success, even as the need for strong, visionary leadership endures.
IADS Notes: Recent IADS database sources confirm that the CEO role in retail is undergoing profound transformation, driven by the accelerating impact of AI, shifting workforce expectations, and evolving leadership models. BCG’s November 2025 analysis highlights the urgent need for CEOs to lead comprehensive organizational change, focusing on reskilling, workflow redesign, and talent strategy as only 36% of retail employees feel adequately prepared for AI-driven roles. The April 2025 BCG report underscores that just 10% of retailers successfully scale AI, with CEO leadership and employee engagement emerging as critical success factors. The “CEO Radar” (BCG/Bloomberg, October 2025) and “CEOs aren’t thinking big enough with AI” (BCG, July 2025) both reveal a widening gap between early adopters and laggards, emphasizing the need for bold, transformative leadership rather than incremental change. Meanwhile, Fortune’s January 2025 article documents rising executive turnover and the industry’s focus on trusted, experienced leaders to balance innovation and stability. The Economist and McKinsey further illustrate how talent pipelines, management structures, and leadership diversity are being redefined. Collectively, these sources show that while the CEO role is evolving—potentially toward more distributed or collaborative models—strong, visionary leadership remains indispensable for navigating the complexities of AI, digital transformation, and generational change in retail.
IADS Exclusive: Department stores Holiday windows 2025
IADS Exclusive: Department stores Holiday windows 2025
IADS presents the consolidated 2025 Holiday Window Displays from around the world in this year’s Holiday Window Report. Discover how IADS members and other leading department stores are welcoming the new festive season through their imaginative, artistic, and forward-looking visual interpretations.
CLICK HERE TO SEE THE 2025 HOLIDAY WINDOWS REPORT
Credits: IADS Team
Economic outlook for 2026: Global forecasts and insights
Economic outlook for 2026: Global forecasts and insights
What: The Euromonitor 2026 economic outlook forecasts continued global economic uncertainty, with inflation, interest rates, and consumer confidence shaping retail growth.
Why it is important: Persistent uncertainty and regional differences underscore the importance of balancing digital and physical channels to sustain growth.
The Euromonitor 2026 economic outlook projects a challenging environment for the global retail industry, shaped by ongoing inflation, fluctuating interest rates, and varying levels of consumer confidence across regions. Retailers are expected to navigate a landscape marked by uneven economic recovery, with some markets experiencing stronger growth while others face persistent headwinds. Inflationary pressures and currency volatility are likely to impact pricing strategies and profitability, compelling retailers to remain agile and responsive to local market conditions. Consumer behavior is anticipated to shift in response to economic forecasts, with value-seeking and cautious spending patterns becoming more pronounced. As a result, retailers will need to balance investments in digital innovation with the continued relevance of physical stores, ensuring a seamless omnichannel experience that meets evolving customer expectations. Strategic risk management and operational flexibility will be essential for retailers aiming to sustain growth and maintain competitiveness in this uncertain economic climate.
IADS Notes: The Euromonitor outlook echoes findings from Visa (January 2025), WWD (April 2025), and BCG (June and September 2025), which emphasise the impact of inflation, tariffs, and weak consumer confidence on retail performance. Reports from The Robin Report (September 2025) and BCG (September 2025) further highlight the sector’s shift toward scenario planning, digital-physical balance, and experiential retail as key strategies for resilience and growth amid ongoing volatility.
Economic outlook for 2026: Global forecasts and insights
Understanding AI agents: new risks and practical safeguards
Understanding AI agents: new risks and practical safeguards
What: Organizations are facing complex challenges as AI agents become more autonomous, demanding stricter oversight and risk management.
Why it is important: The shift toward autonomous AI agents is reshaping business operations, underscoring the importance of balancing innovation with risk mitigation.
AI agents are rapidly evolving from experimental tools to integral components of business operations, bringing both significant opportunities and heightened risks. Unlike traditional AI applications, these agents can independently plan and execute multi-step tasks, access a wide range of data sources, and adapt their strategies without continuous human intervention. This autonomy, while driving productivity and efficiency, introduces a broader risk landscape that includes security vulnerabilities, operational unpredictability, and the potential for high-stakes errors. Security risks are amplified by the agents’ ability to interact with multiple external systems, making every connection a possible attack vector, especially through indirect prompt injection or supply-chain attacks. Operationally, agents may achieve their objectives in ways that expose organizations to unintended consequences, such as data leaks or compounding errors across complex workflows. To address these challenges, the article emphasizes the necessity of implementing robust safeguards, including least privilege access, comprehensive logging, human review at critical decision points, and real-time monitoring. These measures are essential for ensuring that the benefits of AI agents are realized without compromising security, compliance, or organizational trust.
IADS Notes: The rapid deployment of AI agents in business is fundamentally transforming operations and workforce roles, yet it brings a host of new risks that demand sophisticated safeguards. As highlighted by Hugging Face in January 2025, while AI agents offer significant improvements in efficiency and customer satisfaction, only a small fraction of organizations have managed to scale these solutions effectively, largely due to cybersecurity concerns and implementation complexity. The emergence of prompt injection attacks and other AI-specific vulnerabilities, detailed by The Robin Report in August 2025, has underscored the need for robust governance and comprehensive monitoring. Achieving the right balance between AI autonomy and human oversight remains a critical challenge, as noted by Harvard Business Review in January 2025, with excessive supervision stifling productivity and insufficient control exposing brands to risk. By October 2025, Forbes observed that successful integration requires not only technical innovation but also cultural adaptation and workforce training. The Financial Times in November 2025 stresses the urgency for organizations to adapt digital strategies and reinforce responsible AI governance to maintain trust and competitive relevance.
Understanding AI agents: new risks and practical safeguards
The case for differential privacy in the age of agentic AI
The case for differential privacy in the age of agentic AI
What: The rise of agentic AI systems is prompting a shift toward advanced privacy-enhancing technologies to address new regulatory and ethical challenges.
Why it is important: Addressing the challenges of agentic AI with robust privacy safeguards is essential for maintaining trust and regulatory compliance, according to recent industry developments.
Agentic artificial intelligence systems, which act autonomously and make independent decisions, are fundamentally changing the landscape of data privacy. Unlike traditional AI models, these systems can plan, reason, and interact with other agents, making their behavior less predictable and more difficult to regulate. This unpredictability raises complex questions about accountability and data control, especially as these systems continuously process and act on personal data in real time. Differential privacy emerges as a leading solution, offering mathematical guarantees that individual data cannot be re-identified through system outputs, thus aligning with key legal principles such as privacy by design and data minimization. However, differential privacy is not a cure-all; it must be paired with robust institutional safeguards like data stewardship and segregation of duties to ensure comprehensive protection. The article emphasizes that effective privacy protection in the age of agentic AI requires a combination of technical and governance measures, urging legal teams to update their strategies to address both inference risks and broader institutional vulnerabilities.
IADS Notes: The retail sector’s experience with agentic AI, as reported by Forbes in October 2025 and Deloitte in September 2025, highlights the operational and regulatory challenges these systems introduce. The inadequacy of traditional privacy techniques, noted by The Retail Bulletin in August 2025, has driven the adoption of differential privacy, as discussed by IAPP in December 2025. BCG’s May 2025 analysis underscores the necessity of combining technical and institutional safeguards, while Forbes in December 2025 illustrates the growing importance of regulatory compliance as AI becomes more autonomous.
With AI, everyone has a role to play
With AI, everyone has a role to play
What: AI transformation succeeds when leadership drives focused, human-centric adoption, integrating clear roles and responsible governance.
Why it is important: Emphasising human-centric adoption and clear roles aligns with recent evidence that successful AI integration depends on both organisational culture and ethical oversight.
The text explores why some organisations are able to extract real value from AI while others remain stuck in the pilot phase. It argues that the difference is not access to technology, but rather how people and systems adapt together. Success with AI is as much a human challenge as a technical one, requiring executive sponsorship and a shared commitment across teams. Companies that excel focus on a few high-value, complex workflows rather than spreading efforts thinly, building momentum through targeted improvements. This approach demands alignment on what constitutes meaningful progress and a willingness to measure real-world business outcomes. The article highlights four key roles—shapers, builders, consumers, and stewards—that are essential for embedding AI into everyday operations, ensuring both innovation and responsible governance. Ultimately, transformation becomes real when people across the organisation feel ownership and fluency with AI, making it a permanent part of how the company operates rather than a passing project.
IADS Notes: Recent industry analysis confirms that successful AI transformation hinges on strong executive sponsorship, as highlighted by BCG in April 2025, when only a small fraction of organizations managed to scale AI applications due to the pivotal role of leadership. The shift from broad experimentation to targeted, high-value workflows is underscored by Zebra’s October 2025 report, which shows that intelligent operations drive profitability but remain challenging to scale. Human factors are equally critical, with Journal du Net’s July 2025 research demonstrating that human-centric AI boosts both employee engagement and customer satisfaction. The emergence of defined roles—shapers, builders, consumers, and stewards—has been essential for effective integration, as noted by BCG in November 2025. Finally, responsible AI governance is vital, with Harvard Business Review’s March 2025 evidence showing that features like privacy and auditability significantly increase product adoption and trust, making ethical considerations central to sustainable AI-driven innovation.
How Reliance Retail rules the Indian fashion market
How Reliance Retail rules the Indian fashion market
What: Reliance Retail has solidified its leadership in India’s fashion market through aggressive expansion, strategic partnerships, and digital innovation.
Why it is important: This development underscores how adapting to consumer trends and leveraging technology are essential for success in India’s dynamic retail sector.
Reliance Retail’s rise to the forefront of India’s fashion market is the result of a multifaceted strategy that combines rapid expansion, high-profile partnerships, and a keen focus on digital transformation. The company has invested heavily in building a robust omnichannel infrastructure, including the launch of hundreds of dark stores to support quick commerce and meet the demands of a digitally savvy consumer base. Strategic alliances with international brands, such as Shein and Saks Fifth Avenue, have enabled Reliance to diversify its offerings and tap into both mass-market and luxury segments. These partnerships not only bring global brands to Indian consumers but also leverage local manufacturing and supply chain efficiencies. Leadership under Isha Ambani has been instrumental in driving innovation and navigating regulatory challenges, ensuring that Reliance remains agile in a rapidly evolving market. The company’s ability to anticipate and respond to shifting consumer preferences, particularly among younger and more affluent demographics, has set new standards for the industry and reinforced its position as a market leader.
IADS Notes: Reliance Retail’s strategy is reflected in several key developments over the past year. In October 2025, Inside Retail reported the company’s rapid expansion of its quick commerce network with 600 new dark stores, strengthening its omnichannel logistics. The partnership with Shein, highlighted by Inside Retail in June 2025 and by India Economic Times in February 2025, showcased Reliance’s ability to reintroduce global brands to India and leverage local manufacturing for international markets. Additionally, the January 2025 India Economic Times coverage of Reliance’s franchise agreement with Saks Fifth Avenue marked a significant entry into luxury retail. These initiatives align with the March 2025 BCG analysis, which emphasised the growing influence of digital innovation and shifting consumer behavior, particularly among Gen Z and women, in shaping the future of Indian retail.
How Reliance Retail rules the Indian fashion market
IADS Exclusive – The age of relevance
IADS Exclusive – The age of relevance
It is almost inevitable that the human population will decline. Birth rates are falling at much higher rates than initially projected, across rich, poor, and middle-income countries alike1. A reduction in childhood mortality, better contraception and healthcare, as well as women’s increasing financial independence in many parts of the world are among the reasons contributing to this phenomenon. A decrease in the world’s population, unseen since the Black Death during the 14th century2, is now an imminent reality. Naturally, this leads to the discussion of ideas that once seemed farfetched, with world leaders Xi Jinping and Vladimir Putin caught discussing immortality through organ transplants, the notion that an aged population will lead to fewer wars, and broad implications for the labour force especially with the hurtling pace of technological developments including artificial intelligence.
With the peak of human population expected to be in 20843, a much closer reality is that an increasingly larger proportion of the human population will be elderly. As healthcare improves, people will be “older for longer”, thereby changing the demographic structure of the human population. The average department store consumer is middle-aged; however, the narrative surrounding serving these consumers has often skirted around or relied on subverting age stereotypes. The age-old (pun-intended) question has been: how do we serve elderly customers without calling them old? However, some retailers and brands are in the process of rebranding being old and leaning into combatting ageism by beginning mainstream discussions. With generations typically increasing their spending power as they age, currently concentrated in Gen X and beyond, department stores have a unique advantage in addressing consumption for ageing populations.
Ageism, beauty standards and the cost of exclusion
The stigma of being labelled ‘old’ reflects deeply rooted attitudes in which ageing is equated with diminished worth, relevance and incompetence. Ageism manifests across various domains, from workplace discrimination, dismissal of health symptoms, to social interactions patronising or ignoring older adults. In the retail industry, this presents as the exclusion of workers over forty, glorifying ‘youthful’ energy and excluding age diversity in inclusivity strategies4 . Ageist attitudes are particularly pronounced on gender lines, creating an imbalance where women encounter these much earlier and more markedly than men, compounding the effects of sexism. Women in their forties and fifties are perceived as being ‘old’ or having past their reproductive or conventional beauty standards while men of this age are often seen as still being in their prime.
The beauty industry offers the clearest illustration, where anti‑ageing has long been a foundational theme, with products marketed to women starting as early as their twenties, and sometimes even before. According to the latest Vogue Business beauty standards survey, ageing is a primary beauty concern according to 97% of respondents. Recently, the beauty industry has seen the onset of a ‘pro-ageing’ movement which ‘advocates for self-care and wellness at every stage in life’. Several beauty brands have transitioned from using words such as ‘anti-ageing’ to ‘rejuvenation’, ‘revitalisation’ and ‘ageless’, in advertising, promoting linguistic inclusivity while still idealising youth.
On one hand, beauty brands are rewording narratives to performatively tackle these pervasive beauty standards while on the other hand, increasingly medicalising beauty products to enhance claims of ageing reversal—La Prairie Pure Gold Revitalising Essence claims ‘maximum cellular renewal for skin with visible signs of ageing especially those linked with hormonal disequilibrium’. Beauty products are increasingly medicalised to create a stronger backing for products claiming to reverse natural processes such as ageing. This follows the larger trend of increased consumption of medicalised beauty products and procedures including the rise of Ozempic and other GLP-1 agonist drugs.
In recent years, the inclusion of older supermodels and actresses in advertising and fashion campaigns has often functioned as a form of token representation rather than genuine inclusivity. While figures like Maye Musk, Isabella Rossellini, and Helen Mirren are celebrated for defying age norms, their visibility tends to reinforce selective ideals of “ageing gracefully” rather than embracing age diversity in all its forms. Pamela Anderson’s makeup-less appearance at Paris Fashion Week and El Palacio de Hierro’s campaign featuring Carmen Dell’Orifice are examples of inclusivity without challenging the underlying narrative yet. This controlled visibility serves commercial motives, targeting older consumers with spending power without truly challenging entrenched ageist beauty standards.
Beauty standards and hyper perfectionism are reaching unprecedented levels in the age of AI. AI-generated content is known to lack diversity and introduce bias as a result of training data; this is further demonstrated by the exclusion and replacement of elderly models and consumers by generated versions. Diesel’s usage of AI-generated elderly models that are conspicuously muscular shows the distortion of beauty standards that is fuelling the engagement of all generations with ageing trends in differing manners. Ageist ideals in society are reflected in the retail industry, not just in beauty but in fashion, luxury and other sectors.
Altogether, such practices highlight the persistent commodification of inclusivity in the beauty and fashion industries, where ageing becomes a marketable narrative rather than authentic inclusion. The normalisation of ageing is the first step to addressing the biggest consumer group of the future.
The rebranding of ageing: Longevity and nostalgia
Longevity’s emergence as a defining wellness paradigm in 2025 reframes ageing from an unavoidable decline into an optimisation programme. A significant share of younger consumers is prioritising healthy ageing by adopting preventive practices such as cellular supplements, wearables, and epigenetic testing to extend health span rather than merely lifespan. Within this context, Khloé Kardashian’s KHLOUD protein popcorn exemplifies youth-oriented and health‑conscious positioning that capitalises on recent widespread appeal for accessible nutrition. Concurrently, the mainstreaming of menopause care, accelerated by social media communities and emergent brands such as Respin serving women in their forties and fifties, exposes a historically underserved category for life-stage solutions in the beauty and health industry. In developing markets, younger generations’ early adoption of wellness and longevity products is reinforced by sustainability considerations, further integrating health optimisation with sustainable consumption.
Parallelly, nostalgia marketing from legacy brands such as Levi’s and Polaroid taps into younger consumers’ yearning for eras they have never experienced, reflecting deeper anxieties about uncertain futures and a desire for perceived authenticity and stability from the past. This convergence creates a unique opportunity where older adults become valuable cultural transmitters rather than obsolete demographics - their lived experiences of nostalgic eras gain currency with younger generations seeking connection to ‘simpler times’, while their embodiment of successful ageing aligns with longevity wellness aspirations.
The result is a reframing where age becomes a bridge rather than a barrier, with older consumers positioned as pioneers and cultural custodians rather than declining market segments, fundamentally reshaping retail’s approach to intergenerational marketing and product development. Rather than recasting ageing for younger consumers, embedding older adults in product, content, and experience design so that communication embodies participation, not proxy representation is key.
Department stores bridging generations
Recently, Le Bon Marché hosted a cultural exposition entitled Rock’n’Drôle curated by renowned French television presenter Antoine de Caunes. Transforming the store and windows into a comprehensive celebration of rock and roll heritage, it encompassed a selection of vintage clothes and accessories reminiscent of the genre’s golden era, limited edition souvenirs and rare concert merchandise, as well as a space dedicated entirely to music complete with jukeboxes and vinyl records in collaboration with brands such as Kiloshop and Gibson, and collaborations with artists and animators including a surprise performance by Patti Smith.
The most notable feature, however, was the Rock Motel on the second floor which had ten themed rooms, each one paying tribute to ten icons of the genre including Elvis Presley, The Beatles, David Bowie and Patti Smith among others. The experience was enhanced by sensor-driven technology that triggered contextual narration throughout different areas of each room, with commentary provided by de Caunes’ cult persona Didier L’Embrouille from the French channel Canal+.
Perhaps unintentionally but significantly, the exhibition created meaningful intergenerational connections. Grandparents and parents were observed guiding younger family members through the installations, sharing anecdotes and contextualising the cultural significance of these musical icons for younger audiences. This organic knowledge transfer, as part of a technological showcase, exemplified how curated experiences can serve as a bridge between generations, demonstrating the growing trend of cultural programming to foster deeper customer engagement. John Lewis’ Christmas advertisement for the new ‘Where Love Lives’ campaign, showcases a similar sense of connection and nostalgia, taking viewers on a journey between a father and son, transported by music back to the 1990s.
During the same period, Galeries Lafayette presented a fashion and accessories curation by Sophie Fontanel, a French fashion critic, writer and influencer. She has been an avid commentator on ageing and deciding to go grey, having released a book on this topic, and stating that ‘the real anti-wrinkle is not caring’. Her curation was displayed across the ground floor and womenswear section at Galeries Lafayette Haussmann, however at the time of visit, there was negligible customer interaction. She is featured on the cover of the fall catalogue, and the photograph and her choice of products subvert age stereotypes by owning markers such as greying hair and wrinkles, despite the ironic advertisement for La Prairie’s Revitalising Essence promising ‘eternal youth’ in the catalogue. In an interview, she also discussed the impact of filters on younger generations and how wrinkles go beyond shaping one’s face to include every experience in one’s life.
Beyond youth targeting: the intergenerational dividend
The silver generation, comprising many grandparents, frequently assumes responsibility for the care of their grandchildren. This demographic generally enjoys financial stability and tends to indulge their grandchildren, prioritising expenditures on them over personal spending (in France, it is estimated that assets exceeding EUR 9 trillion will be transferred to the next generation by 2040 as the baby boomer cohort ages). Grandparents shop for their grandchildren and look for entertaining activities when they look after them, representing business opportunities for retailers. Department stores, in particular, should reflect on how shared experiences between grandparents and grandchildren might cultivate enduring customer relationships among younger generations. Furthermore, a fair part of Generation X remains financially prosperous and spends a significant portion of their resources on personal consumption, which is another business opportunity. Despite this, most visible marketing efforts among retailers usually focus on attracting younger generations. It is notable that two department stores simultaneously introduced substantial campaigns addressing ageing through distinct approaches. These examples show that retailers may begin to mainstream age inclusion as an engagement driver, with iterations likely to deepen intergenerational relevance by delivering participatory experiences across customer segments. By recognising the emotional and financial influence of older generations alongside the aspirational pull of younger consumers, programming that transcends age categories can strengthen intergenerational brand affinity if sustained strategically.
For the retail industry, this shift also represents a strategic imperative. As the majority of disposable income consolidates among older generations and wellness becomes a universal aspiration, retailers that prioritise healthy ageing and intergenerational engagement will be best positioned for long-term growth. Younger generations remain essential to sustained relevance; however, their engagement is most effective when embedded within intergenerational strategies that elevate the service, accessibility, and trust valued by older shoppers while integrating the discovery, wellness, and omnichannel expectations set by Gen Z and Millennials. Department stores have often served as settings for intergenerational traditions such as shared visits and gifting rituals between grandparents and grandchildren. These can be complemented by designing services that intentionally translate elder advocacy into younger loyalty, thus creating a continuum of influence across life stages. Department stores, in particular, have the spatial and experiential capacity to curate environments combining culture with commerce, strengthening brand loyalty beyond transactional relationships. By framing ageing not as an obstacle but as an opportunity for innovation, the retail industry can connect, include, and create enduring relevance in a world where longevity defines the future of consumption.
Conclusion: the next strategic mandate?
A future shaped by longer lifespans and shifting demographics demands a deeper commitment to normalising healthy ageing as part of everyday life, not just as a market trend. Rather than positioning older consumers as an isolated segment, department stores can serve as cultural and commercial hubs that integrate ageing into their narratives by highlighting wellness, vitality, and lived experience across all age groups. Embracing intergenerational programming, experiential retail, and nostalgic storytelling, these spaces can connect generations through shared cultural touchpoints, knowledge exchange, and collaborative participation. Such approaches move beyond the narrow ambition of attracting youth toward cultivating environments where the presence and participation of older adults are seen as enriching for everyone. In doing so, department stores retain their relevance as inclusive institutions capable of bridging generational divides, fostering community, and reframing ageing as a valued stage of life.
Credits: IADS (Anchita Ranka)
Patagonia 2025 Progess Report
Patagonia 2025 Progess Report
What: Patagonia’s inaugural sustainability report details the brand’s mixed progress in balancing environmental goals with business realities amid growing backlash against climate-conscious capitalism.
Why it is important: The report’s transparency and acknowledgment of setbacks set a new standard for accountability, reinforcing the need for collective action in the retail sector.
Patagonia’s first-ever sustainability progress report offers a candid evaluation of the brand’s journey to align profit with purpose over the past fifty years. While the company has made significant investments in conservation and supply chain improvements, it openly acknowledges that its environmental impact still outweighs its remediation efforts. The report highlights both achievements and persistent challenges, such as the difficulty of decarbonizing supply chains, managing product end-of-life, and scaling circular initiatives. Patagonia’s leadership recognizes that shifting political and cultural climates, including skepticism toward “woke” capitalism and regulatory rollbacks, have complicated its mission. Despite these headwinds, the company remains committed to transparency and urges the industry to move beyond competitive advantage toward collective action. By sharing its lessons and supporting tougher regulations, Patagonia aims to inspire broader change, even as it admits that no single company can solve the climate crisis alone. This honest self-assessment sets a benchmark for the retail sector, emphasizing that meaningful progress requires ongoing adaptation and collaboration.
IADS Notes: Patagonia’s report arrives as retailers like Falabella and Peek & Cloppenburg demonstrate how comprehensive sustainability strategies and experimental formats can drive both environmental and commercial success, as seen in May and January 2025. The growing demand for transparency and innovation, highlighted in February 2025, is matched by new regulatory requirements outlined in March 2025, while the April 2025 analysis underscores the importance of pragmatic adaptation amid political and operational challenges. These developments frame Patagonia’s efforts within a retail landscape increasingly defined by accountability and collective ambition.
Patagonia’s CEO on selling ‘the unsexiest thing in the world’

